



PW Consulting: Switches Market to Reach USD 26.55 Billion by 2032 at 8.82% CAGR

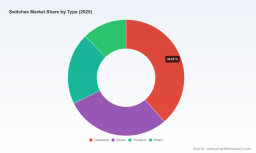
Switches Market 2026: Strategic Preview for C-Level Decision Makers
Executive trailer — why this matters in 2026
As global industry transitions accelerate in 2026, the switches market has moved from a component-level afterthought to a strategic fulcrum in product architecture, cost management and supply resilience. Our forthcoming Switches Market study — built on a 2025 base year and a 2020–2025 historical window, with forecasts through 2032 — captures the macro trajectory and the practical levers that will determine competitive advantage. At the market level, total revenues grew steadily across the historical period and are projected to expand at a compound annual growth rate (CAGR) of 8.82% through the forecast window, more than doubling certain addressable segments and driving new supplier-customer dynamics across industries.
Switches Market
What senior leaders need to know right now
-
Growth is tangible and sustained: The market is moving from single-point procurement to system-level buying decisions. The scale expansion expected by 2026 means procurement choices around specification, supplier partnerships and total cost of ownership will materially affect product margin and time-to-market.
Switches Market -
Consolidation is selective, not absolute: Market concentration metrics indicate a moderately consolidated environment where a handful of global players control a meaningful share, while a large long tail of specialized vendors remains commercially viable. This structure enables both strategic partnerships with established brands and focused plays by niche specialists.
Switches Market -
Operational pressures are real and quantifiable: Surveyed industry data shows near-term cost pressure driven by raw material volatility, regulatory constraints and labor inflation — practical impacts that procurement, product and operations teams must operationalize into scenario plans.
Macro trajectory — what the headline numbers tell you
From 2020 through the 2025 base year, the market demonstrated steady expansion as adjacent trends (industrial automation, EVs, smart consumer electronics and dense telecommunications infrastructure) increased unit demand and shifted feature requirements. Our forecast through 2032 models this momentum continuing at an 8.82% CAGR, underpinned by accelerating replacement cycles, greater functionality embedded in switch components, and wider adoption across emerging sub-segments. For strategy teams, these headline dynamics mean two simultaneous imperatives: scale to capture demand growth, and invest selectively to protect margin as product complexity rises.
Key demand drivers shaping 2026 decisions
-
Electrification and vehicle architecture evolution — As electrified mobility and electrified subsystems proliferate, switches move from low-visibility legacy items to mission-critical components with safety and thermal constraints.
-
Automation and control proliferation — Industrial and building automation increase the need for rugged, high-reliability switching solutions integrated into digital control systems.
-
Miniaturization and interface innovation — Consumer and professional devices demand smaller footprints and richer HMI (human-machine interface) capabilities, creating white-space for hybrid electromechanical and smart-switch solutions.
-
Telecom densification and edge compute — Network hardware modernization requires switches with tighter tolerances and longer service profiles, especially in harsh or remote deployments.
Constraints and risk vectors — what to stress-test in 2026 planning
-
Raw material volatility: Nearly half of manufacturers report cost pressure from fluctuating commodity prices for copper, plastics and specialty materials. Scenario modelling around ±20–30% raw material swings is now table stakes for procurement and pricing teams.
-
Regulatory & trade complexity: A meaningful share of industry respondents cite regulation, supply-chain disruption and import dependencies as constraints on market expansion in certain geographies — requiring supply diversification and compliance programs embedded in sourcing strategies.
-
Labor cost inflation: Measured labor cost rises have compressed manufacturing margins. Companies must evaluate automation, regional cost arbitrage and product redesign to preserve profitability.
Actionable strategic playbook for 2026
-
Procurement & supplier segmentation: Move from single-attribute sourcing (price or lead time) to supplier scorecards that weight technical roadmap alignment, raw-material hedging capability and regional footprint. Prioritize suppliers that offer co-engineering, lifecycle support and scaled manufacturing options.
-
Product architecture decisions: Adopt a variant-reduction program combined with platformized switch modules for fast-to-market configurations. This reduces SKUs and enables volume sourcing economics while maintaining configurability.
-
R&D and quality investment: Target investments in thermal resilience, contact wear mitigation and electrical noise immunity — features that increasingly differentiate premium offerings in adjacent markets such as automotive and industrial controls.
-
M&A and partnership criteria: Seek bolt-on acquisitions that expand functional breadth (e.g., smart-switch electronics) or regional footprint in low-cost/high-growth areas. Partnerships should be assessed on IP complementarity and manufacturing scale.
-
Commercial model adaptation: Consider outcome-based contracts for critical customers (uptime SLAs, lifetime replacement plans) and subscription-style consumable models for high-turnover applications to lock in recurring revenues.
What our report delivers — practical components (no raw tables)
The PW Consulting Switches Market study is designed as an operational toolkit, not a glossy summary. Key deliverables include a transparent forecasting methodology (base year 2025; forecasts 2026–2032), scenario pathways tied to macro cost drivers, a supplier strength-weakness-opportunity-threat (SWOT) construct aligned to product families, and a buyer decision matrix that maps technical specs to TCO and supplier risk. We provide price-sensitivity models, a supply-chain stress-test framework, and executive-ready slides for board-level investment decisions. To preserve commercial value for subscribers, we deliberately abstract granular segmentation tables from this preview — the full segmentation, regional flows and application-level forecasts are available in the subscriber report.
Competitive landscape — how to interpret positions and moves
The competitive topology blends global industrial conglomerates, regionally dominant players and focused niche manufacturers. Market concentration indicators show that the top three and top five firms collectively account for a material portion of market share, leaving room for specialists to capture premium niches. Below we synthesize strategic postures and capabilities of leading firms to inform your sourcing and partnership choices.
-
Eaton Corporation plc (Dublin, Ireland) — Eaton brings integrated power-management capabilities and a broad portfolio that spans low-voltage switchgear to application-specific switching solutions. Their strength lies in system-level integration and aftermarket service models, making them a logical partner for industrial and energy customers seeking end-to-end solutions.
-
ABB Ltd (Zurich, Switzerland) — ABB focuses on modular, digitally-enabled switching solutions tied to automation platforms. Their value proposition centers on interoperability and lifecycle analytics, targeting industrial modernization and grid-edge deployments.
-
Siemens AG (Munich, Germany) — Siemens leverages deep automation and control expertise to position switches as part of larger digital factory and building solutions. Emphasis is on high-reliability designs and integrated software for predictive maintenance.
-
Schneider Electric SE (Rueil-Malmaison, France) — Schneider emphasizes energy management and smart-building interfaces. Their switches often feature in holistic eco-systems that prioritize energy efficiency and connected control.
-
Honeywell International Inc (Charlotte, USA) — Honeywell’s offerings are focused on safety-critical and building-management applications, with an emphasis on certifications and sector-specific compliance.
-
Panasonic Corporation (Kadoma, Japan) — Panasonic covers a broad span from consumer-to-industrial electromechanical switches with strengths in miniaturization, manufacturing scale and reliability for consumer electronics.
-
Rockwell Automation, Inc. (Milwaukee, USA) — Rockwell combines industrial automation controls with rugged switching components, enabling tightly integrated solutions for factories moving toward digital operations.
-
Crouzet (Valence, France) — A specialist with niche mechatronic competencies, Crouzet competes on tailored designs for discrete automation and OEM applications where customization matters.
-
Bernstein AG (Höfingen, Germany) — Bernstein offers precision control switches optimized for industrial control panels and safety applications, appealing to customers needing deterministic performance.
-
E-SWITCH (Windsor, USA) — E-SWITCH is a highly focused manufacturer of electromechanical switches and tactile interfaces, with strengths in rapid product development cycles and component-level cost optimization.
-
Knitter-Switch (Essen, Germany) — Specialized in engineered switch solutions for high-end industrial and mobility applications, Knitter is known for performance under demanding environmental conditions.
-
Marquardt Management SE (Berg, Germany) — Marquardt focuses on automotive and consumer-interface switches, with deep OEM relationships and a roadmap aligned to next-generation vehicle interiors.
-
C&K Components (Newton, USA) — C&K supplies a broad portfolio of electromechanical switches with design-for-manufacturing capabilities and a strong presence with electronics OEMs.
How to use this preview in board-level planning
-
Use the report’s forecast scenarios to stress-test capital allocation for product lines where switches are a critical margin driver; small changes in unit cost or reliability assumptions can have outsized P&L effects.
-
Map supplier selection against regulatory and raw-material risk matrices included in the study to create a prioritized supplier-hedging plan for 2026 procurement cycles.
-
Evaluate potential M&A targets against the capability frameworks in our vendor diagnostic: look beyond revenue and assess IP fit, manufacturing depth and aftermarket reach.
Next step
This article is a strategic preview: it signals the opportunities, pressures and practical moves executives should contemplate in 2026. For the full empirical breakdown — granular segmentation, regional and application-level forecasts, supplier scorecards and downloadable scenario models — access the complete PW Consulting Switches Market report. The full report contains the detailed tables and annexes you will need to convert insight into investment decisions.
For detailed analysis of this topic, please visit the official page: Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


