



Copper Clad Laminate Market to Hit USD 27.17B by 2032 at 5.4% CAGR - Asia Pacific Leads

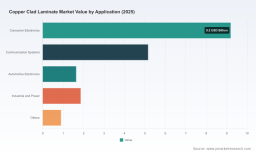
Copper Clad Laminate Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our Copper Clad Laminate (CCL) Market study designed to inform strategic decisions in 2026. This overview synthesizes market sizing, macro drivers, supply‑chain stress points, and competitive moves that will shape pricing power, capacity planning and product strategy over the coming seven years. The full report contains the granular, proprietary segment-level analytics and scenario models that senior leaders use to underwrite investment and procurement choices; this introduction demonstrates our analytical depth while intentionally withholding the specific segment splits to encourage direct access to the source study.
Copper Clad Laminate Market
Market snapshot — scale and trajectory
Our base year for the study is 2025 with a historical window covering 2020–2025 and a forecast horizon from 2026 through 2032. The market has expanded from approximately USD 15.1 Billion in 2020 to USD 18.76 Billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.4% through our projection period. By 2032, our central scenario sees the CCL market approaching roughly USD 27.2 Billion under prevailing technological and macroeconomic assumptions.
Copper Clad Laminate Market
That trajectory reflects several concurrent dynamics: steady demand from more complex printed circuit board assemblies, a structural shift toward high‑performance and frequency‑critical materials, and episodic but meaningful raw‑material‑driven pricing inflections. For corporate leaders, these topline figures are not mere headline metrics — they are the foundation for capital allocation, pricing strategy, and supply‑chain design decisions in 2026.
Copper Clad Laminate Market
Dynamics shaping 2026 decisions
-
Raw material volatility and cost pass‑through. Copper price behavior has been one of the dominant short‑term disruptors. In recent years the market experienced record highs and elevated averages — for example, copper benchmarks registered unusually high levels through 2024–2025. Commodity volatility remains a persistent input into laminate pricing and manufacturer margin profiles, and we model multiple copper scenarios in the report to quantify pass‑through timelines and elasticity of demand.
-
Changing treatment and refining economics. Global smelting treatment and refining charges (TC/RCs) have shifted materially compared with prior decades, altering the effective cost base of copper supply chains. These structural changes influence sourcing strategies, regional competitiveness and the attractiveness of vertical integration for downstream producers.
-
Trade policy and tariff noise. Tariff actions and import measures affecting copper-containing materials intensified cost swings in 2025. Trade policy remains a rapid‑response risk vector for procurement and pricing teams, particularly for producers and OEMs with cross‑border production footprints.
-
Demand composition change. Demand is being reweighted toward high‑frequency, high‑speed and multilayer applications — driven by AI server infrastructure, 5G/communications upgrades and advanced automotive radar/electronics. This is not simply a volume story: it’s a quality and mix shift that lifts average selling prices and capital intensity for suppliers.
Supply side — concentration, pricing power and capacity signals
The CCL market is concentrated; our concentration metrics show significant market share accruing to the top suppliers, creating distinct pricing and capacity implications. In practice, concentration translates into uneven bargaining dynamics across the value chain: leading integrated suppliers exert pricing discipline in tight markets and can accelerate capacity moves when order books backfill.
We observed concrete manifestations of that dynamic in the most recent corporate activity. A major producer announced a broad price increase across specifications in mid‑2026, raising standard CCL prices and increasing prepreg prices by larger increments. Other mid‑tier niche players report planned double‑digit revenue expansion in 2026 driven by targeted high‑frequency material offerings and realized price gains. Simultaneously, several large OEM‑grade material producers have disclosed capacity investments in Southeast Asia to support high‑performance multilayer demand — investments that reconfigure regional supply footprints and tilt competitive advantage toward firms that move swiftly.
For buyers and suppliers, these signals are the proximate determinants of contract strategy. Buyers face a choice: lock in multi‑year volumes at the expense of reducing supplier spot leverage, or modularize sourcing to capture technical premium segments. Suppliers must decide where to allocate limited capital — broad capacity buildouts or selective high‑margin specialty lines.
Competitive landscape — what the majors are doing
-
Integrated leaders expand selectively. Large players with diversified portfolios are focusing investments on high‑value materials for AI servers, RF and high‑speed boards. Their strategy combines targeted capacity additions with price discipline to protect margin during cyclical upswings.
-
Niche specialists scale vertically by technology. Firms targeting RF, high‑frequency and automotive radar applications are expanding production of specialty laminates and pursuing technical partnerships with PCB fabricators to lock in design wins.
-
Regional players optimize footprint for end‑market exposure. Several producers are reshaping regional manufacturing footprints to be closer to major consumer electronics and server manufacturing hubs; this reduces logistics risk and improves responsiveness to OEM qualification timelines.
Our full competitive benchmark includes granular profiles of the major industry participants, assessing manufacturing scale, product portfolio breadth, vertical integration, R&D intensity and near‑term capacity movements. That benchmarking underpins M&A readiness assessments, supplier scorecards and target lists for procurement-led consolidation.
What the report contains (practical sections for 2026 action)
-
Market sizing and three‑scenario forecasts. Base, upside and downside scenarios incorporating commodity shocks, demand elasticities and policy shocks.
-
Value chain and cost‑to‑serve analysis. Detailed manufacturing cost curves, input cost pass‑through lags, and break‑even utilization thresholds for different laminate classes.
-
Raw material sensitivity models. Copper price stress tests and hedging strategy playbooks that translate metal moves into board‑level cost implications.
-
Pricing and contracting playbook. Tiered contracting templates and dynamic escalation clauses designed to protect margins while retaining volume commitments.
-
Competitive benchmarks and capability maps. Side‑by‑side assessment of leading firms across capacity, product lines, and technological differentiation.
-
Strategic roadmaps. Decision frameworks for greenfield capacity, M&A, joint ventures and vertical integration under alternative demand paths.
These sections are supported by proprietary tables, supplier scorecards, and modelled P&L impacts under our forecast scenarios — content we reserve for the full report audience.
Actionable playbook for executives in 2026
-
Adopt a tiered procurement posture. For 2026, blend fixed‑price commitments for core volumes with flexible, indexed pricing for specialty or incremental volumes. This hedges against commodity swings while preserving access to capacity for critical high‑performance laminates.
-
Prioritize technical partnerships over spot buys. Qualification cycles for high‑frequency materials are lengthy; early co‑development and pilot commitments secure preferential allocation when suppliers tighten capacity.
-
Use scenario‑based capital gating. For suppliers, stage capacity investments with clear stop‑points tied to order visibility and lead‑indicator metrics (design wins, binding purchase agreements). Avoid broad capacity expansion in commodity grades when elevated copper prices amplify downside risk.
-
Operationalize copper risk management. Integrate metal exposure into procurement and treasury functions; evaluate a mix of physical hedges, long‑dated supply contracts and price indexation clauses.
-
Focus R&D on differentiated performance attributes. Insulate margin by accelerating materials that support AI, high‑speed interconnects and automotive safety systems — categories where customers accept premium pricing and qualification barriers deter new entrants.
-
Scan the M&A horizon. For both acquirers and targets, prioritize capabilities over scale: niche high‑frequency portfolios, regional market access and proven qualification pipelines provide outsized strategic value versus undifferentiated tonnage.
Why this report matters in 2026
Decisions made in 2026 will be outcome‑determinative for the next product cycle. The combination of elevated commodity prices, renewed trade policy uncertainty, concentrated supplier power and a demand shift toward high‑margin materials means that firms unable to translate market intelligence into procurement, investment and product strategies will concede margin or market share. Our study quantifies those trade‑offs and delivers operationally usable templates — from contracting language to capital gating rules — so C‑suite and business leaders can move from reactive to anticipatory mode.
We intentionally refrain from publishing the detailed regional and application splits in this preview because they are the core, actionable outputs clients rely on for competitive positioning. The full PW Consulting Copper Clad Laminate Market report contains those proprietary splits, the underlying model workbooks, supplier scorecards and scenario P&Ls that are essential for transaction support, negotiation, and capital planning.
Next steps — how to use this intelligence
-
Procurement leaders: request the raw material sensitivity module and the contracting playbook to operationalize price protection and supplier engagement plans for the upcoming negotiation windows.
-
Supply chain and operations: use our capacity and utilization thresholds to stress test expansion projects and to craft contingency plans for labor and logistics constraints.
-
Corporate development: leverage the competitive benchmark and M&A priority matrix to build a shortlist for strategic acquisitions or JVs focused on high‑frequency and multilayer assets.
In an environment of sustained structural change, timely, actionable market intelligence is the difference between capturing an outsized share of growth and becoming an involuntary price taker. PW Consulting’s full CCL Market study provides the models and playbooks needed to translate the macro trajectory into concrete 2026 choices. Contact PW Consulting to access the complete report, the underlying data models, and our bespoke advisory services for executing the actions outlined above.
For detailed analysis of this topic, please visit the official page: Copper Clad Laminate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


