



PW Consulting: Hydraulic Winches Market Poised at 7.47% CAGR Through 2032

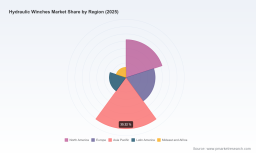
Hydraulic Winches Market — 2026 Strategic Brief
Executive summary
As we enter 2026, the hydraulic winches market sits at an inflection point. After compounding growth through the early 2020s, the global market reached a substantial scale in our 2025 base year and continues on a robust growth trajectory into the 2026–2032 forecast window at a compound annual growth rate of 7.47%. Our modeling projects continued expansion through 2032 underpinned by demand across marine & offshore, construction & infrastructure, and mining & oil & gas end-markets, while regulatory changes and raw material dynamics are re-shaping supplier economics and product requirements.
Hydraulic Winches Market
This briefing is an extract from PW Consulting’s full Hydraulic Winches Market study. It highlights the strategic value available to executives making investment, product, and go‑to‑market decisions during 2026. We deliberately present high-level, decision‑relevant signals here while reserving the granular segment tables, regional breakdowns, and company-level revenue detail for the full report.
Hydraulic Winches Market
Why this study matters for 2026 decision-making
- Market momentum and visibility: The market’s scale at the 2025 base year and the projected trajectory through 2032 create a clear opportunity set for product investment, capacity planning, and aftermarket monetization. Executives who align 2026 CAPEX and R&D roadmaps to this forecast window capture disproportionate upside.
- Regulatory tailwinds and compliance risk: New regulatory requirements that entered into force at the start of 2026 require enhanced certification, testing and in‑service verification for certain marine winch types. Compliance is rapidly becoming a minimum‑viable product attribute in export and offshore programs.
- Concentration and competitive dynamics: The market is moderately concentrated among established OEMs and specialist winch manufacturers; our competitive concentration metrics underline that the top three and top five suppliers account for a meaningful share of industry revenues, affecting supplier bargaining power and M&A opportunity sets.
- Supply chain fragility: Dependence on high‑strength steels, cables and precision gear components makes production sensitive to raw material availability and price volatility. Firms that secure supply or adopt material substitution strategies will enjoy margin resilience.
What the full PW Consulting report delivers (practical, executable content)
- Bottom‑up market sizing and scenario forecasts (2026–2032) including sensitivity to commodity price shocks, regulation, and capex cycles.
- Segment economics by duty class and application (methodology and drivers disclosed; granular revenue tables and regional splits available in the full report).
- Demand-driver diagnostics: vessel ordering trends, infrastructure programs, mining rigs, and heavy equipment replacement cycles mapped to winch demand.
- Regulatory impact assessment: technical, certification and retrofit implications of the latest SOLAS updates for marine and anchor handling winches, plus crosswalks to EN and ISO standards used in key manufacturing hubs.
- Supply chain and procurement playbooks: raw material sourcing risk heatmaps, alternative material paths, and vendor consolidation scenarios.
- Competitive benchmarking and CR analysis: product positioning, price architecture, aftermarket service revenue potential, and a ranked list of M&A targets by strategic fit.
- Commercial and product playbooks: go‑to‑market templates for new product launches, channel design for international distributors, and aftermarket service expansion models.
- Financial impact tools: margin sensitivity models, TCO calculators for end customers, and payback analysis for electrification or hybridization of winch systems.
Market dynamics — drivers and headwinds
Three forces dominate near‑term trajectories. First, end‑market demand from heavy industries and marine sectors is driving both replacement and new‑build orders. Second, regulation has moved from a compliance checkbox to a forward planning input — new SOLAS requirements effective in 2026 raise certification complexity and test requirements for certain anchor handling installations. Third, raw material volatility — particularly in high‑strength steels and specialized rope/cable supplies — injects both cost pressure and potential production interruptions.
Hydraulic Winches Market
For manufacturers, this means simultaneously optimizing for regulatory conformity, securing critical inputs, and accelerating product modularity so that one platform architecture can be reconfigured for different duty classes with minimal requalification. For buyers, it shifts evaluation criteria toward lifecycle compliance, documented testing histories, and service capability rather than just purchase price.
Competitive landscape: positioning and strategic moves
The market is populated by established OEMs, specialist independent winch builders, and regionally strong manufacturers. Our full study contains comprehensive profiles and capability matrices; below is a concise strategic snapshot of core players and tactical moves observed through late 2025 and early 2026.
- Ramsey Winch (Nampa, Idaho, USA) — Known for durable industrial and recovery hydraulic winches, Ramsey’s strength is brand recognition in heavy‑duty and off‑road applications. Their engineering DNA and aftermarket reach position them well for service‑led revenue growth.
- Pierce Arrow Inc. (USA) — Focused on heavy‑duty recovery and industrial ranges, Pierce Arrow’s portfolio addresses high‑capacity requirements where reliability and field serviceability are paramount. Their product spectrum supports utility fleets and industrial OEM integrations.
- Bloom Manufacturing (Independence, Iowa, USA) — A customization‑focused American manufacturer that competes on bespoke solutions for lifting and pulling across marine and construction segments. Their value proposition is high configurability and close customer engineering support.
- TWG / Tulsa Winch (Tulsa, Oklahoma, USA) — With planetary and industrial winch lines, TWG leverages catalogue breadth and aftermarket parts programs. Recent service kit catalog releases signal an emphasis on recurring revenue from servicing existing installations.
- Hammer Endüstri / Hammer Winch (Turkey) — A European‑standards producer with focus on towing, recovery and military applications. Compliance with regional standards enables export competitiveness into adjacent markets.
- Ningbo Xinhong Hydraulic (Ningbo, China) — A factory‑scale producer emphasizing integrated gearboxes and modular subassemblies designed for export. Their cost structure and manufacturing depth make them a supplier of choice for volume projects and OEM sourcing.
- Arrowhead Winch (USA) — Custom‑engineered solutions and manufacturing certifications (ISO 9001:2015; ISO 14001:2015) support complex industrial and hoisting applications, and recent distributor appointments point to an international growth agenda.
- Prowinch (USA) and Industrial Winch (Europe) — These specialists cover wide capacity ranges for construction, dredging and offshore; their value lies in scale variants and sector‑specific engineering.
- Thern (USA) — A legacy producer of robust industrial hydraulic winches with emphasis on heavy steel construction and lifting standards.
Recent tactical developments we track include new product introductions, catalogue and service‑kit updates, distributor network changes, trade show activity, and the regulatory change impacting marine winches that took effect in January 2026. Each of these events bears direct operational or go‑to‑market implications for suppliers and buyers alike.
Strategic playbook for 2026 (what executives should do now)
- Conduct a SOLAS and standards audit: ensure product families targeted at marine and anchor handling meet the new certification and testing requirements; prioritize retrofitable control and monitoring packages to minimize field downtime.
- Hedge critical raw materials and diversify suppliers: implement multi‑sourcing for high‑strength steels and ropes; explore composite or hybrid designs to reduce exposure to single‑source disruptions.
- Shift from unit sales to service economics: build aftermarket service packages, inspection regimes, and predictive maintenance offers that convert installations into recurring revenue streams.
- Modularize product architecture: design common subassembly platforms to reduce qualification cycles and accelerate entry into adjacent applications without large incremental R&D spend.
- Pursue selective partnerships and distribution deals: use distributor networks to enter new geographies quickly while evaluating M&A to acquire specialized capabilities or aftermarket footprints.
How to use this briefing and next steps to unlock the full study
This briefing is a strategic trailer: it surfaces the high‑value implications and actionable recommendations from PW Consulting’s Hydraulic Winches Market study while intentionally withholding granular segment tables, regional market shares, and company‑level revenue detail that form the core of the full intelligence product.
Purchasers of the full report receive detailed revenue by year and region, duty‑class splits, a ranked list of prospective acquisition targets by commercial fit, and downloadable financial modeling templates that allow you to stress‑test scenarios against commodity shocks and regulatory permutations. For procurement, product and M&A teams, the full dataset converts strategic direction into executable plans.
To access the full report, methodology appendix, and supplier models — or to commission a custom deep‑dive tailored to your product portfolio, geographic footprint, or acquisition screening — please reach out to PW Consulting. Our advisory teams are ready to translate the forecast, standards landscape, and competitive intelligence into a 90‑day action plan aligned to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Hydraulic Winches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


