



PW Consulting: Menstrual Cups Market to Reach USD 1,400 Million by 2032 at 5.8% CAGR

Menstrual Cups Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, decision-focused preview of our Menstrual Cups Market study — crafted to inform board-level choices, commercial prioritization, and capital allocation through 2026 and beyond. This introduction surfaces the analysis’ most consequential signals: market trajectory, regulatory inflection points, competitive positioning, and actionable strategic options — while intentionally withholding granular segment tables and proprietary splits to preserve the full consultancy value of the underlying research.
Menstrual Cups Market
Market at a glance
- Base year and recent momentum: Our base year is 2025. Between 2020 and 2025 the market expanded materially, reflecting stronger consumer adoption, product innovation, and distribution channel maturation.
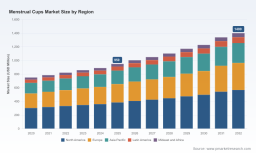
- Near and medium-term outlook: The market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.8% through the 2026–2032 forecast window. By our model the global market moves from roughly USD 950 million in 2025 to roughly USD 1.4 billion by 2032, underscoring a stable, mid-single-digit growth profile driven by reusable product adoption, regulatory clarity, and incremental product innovations.
- Structure and concentration: Market concentration remains relatively low compared with many medical-device segments — the top three players account for an estimated quarter of market revenue while the top five capture around two-fifths — a fragmentation that shapes tactical opportunities for new entrants, contract manufacturers, and M&A buyers.
Why this matters for 2026 decision-making
- Regulatory timing is a gating factor. With recent FDA actions aligning device quality systems to ISO 13485 and draft guidance focused on menstrual product performance and labeling, firms with weak regulatory preparedness face longer time-to-market and higher premarket costs. For 2026, regulatory readiness is a de-risking lever that executives should accelerate.
- Supply chain and materials: Almost all menstrual cups continue to rely on medical‑grade silicone (Class VI certified), which concentrates technical requirements (biocompatibility, molding controls) and supplier risk. Procurement choices made in 2026 will influence cost, speed, and compliance for several years.
- Product differentiation is now two-dimensional — functional performance (fit, leakproof life, antimicrobial treatments) and distribution model (direct-to-consumer vs. institutional programs). Both axes matter for 2026 go-to-market decisions.
- Market fragmentation creates roll-up and partnership opportunities in 2026. Strategic buyers can consolidate brand portfolios, scale manufacturing, or secure distribution nodes to accelerate growth above the market CAGR.
What the full report delivers (practical, executable content)
- Transparent methodology and audit-ready market sizing: historical reconciliation (2020–2025) and scenario-based forecasts (2026–2032) with sensitivity to pricing, adoption, and regulatory timelines.
- Segment-level frameworks and decision matrices: consumer archetypes, product-type mapping, material choices, and channel economics (note: granular public disclosure of specific splits is withheld in this preview).
- Regulatory playbook and compliance checklist: alignment with FDA classifications, 510(k) considerations where applicable, and ISO 13485 adoption implications for QMS and supplier audits.
- Competitive playbooks and supplier scorecards: profiles of core incumbents, contract manufacturers, and promising challengers with tactical options for partnerships, private-labeling, and white-label production.
- Manufacturing and cost engineering models: unit-cost drivers, scale inflection points, capital expenditure sizing for in-house vs. outsourced production, and raw material supply risk assessments.
- Go-to-market blueprints: channel prioritization, pricing ladders, launch milestones for product variants, and social-impact program structuring for institutional tenders and donors.
- M&A screening engine and integration plan templates: quick-reference investment cases, synergies mapping, and integration “first 100 days” templates for acquirers.
- Actionable annexes: supplier directories, inspection checklists, sample labeling language aligned to draft guidance, and ready-to-use board presentation slides.
Competitive landscape — what you need to know
The competitive field blends digital-first branded challengers, heritage brands, and specialized contract manufacturers. The market is characterized by branding and design differentiation, compliance credentials, and manufacturing certainty rather than pure price competition.
Menstrual Cups Market
- MeLuna (USA) — Strengths: differentiated sizing and TPE-based custom-fit options with multiple firmness and handle styles that cater to nuanced anatomical fit. Strategic implication: MeLuna’s EU-focused product launch in late 2025 shows how localization and body-positive positioning can expand market share in value-conscious segments.
- Saalt (USA) — Strengths: silicone-based product portfolio with clear positioning on leakproof protection and extended wear. Strategic implication: Saalt’s emphasis on consumer education and brand trust is a replicable playbook for premium DTC positioning.
- DIVA (USA) — Strengths: recognizable legacy brand with a market-leading reusable silicone cup and disc offering. Strategic implication: incumbents with strong brand recall remain attractive acquisition targets for buyers seeking immediate consumer trust.
- Voxapod (USA) — Strengths: domestic manufacturing of medical-grade silicone cups. Strategic implication: onshore manufacturing offers a compliance and supply-security premium that can justify higher price points in regulated markets.
- Cascobay Molding (USA) & Chemco Group (India) — Strengths: ISO 13485 certified and FDA-registered contract manufacturing capacity, positioning them as industrial partners for brands and OEMs. Strategic implication: companies seeking to scale rapidly in 2026 should prioritize due-diligence on such partners’ QMS maturity and regulatory history.
Industry dynamics and recent signals
- Regulatory: The FDA has clarified menstrual cups’ device classification and issued draft performance and labeling guidance. Crucially, the U.S. regulatory regime is moving to incorporate ISO 13485 into the device QMS framework effective February 2, 2026 — a hard deadline for firms to align processes.
- Product innovation: Recent product launches have moved beyond basic reuse economics to address real-world barriers — e.g., boil-free antibacterial formulations and body‑positive custom-fit ranges. These innovations reduce friction for adoption in low-resource settings and open institutional procurement use cases.
- Social procurement and NGOs: Philanthropic and NGO pilots — including recent donation programs — demonstrate sustained demand in institutional channels, a route to volume and public-sector credibility for brands in 2026.
Strategic playbook for 2026 (prioritized actions)
- Immediate (0–6 months): Conduct a regulatory readiness audit focused on ISO 13485 alignment and 510(k) pathways where relevant. Secure short-list of ISO 13485-certified manufacturers and initiate supplier audits for medical‑grade silicone sourcing.
- Near-term (6–18 months): Launch a two-track product strategy — a mainstream reusable offering for DTC/retail channels and a differentiated product (e.g., boil-free antimicrobial, custom-fit sizing) targeted at institutions and premium buyers. Pilot social-procurement programs to build institutional references.
- Medium-term (>18 months): Evaluate M&A or partnership plays to acquire distribution networks or manufacturing capacity. Use the market’s fragmented structure to consolidate smaller niche brands that provide access to new geographies or channel segments.
- Across all horizons: Invest in labeling and clinical-performance documentation aligned to the most conservative regulatory timeline (assume FDA draft guidance becomes binding). Maintain a 12–18 month regulatory buffer for product launches in markets that rely on U.S. clearance as a benchmark.
How to use this research
- Executive teams: Convert the scenario models into a prioritized investment plan with required capex, hiring, and vendor contracting milestones for 2026.
- Product teams: Use the material and performance matrices to select formulations and mold designs that minimize regulatory friction and maximize consumer comfort.
- Business development and M&A: Feed the competitive scorecards and concentration maps into target screeners and create rapid financial models for bolt-on acquisitions.
- Procurement and operations: Leverage supplier due-diligence templates and cost-engineering annexes to lock favorable long-term contracts for medical-grade silicone and molding capacity.
Conclusion — The market is maturing, not exploding. For executives making decisions in 2026, the imperative is clear: prioritize regulatory alignment, lock dependable medical‑grade supply chains, and choose a commercial model that balances brand-led premium positioning with institutional volume opportunities. The market’s mid-single-digit CAGR will reward disciplined execution and targeted consolidation.
Menstrual Cups Market
To access the full data tables, proprietary segmentation, supplier rankings, and the executable 100‑day integration templates referenced above, download the complete PW Consulting Menstrual Cups Market report from our website or contact your PW Consulting account director. The granular splits and model files are retained in the full report to preserve analytic integrity and to enable bespoke client workshops.
For detailed analysis of this topic, please visit the official page: Menstrual Cups Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


