



Security Ink Market Poised for 4.58% CAGR Through 2032 — PW Consulting Insight

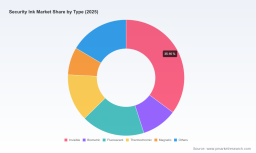
Security Ink Market — 2026 Strategic Preview
As organizations re-arm their anti-counterfeiting and authentication toolkits for the next strategic cycle, the Security Ink market deserves renewed executive attention. Our latest PW Consulting Security Ink Market research—anchored on a 2025 base year and a historical review from 2020–2025—shows a sector growing steadily into the forecast window of 2026–2032 at a compound annual growth rate (CAGR) of 4.58%. This growth trajectory, combined with a concentrated supplier landscape and accelerating regulatory change, creates a distinct set of strategic inflection points for buyers, suppliers, and investors in 2026.
Security Ink Market
Market snapshot that matters to decision-makers
-
Scale and momentum: The market has expanded consistently over the 2020–2025 period and is projected to continue that growth through 2032. This is not a nascent niche exercise anymore — it is an established, growing industry where incremental product and process innovation meaningfully affect returns on security investments.
Security Ink Market -
Supplier concentration: The market displays a measurable degree of concentration among leading providers (top‑3 and top‑5 firms capture a clear majority of sales). That concentration creates both supply‑side predictability for buyers who can secure long‑term arrangements and competitive pressure for mid‑tier players seeking differentiation through technology or service models.
Security Ink Market -
Regulation and raw‑material risk: Two dominant structural themes will dictate near‑term strategic posture — tighter raw‑material governance (notably in Europe) and volatile feedstock pricing driven by petrochemical cycles. Together these drivers compress development lead times and elevate the importance of compliant, resilient formulations.
Why our 2026-era clients cite this research as mission‑critical
-
Investment prioritization: The report translates projected growth and risk into prioritized areas for R&D, capacity expansion, and commercial focus—helping boards allocate capital where near‑term returns and strategic defensibility align.
-
Procurement & supplier strategy: Procurement teams receive an actionable framework for supplier segmentation, contract levers, and contingency planning calibrated to concentration metrics and supplier capabilities.
-
Regulatory compliance planning: With new industry guidance and charters emerging, organizations need a compliance roadmap that preserves performance while removing restricted chemistries from formulations and supply chains.
-
M&A and partnership scouting: For PE and corporate dev teams, the report highlights capability gaps across the value chain where acquisitions or JV structures can rapidly upgrade product portfolios or market access without technological reinvention.
What the PW Consulting report contains — practical, actionable, and field‑tested
-
Quantified market model: Historical baseline (2020–2025), a 2025 base year, and a granular forecast for 2026–2032 with scenario variants reflecting demand shocks and regulatory outcomes.
-
Segmentation architecture: A commercial view across types, end‑use applications, and geographies, paired with buyer personas and procurement cycles. (Note: this preview omits the detailed split data and modeling tables available in the full report.)
-
Vendor intelligence: Profiles of incumbent leaders and disruptive challengers with capability maps, go‑to‑market strategies, and technology roadmaps.
-
Supply‑chain playbook: Sourcing risk matrix, alternative feedstock assessments, inventory policy recommendations, and contract clauses to limit exposure to petrochemical price swings.
-
Regulatory & compliance toolkit: Step‑by‑step adoption roadmap for new material exclusion lists and GMP expectations, plus a compliance impact model for product portfolios.
-
Commercial templates: Pricing, TCO, and ROI models for pilots and scale rollouts; procurement scorecards; and negotiation playbooks aligned to supplier concentration realities.
-
Case studies & pilots: Documented implementations across currency security, tax stamps, product labels, and identity documents, including measured outcomes and lessons learned.
-
Risk scenarios & mitigation strategies: Stress tests that model supply disruption, sharp regulatory restrictions on key chemistries, and rapid shifts towards bio‑based or food‑safe inks.
Competitive landscape — who shapes the market and why it matters
The commercial map of the Security Ink market is anchored by a mix of specialized global leaders, diversified chemical companies with dedicated security portfolios, and nimble specialists focused on novelty pigments and tamper‑evident technologies. A concentrated top tier — where the largest three firms capture a notable portion of market revenues and the top five capture a substantially larger share — establishes the baseline for market conduct, pricing power, and R&D leadership.
-
SICPA Holding SA (Switzerland): The archetypal banknote and high‑security inks specialist. Their integrated authentication systems and deep relationships with central banks create high switching costs for some categories of demand.
-
Sun Chemical (DIC Corporation, United States): A scale player translating specialty ink capabilities into diverse applications. Recent product introductions illustrate a strategy of platformizing brand protection across fast-moving segments.
-
Gleitsmann Security Inks (Germany): A high‑precision supplier whose intaglio and secure‑printing chemistry competencies align it closely with legacy currency and securities clients.
-
OliKrom (France) and specialist pigment players: Focus on intelligent materials and color‑intelligence solutions that become primary differentiators in anti‑tamper offerings.
-
Regional and niche specialists (e.g., ARON Universal, Mingbo Anti‑forgery, NanoMatriX, Kao Collins, The Cronite Company, ANY Security Printing, Authentix): These vendors supply targeted capabilities—rapid prototyping, UV‑fluorescent pigments, localized regulatory knowledge, or embedded verification services—that create entry points for strategic partnerships and co‑development.
Implication: Buyers should combine long‑term agreements with leading incumbents to secure core supply, while channeling incremental spend to niche innovators for functionality that materially raises the cost of counterfeiting.
Recent industry shifts that change the playbook in 2026
-
Product innovation and platformization: Major suppliers continue to evolve from commodity inks to systems that combine inks, coatings, and authentication services—Sun Chemical’s 2026 launches are emblematic of this integrated approach.
-
Regulatory tightening in Europe: The adoption of new GMP expectations and a formalized raw‑material exclusion charter require manufacturers and formulators to revisit ingredient roadmaps and supply partnerships to maintain market access.
-
Supply volatility: Petrochemical feedstock price swings remain a live risk; manufacturers are increasingly testing bio‑based and food‑safe alternates to stabilize cost and broaden addressable applications.
Practical 2026 playbook — six priority moves for executives
-
Fast‑track a compliance inventory: Map which SKUs and formulations are exposed to new exclusion lists and GMP requirements. Prioritize re‑formulation for products with the highest revenue risk.
-
Adopt a two‑tier supplier strategy: Secure base capacity with top‑tier incumbents via multi‑year contracts while allocating an innovation budget to specialized suppliers for next‑generation pigments and verification tech.
-
Hedge feedstock exposure: Contract for mixed sourcing (petrochemical + bio‑based where feasible), and embed price‑pass‑through triggers that protect margins without sacrificing competitiveness.
-
Invest in authentication ecosystems: Move beyond stand‑alone ink purchases to bundled solutions that integrate inks with verification hardware/software and lifecycle services for sustained differentiation.
-
Explore targeted M&A or strategic partnerships: Identify mid‑tier specialists with additive technologies that can be rapidly scaled via incumbent sales channels.
-
Deploy the report’s pilot & TCO toolset: Use the provided ROI templates and stress scenarios to justify pilots to procurement and risk committees, shortening the path from proof of concept to scaled program.
Where this preview stops — and where the full report takes over
This strategic preview is designed to orient executives on the market dynamics, competitive positioning, and immediate actions for 2026. To preserve the tactical leverage that detailed segmentation, region/application splits, and unit‑level financial models provide, those core tables and granular datasets are reserved for the full Security Ink Market report. The complete study contains the exact segment breakdowns, price‑point matrices, supplier scorecards, and downloadable financial models that procurement, product, and corporate development teams require to execute with confidence.
For leaders needing to finalize 2026 budgets, supplier contracts, or innovation roadmaps, the full report delivers the connective tissue between strategic intent and operational execution. Contact PW Consulting or visit our Security Ink Market research page to request the full study, schedule a tailored executive briefing, or commission a bespoke variant of the model calibrated to your product portfolio and procurement footprint.
For detailed analysis of this topic, please visit the official page: Security Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


