



Electric Motorcycle Market to Reach USD 170.8B by 2032 at 18% CAGR — PW Consulting Insight

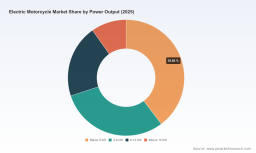
Electric Motorcycle Market — Strategic Briefing for 2026 Decisions
Executive summary
The electric motorcycle market is entering a decisive phase. After strong historical expansion from 2020 through 2025, the market is positioned for accelerated scale as incumbents and new entrants convert prototype momentum into series products. Our analysis uses a 2025 base year and projects the global market to grow at an 18% compound annual growth rate across the 2026–2032 forecast horizon, producing a multi-fold increase in industry revenue by the end of the period. For 2026 decision-makers, this is a growth window defined by rapid product launches, tightening safety regulation, cost curve improvements in battery packs, and a competitive landscape that is concentrated enough to enable strategic consolidation yet fragmented enough to reward focused specialization.
Electric Motorcycle Market
Why this matters for 2026 strategy
- Scale meets bifurcation: As overall market volumes expand materially in 2026, firms will face diverging fortunes depending on their ability to industrialize product lines, secure battery supply, and meet evolving certification requirements.
- Timing is strategic: 2026 is not only the start of a multi-year growth leg — it is the pivot year when prototype-stage programs from traditional OEMs move into production and when regulatory gating (safety, certification and vehicle classification) becomes binding for market access.
- Value capture shifts forward in the stack: Battery systems, power electronics, and platform software are increasingly decisive in value allocation; manufacturers that lock in integrated capabilities will command premium pricing and margin expansion.
Market trajectory and what the numbers tell us
Historical growth through 2025 demonstrates clear consumer and fleet-level uptake. With a 2025 base and an 18% CAGR through the 2026–2032 forecast window, the industry is set to more than treble in scale over the decade that follows. That pace of growth creates distinct horizons for investment: 1) capacity and tooling investments required to hit near-term production targets; 2) mid-term investments in charging and service networks to sustain adoption; and 3) longer-term strategic moves such as software monetization, subscription services, and cross-border expansion.
Electric Motorcycle Market
For executives planning capital allocation in 2026, the key takeaway is straightforward: commitments made this year — on supply agreements, certification programs, and channel partnerships — will determine whether a company participates meaningfully in the larger market or competes for a shrinking niche.
Electric Motorcycle Market
Drivers, constraints and operational dynamics
- Battery cost and chemistry: Battery pack cost improvements continue to be a primary driver of unit profitability and achievable range. Recent data shows a meaningful reduction in lithium-ion pack prices in 2025, which is already lowering entry barriers for higher-range models and opening new product segments.
- Regulation as a market-shaper: 2025–2026 regulatory updates (notably enhanced safety testing and certification requirements) are creating new compliance baselines. These standards raise the bar for new models but also create durable market advantages for manufacturers that certify early and build compliance into their design processes.
- Channel and service ecosystems: Real-world ownership economics hinge on charging availability, aftersales service, and parts distribution. OEMs and distributors that secure service footprints and certification for battery swapping or DC fast charging will accelerate fleet and consumer adoption.
- Product segmentation shifting: While legacy low-speed electrics remain relevant in certain use-cases, mid- and high-performance segments are expanding as OEMs introduce street, trail, and dual-sport electric models with broader appeal to mainstream riders.
Competitive landscape — implications for incumbents and entrants
The competitive field in 2026 reflects a mix of established electric-native brands, traditional motorcycle OEMs transitioning to electrics, and new mobility players. Market concentration is moderate: the top three players account for roughly one-third of industry revenue and the top five do not exceed half of the market. This structure supports both scale advantages for larger players and meaningful opportunities for focused challengers.
- Electric-native specialists: Firms that started as electric-only manufacturers have advantages in platform modularity, battery integration, and brand positioning among early adopters. Their challenge is industrial scale — turning boutique performance models into high-volume, margin-stable product lines.
- Traditional OEMs going electric: The entry of legacy manufacturers into full-size electric motorcycles represents a strategic inflection. These incumbents bring dealer networks, manufacturing scale, and channel trust, but must accelerate learning curves in software, battery management, and fast-paced product cycles.
- New product launches and timing: Several high-profile product introductions scheduled for 2026 — including full-size and dual-sport electric models from both legacy OEMs and newer brands — will force a re-evaluation of pricing architectures and market segmentation across urban, touring and off-road categories.
- Certification and regional compliance as moat: Early certification in major markets creates effective barriers to late entrants and forms a defensible commercial advantage for those who invest first in compliance testing and homologation.
Key players — strategic read of recent moves
- Specialists that balance performance with industrialization: Brands known for high-performance electric motorcycles have proven R&D and product credibility; their near-term challenge is improving manufacturing throughput while broadening their model portfolios to address mass-market requirements.
- Legacy OEMs broadening portfolios: Established manufacturers entering the electric space in 2026 bring scale and channel advantages and will push price pressure on performance segments. Their presence will accelerate consumer familiarity with electric motorcycles and expand addressable demand.
- Global OEMs with regulatory and distribution strengths: Players offering globally compliant products and capable of navigating diverse homologation regimes will win rapid distribution deals, particularly where safety standards have been newly codified.
- Cross-regional suppliers and low-cost volume players: Firms that successfully offer certified, cost-competitive platforms will capture fleet and last-mile demand; however, their long-term margin trajectory depends on product differentiation beyond cost alone.
Supply chain, cost and regulatory risk matrix
- Raw materials: Downward pressure on battery-pack prices in 2025 provides a tailwind but also signals intense supplier competition. Procurement teams must balance short-term cost savings with multi-year supply security and technology lock-ins.
- Certification requirements: New mandatory standards for rechargeable energy storage systems and vehicle-level safety testing require earlier and deeper investment in validation. Firms that defer compliance risk delayed market entry and higher retrofit costs.
- Vehicle classification and operating rules: Changes in vehicle code definitions for off-highway and street-legal classifications affect product positioning, distribution, and aftersales obligations. Early legal and regulatory strategy will reduce go-to-market friction.
Strategic playbook for 2026 — prioritized actions
To translate market opportunity into durable advantage in 2026, firms should prioritize decisive, time-bound moves across five dimensions:
- Secure battery and subsystem supply with staged commitments. Negotiate layered contracts that provide near-term cost certainty while preserving flexibility to adopt next-generation chemistries.
- Invest in certification and homologation early. Allocate budget and technical resources to meet new safety and overcurrent testing regimes; certifications secured in 2026 will function as commercial permits to scale in 2027–2028.
- Define a clear product-to-channel alignment. Decide which segments to lead (performance, commuter, dual-sport) and map each to the most realistic distribution model — direct retail, dealer network, or fleet tenders.
- Build service and digital ownership experiences. Establish warranty structures, predictive maintenance programs, and connected services that increase residual value and create recurring revenue opportunities.
- Prioritize M&A and partnerships strategically. Consider acquiring niche battery system integrators, regional distributors with service networks, or software providers to accelerate time-to-market and close capability gaps.
What the full PW Consulting report delivers
The full Electric Motorcycle Market report provides actionable modules designed for executive decision-making:
- Comprehensive market sizing (historical 2020–2025 and detailed forecasts to 2032) and scenario modeling tailored to different regulatory and cost paths;
- End-to-end commercial playbooks for OEMs, suppliers, and mobility operators (go-to-market, channel economics, and service strategies);
- Detailed competitive benchmarking and acquisition targets mapped to strategic objectives (including capability heatmaps and integration considerations);
- Supply chain risk matrices and procurement templates for battery sourcing, powertrain components, and critical electronics;
- Regulatory impact analysis with compliance roadmaps for major jurisdictions and certification timelines;
- Executive dashboards and implementation checklists that convert insights into 90/180/360 day action plans.
Note: This briefing deliberately omits the granular regional and application-level splits and other detailed segmentation tables reserved for the full report. Those granular schedules are a critical part of scenario-based decisioning and are available in the source report.
Practical next steps for leadership teams
- Convene a cross-functional 60-day task force (product, supply chain, regulatory, sales) to convert these strategic priorities into decision points with specific owners and budget requests.
- Use the 2026 window to pilot certification-first engineering programs for at least one platform to reduce time-to-market risk for subsequent variants.
- Reassess pricing strategy in light of battery cost improvements and competitive product launches — aim for a test-and-learn approach with selective market-entry discounts tied to service commitments.
Conclusion — why PW Consulting’s insight is decision-critical in 2026
The market dynamic entering 2026 rewards decisiveness: the combination of accelerating demand, rapid product introductions from both electric-native and legacy OEMs, and tightening safety and certification regimes creates a high-reward window for first movers who are operationally prepared. Our analysis provides the strategic framework and operational toolkits needed to convert market growth into sustained competitive advantage. For teams preparing budgets, channel strategies, or M&A plans in 2026, the choices made now will have outsized impact on market share and profitability across the forecast period.
To access the full datasets, regional and application segmentation, and the implementation templates referenced above, consult the complete PW Consulting Electric Motorcycle Market report available on our website.
For detailed analysis of this topic, please visit the official page: Electric Motorcycle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


