



PW Consulting: Assistive Tech for Visual Impairment to grow at 7.21% CAGR through 2032

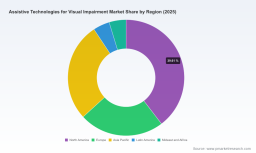
Assistive Technologies for Visual Impairment: Strategic Insights for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused executive preview of our new market study on Assistive Technologies for Visual Impairment. This briefing is written to help executives, investors, product leaders and public-procurement teams understand the strategic value of the full report for decisions to be made in 2026. It illustrates the market’s trajectory with high-confidence macro metrics, synthesizes the structural dynamics shaping opportunity and risk, and outlines the tactical playbook that the full study delivers — while preserving the granular segment-level figures that drive deal-level and product-level decisions (available in the full report).
Assistive Technologies for Visual Impairment Market
Why this study matters in 2026
The assistive technologies market for blind and low-vision users is no longer a niche: it is a steadily expanding ecosystem where hardware, software, AI and policy converge. Our analysis shows the market grew from USD 163.15 Million in 2020 to USD 215.0 Million in 2025 (base year). Under base-case assumptions and current technology and policy trajectories, the market is forecast to expand to USD 230.08 Million in 2026 and to USD 344.8 Million by 2032 — a compound annual growth rate (CAGR) of 7.21% over the 2026–2032 forecast period. These macro figures demonstrate a durable growth runway attractive to product investors, strategic acquirers, and policy makers focused on accessibility outcomes.
Assistive Technologies for Visual Impairment Market
High-level market character and concentration
- Growth profile: The market has shown consistent year-on-year expansion through 2025 and enters 2026 with momentum driven by improved device affordability, AI-enabled capabilities, and expanded procurement mandates in public and enterprise sectors.
- Competitive structure: Market concentration is low-to-moderate. The top three players account for roughly a quarter of market revenues and the top five for a little over one quarter — a structure that signals meaningful room for regional specialists, innovative entrants, and vertical integrators to scale via product differentiation or partnership strategies.
- Innovation drivers: Rapid progress in computer vision, on-device AI, miniaturization of optical systems, and cloud-based accessibility services is creating a steady stream of product upgrades and adjacent-service opportunities (e.g., workflows for education, workplace accommodations, and independent living).
Policy, reimbursement and procurement dynamics — the near-term levers
Market growth is not solely technical. Policy and payment systems are decisive near-term levers:
Assistive Technologies for Visual Impairment Market
- Reimbursement friction: Key public programs in major markets exclude many low-vision aids from coverage (for example, Medicare does not cover numerous electronic magnifiers). Globally, only a minority of insurers provide coverage for assistive devices, constraining demand elasticity and creating a reliance on public procurement and out-of-pocket purchases.
- Public procurement tailwinds: Regulatory updates mandating accessibility in government procurement (notably Section 508 refresh standards in the U.S.) are expanding addressable spend in public and quasi-public channels. This is a durable demand signal for vendors that can meet compliance and verification requirements.
- Global norms and standards: International forums — such as the WHO Global Forum on Medical Devices — have recently emphasized quality and safety standards for assistive technologies, increasing the compliance burden but also raising barriers to low-quality entrants and enabling premium positioning for trusted brands.
- Budgetary constraints: Public-health procurement is frequently delayed or rejected due to restricted budgets, with material proportions of assistive-technology requests affected. This dynamic favors companies that can demonstrate total-cost-of-ownership improvements, scalable service models, or blended financing solutions.
What the full report delivers (practical, decision-ready outputs)
Our full market study is designed to move leaders from awareness to action. It combines quantitative market architecture with executable strategy tools:
- Validated market sizing and a seven-year forecast model (2026–2032) with scenario analysis, sensitivity testing, and breakouts by device type, application, and region.
- Buyer and channel archetypes, including procurement decision criteria used by educational institutions, health systems, employers, and consumers.
- Detailed reimbursement and regulatory map covering major markets, procurement triggers, and certification pathways tied to the latest WHO and national standards.
- Competitive intelligence dossiers on leading vendors and a prioritized list of challengers, including product portfolios, route-to-market, pricing posture, and M&A activity signals.
- A product-to-market playbook: route-to-procurement playbooks for public tenders, schools, enterprise disability services, and consumer-direct channels; go-to-market ramp plans and pricing frameworks informed by willingness-to-pay research.
- M&A and partnership screening: a short-list of target archetypes, valuation multipliers observed in adjacent assistive-tech deals, and integration risks.
- Implementation checklist for clinical validation studies, interoperability and accessibility testing, and user-experience validation involving persons with lived experience.
Competitive landscape — read between the lines
The market is populated by a mix of specialized device manufacturers, legacy assistive-technology providers, nonprofit innovators, and fast-moving AI startups. The full report includes company profiles and comparative matrices; here are the strategic takeaways:
- Established hardware specialists (e.g., companies with long histories in Braille displays, tactile devices, and electronic magnifiers) hold trusted relationships with educational institutions and rehabilitation networks. Their strengths are product durability, service contracts, and channel depth; their challenge is accelerating software and AI integration.
- Software-first players and accessibility platform vendors have strong traction in screen readers, OCR-based solutions and enterprise accessibility suites. They are advantaged in rapid feature delivery, cloud services and enterprise contracts, but often lack end-user hardware control.
- Wearable and AI-native entrants are re-shaping mainstream expectations for on-the-go recognition and navigation. These players can capture consumer demand outside traditional procurement channels but must scale clinical validation and durable distribution pathways.
- Nonprofit and educational institutions are influential ecosystem stakeholders — both as purchasers and as validators of accessibility outcomes — and new product acceptance often hinges on their endorsement.
Representative names profiled in the report include leading device and solution providers, from traditional Braille and low-vision device manufacturers to AI-enabled wearable innovators. One notable recent development: in April 2026 Perkins School for the Blind unveiled the Perkins Braille Bloom, a digital companion that connects classic Perkins Braille devices to modern screens — an example of legacy-digital convergence that typifies near-term product strategies.
Strategic implications for 2026 planning
Executives planning actions in 2026 should prioritize three parallel tracks:
- Product and technology: Accelerate development of hybrid solutions that pair durable hardware with cloud-enabled services and on-device AI. Invest in interoperability (Braille, AR/vision APIs) and modular service bundles to increase addressable channels.
- Go-to-market and partnerships: Pursue validated pilot partnerships with educational systems and rehabilitation centers to de-risk procurement cycles. Explore bundled financing models and third-party rehabilitation service partnerships to address reimbursement gaps.
- Regulatory and advocacy engagement: Actively track and influence standard-setting forums, and build a compliance-first product roadmap. Demonstrable alignment with WHO quality standards and federal accessibility procurements unlocks large contracts and reduces tender friction.
Risk calibration and near-term opportunities
- Risks: Payment friction (lack of systematic reimbursement), procurement delays driven by constrained public budgets, and rapid obsolescence risk as AI capabilities shift expectations.
- Opportunities: Section 508-style procurement mandates, validated proof points with education systems, and premium positioning via demonstrated clinical and usability outcomes create high-value entry points for players that can navigate reimbursement or offer innovative financing.
How to use the full report in your 2026 playbook
Use our full study to accelerate specific 2026 decisions:
- For investors: identify acquisition targets that fill product-service gaps and have validated procurement relationships; use the report’s scenario models to stress-test valuations under different reimbursement assumptions.
- For OEMs and platform players: adopt the product-to-market playbook and tender templates to compress sales cycles and reduce pilot-to-contract time.
- For public purchasers and NGOs: leverage the procurement playbooks and standards matrix to design compliant tenders and scale assistive-technology deployment efficiently.
Next steps
This briefing highlights the strategic contours and the macro growth story; the full PW Consulting report contains the segment-level granularity, pricing benchmarks, regional and application breakouts, and company scorecards needed to execute and quantify 2026 initiatives. If your team is prioritizing market entry, product investment, strategic partnerships, or procurement reform in 2026, the full study provides the actionable intelligence and execution templates required to move from strategy to measurable outcomes.
For detailed analysis of this topic, please visit the official page: Assistive Technologies for Visual Impairment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


