



PW Consulting: Smart TV Market to Reach USD 542.6B by 2032 at 11.9% CAGR

Smart TVs Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
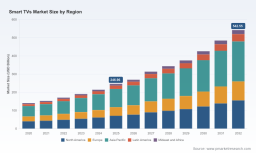
As corporate leaders map their 2026 playbooks, few markets present as many converging opportunities and risks as Smart TVs. Our latest PW Consulting market research — anchored on a 2025 base year and projecting through 2032 — synthesizes five years of historical momentum (2020–2025) with forward-looking scenario analysis to deliver decision-ready insight. The headline: the global Smart TVs market has moved from a sizeable consumer electronics category into a strategic technology frontier, expanding at a compound annual growth rate (CAGR) of 11.9% and more than doubling in scale across our forecast horizon.
Smart TVs Market
Why this research matters for 2026 decision-making
2026 will be a pivot year. Companies face simultaneous pressure from component cost inflation, regulatory change, and intensifying competition at both premium and value tiers. Our brief translates those pressures into three actionable decision levers for 2026 leaders:
Smart TVs Market
- Portfolio prioritization: where to increase R&D and capex to defend margin while capturing growth.
- Supply-chain resilience: tactical levers to mitigate semiconductor and memory price shocks that are already feeding through retail prices.
- Monetization and compliance: how to balance platform-level monetization (ads, subscriptions, services) with new data-rights requirements and cross-border trade frictions.
These levers are grounded in the market’s scale and trajectory. In absolute terms, the Smart TVs market expanded markedly during 2020–2025 and enters 2026 with a materially larger base than a half-decade ago; under our central forecast the sector continues to scale rapidly through 2032. For commercial leaders, that trajectory means the next two years are essential for securing platform positions and establishing upstream supplier relationships that will determine total share and margin performance through the decade.
Smart TVs Market
What the market dynamics tell us
Several macro and micro dynamics are reshaping competition and economics in Smart TVs today:
- Component-cost inflation: TV-specific DRAM surged and flash memory costs doubled in the past year due to demand from AI infrastructure; semiconductor cost escalation is a cross-cutting input pressure. Manufacturers and OEMs must prepare for continued input-price volatility and potential retail-level price adjustments in 2026.
- Regulatory shifts: The EU Data Act (effective 12 September 2025) redefines user control over connected-device data — a direct influence on how Smart TV platforms collect, process, and monetize viewing and usage data. Compliance is both a cost and an opportunity; companies that embed privacy-by-design can differentiate and unlock new B2B services to content partners.
- Trade and tariff noise: Reinstated trade measures on select AV imports in 2025 introduce renewed cross-border cost asymmetries. Firms with globally diversified manufacturing footprints or flexible sourcing will be better positioned to manage margin compression.
- Product innovation cycle: 2026 product announcements from major suppliers underline a bifurcation: premium image- and AI-centric platforms vs. aggressive value plays emphasizing scale and OS partnerships. The pace of portfolio refresh has accelerated, making timing and channel execution more critical.
Competition — what to watch
The Smart TVs market remains concentrated among a small set of global incumbents. Our concentration analysis shows the top three firms control a meaningful majority of the market, with the top five commanding an even larger share. That structure creates a dual reality: incumbents can shape standards and platform economics, while mid-tier challengers can exploit narrow gaps through price-technology arbitrage, channel innovation, and service differentiation.
Key players and strategic pointers (executive snapshot):
- Samsung Electronics (HQ: Seoul, South Korea – https://www.samsung.com/us/): Continues to push premium features and AI integration. Recent 2026 moves include refreshed Neo QLED 4K models, a Mini LED lineup, and the introduction of a platform-level AI companion — signaling a combined hardware-plus-software monetization strategy.
- LG Electronics (HQ: Seoul, South Korea – https://www.lg.com/us/): Sustains leadership in panel innovation and form factor. 2026 announcements highlight RGB Mini LED and OLED variants, which maintain LG’s emphasis on premium display performance and differentiated content experiences.
- Sony Group Corporation (HQ: Tokyo, Japan – https://sony.com/en/): Leverages brand strength and imaging IP to command the premium cinematic segment. Sony’s strategic assets are its content relationships and image-processing prowess — critical as consumers pay a premium for superior visual and audio experiences.
- TCL Electronics (HQ: Huizhou, China – https://us.tcl.com/): Operates as a scale challenger that blends aggressive price positioning with strategic OS partnerships and localized channel playbooks. Ideal for organizations focused on share growth through cost and distribution efficiencies.
- Hisense Group (HQ: Qingdao, China – https://www.hisense.com/): A fast-follower on Mini LED and aggressive US-market product launches (notably the 2026 CES lineup), targeting value-conscious segments while expanding premium variants.
- VIZIO (HQ: Irvine, California, USA – https://www.vizio.com/en/home): Plays a distinctly U.S.-centric role with emphasis on platform-level monetization and an established path-to-market in big-box retail channels.
Recent corporate moves in early 2026 underline these dynamics: Samsung’s 2026 OLED and Mini LED upgrades and platform AI positioning; LG’s RGB Mini LED and OLED pushes; and Hisense’s 2026 U.S. introductions that reinforce the intensifying battle along quality and price vectors. These initiatives will shape channel negotiation, R&D allocation, and co-marketing strategies for the year.
What’s inside the PW Consulting brief (practical deliverables)
Our research is designed as a practical toolkit for executives, with granular modelling and scenario outputs you can deploy directly in your 2026 planning cycle. Highlights include:
- Market sizing and forecasting (2020–2032) with base-year validation and sensitivity bands under alternative macro scenarios.
- Segment-level narratives and growth vectors (by panel technology, application, and region) with downloadable templates to re-run the model under custom assumptions.
- Supplier and input-cost stress test: component-price modelling (DRAM, flash, semiconductors, backlights) and the estimated passthrough to retail pricing under multiple elasticity assumptions.
- Competitive benchmarking and M&A heatmaps: capability overlays that identify likely acquisition targets and partnership fits for incumbents and challengers.
- Commercial playbooks: recommended go-to-market approaches for premium vs. value segments, including channel mixes, subscription strategies, and ad-platform monetization roadmaps.
- Regulatory and data governance checklists aligned to recent rules (e.g., EU Data Act) and practical compliance architectures that minimize user-friction while preserving monetization potential.
- Scenario planning frameworks covering tariff shocks, component scarcity, and rapid platform adoption — each with contingency playbooks and P&L sensitivity impacts.
Note: In keeping with our “trailer” approach, we demonstrate methodological transparency and provide high-level outputs here, while detailed tabular segment data and company-level scorecards are accessible in the full report.
Strategic implications and recommended 90–180 day actions for 2026
Based on the research, PW Consulting recommends an immediate set of prioritized actions to convert market growth into durable advantage within 90–180 days:
- Lock in upstream supply: Negotiate multi-year component agreements with price collars or indexation clauses to manage DRAM/flash volatility; explore strategic inventory buffering for critical SKUs.
- Rebalance portfolios toward value-accretive SKUs: Prioritize product variants that combine differentiated UX (AI-enhanced content discovery), durable hardware features (Mini LED/OLED where appropriate), and service attach points (subscriptions and warranty upsells).
- Operationalize data governance: Implement EU Data Act–aligned consent frameworks and a privacy-first telemetry layer to preserve platform analytics capabilities while minimizing regulatory exposure.
- Price and channel optimization: Run rapid elasticity tests in targeted channels; calibrate promotional intensity against forecasted input-cost passthrough and competitor moves.
- Pursue selective partnerships: Identify content and OS partners that can accelerate user engagement and reduce CAC — focus on integrations that improve retention and ARPU, not only one-off sales.
- Evaluate consolidation opportunities: Given market concentration among the top players, mid-tier firms should prioritize bolt-on targets that fill capability gaps (e.g., AI software, content licensing) and create defensible niches.
Final perspective
The Smart TVs market in 2026 is no longer only about pixels; it is a crossroads of hardware economics, software platforms, regulatory frameworks, and content monetization. For leaders, the central question is how to convert the sector’s robust growth trajectory into a durable, differentiated business model before competitors lock in platform advantages. Our new research provides the data, scenarios, and executable playbooks to inform those choices — from boardroom strategy down to SKU-level margin decisions.
To access the full set of tables, the detailed segmentation matrix, company scorecards, and downloadable modelling templates that underpin the conclusions above, please consult the complete PW Consulting Smart TVs Market report.
For detailed analysis of this topic, please visit the official page: Smart TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


