



PW Consulting: Aluminum casting market to reach USD 166.7B by 2032 (4.98% CAGR)

PW Consulting Perspective: Aluminum Casting Market — Strategic Imperatives for 2026
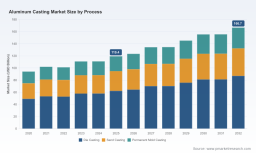
Between 2020 and 2025 the global aluminum casting market demonstrated resilient expansion, rising from approximately USD 94.3 billion to USD 119.4 billion. Our base-year assessment (2025) and forward view to 2032 project continued growth to roughly USD 166.7 billion, representing a compound annual growth rate of about 4.98% over the forecast window. For corporate leaders preparing capital allocation, sourcing, and M&A decisions in 2026, these topline dynamics matter — but only as a starting point. The critical decisions will be shaped by where value migrates across processes, end markets, geographies and technology choices — subjects we analyze with operational depth in our full study.
Aluminum Casting Market
Why 2026 Is a Strategic Inflection Point
2026 is not merely the next year on the calendar; it is the point at which multiple structural drivers converge to reshape competitive advantage in aluminum casting. The sector is being re‑priced by three simultaneous forces:
Aluminum Casting Market
- Regulatory re‑calibration: Carbon border mechanisms and new trade remedies are recasting the cost profile for traded aluminum and downstream cast goods.
- Raw material and input volatility: Alumina and bauxite cost cycles and shifting global supply patterns are compressing margins for unconsolidated producers and advantaging vertically integrated players and recyclers.
- Technology and product evolution: Lightweighting demand from transportation and structural electrification create differentiated value for castings that combine design complexity with high repeatability.
These shifts mean that companies that treat 2026 as “more of the same” risk being outcompeted by firms that accelerate process innovation, circularity initiatives, and defensive commercial strategies.
Aluminum Casting Market
Market Trajectory — Interpreting the Numbers
The macro trajectory we model is unambiguous: a clear recovery through 2025, modest acceleration in 2026‑2029, and compounding improvement into the early 2030s driven by structural end‑market demand and higher recycled-content utilization. Growth is meaningful but not hyperbolic — implying that scale, efficiency and value‑chain integration will dictate winners. The market concentration metrics reinforce this point: the top three players control a material but limited share of demand, and the top five capture roughly half the market, indicating room for consolidation and targeted scale plays.
Value‑Chain Dynamics and Cost Exposure
Value creation and margin resilience in 2026 will depend on three linked competencies:
- Input management and feedstock strategy: With alumina and bauxite supply patterns shifting and price volatility elevated, procurement strategies that combine long‑term offtake, diversified sourcing and integrated recycling deliver superior predictability.
- Process selection and optimization: Casting processes (including high‑pressure die casting, sand casting and permanent mold techniques) differ in capital intensity, cycle time, scrap rates and engineering flexibility. The optimal mix is application‑specific and must be evaluated against total cost of ownership rather than unit price alone.
- Carbon and regulatory pass‑through capability: Carbon border measures and duties on upstream materials require transparent carbon accounting, product traceability, and commercial frameworks to preserve margins when costs are externalized into supply chains.
Our full report maps these exposures to plant archetypes and provides a prioritized remediation matrix for procurement, operations and commercial teams.
Technology, Decarbonization and Circularity — Where to Invest
Technology and sustainability are no longer “nice to have.” They are primary economic levers. In 2026, executives should treat three investment categories as first‑order priorities:
- Recycling and secondary metallurgy: Increasing recycled aluminum content reduces exposure to upstream price cycles and to certain trade measures. Investments in scrap sorting, remelting and alloy control yield rapid payback in volatile markets.
- Low‑carbon process deployment: Demonstrated low‑carbon casting footprints create differentiated access to customers subject to carbon compliance and help avoid margin erosion from border adjustments.
- Advanced casting automation and simulation: Digital process controls, die life optimization, and integrated simulation reduce scrap and speed new product introduction — critical where design complexity meets high volume.
Major industry participants are already advancing these levers. Examples include large integrated producers that emphasize alloy innovation and zero‑carbon casting programs, and precision die casting specialists that invest in process repeatability and tight tolerances for electrified powertrain components.
Competitive Landscape — Strategic Postures and Implications
The competitive field is heterogeneous: vertically integrated primary producers, precision die casters, and component specialists coexist with regional foundries and engineering‑led suppliers. Understanding where each player derives advantage is essential for partnership, supplier selection, and M&A strategy.
- Integrated primary producers: Players with smelting and casting operations command advantages in feedstock control, alloy development and the ability to offer value‑added cast products. These firms are natural partners for OEMs seeking supply security and carbon transparency.
- Global precision die casters: Specialist die casters win on tolerances, automation and fast production ramp. Their investments in tooling and process controls make them critical suppliers for high‑value, high‑volume applications in transportation and industrial markets.
- Automotive‑oriented lightweight specialists: Suppliers focused on high‑pressure die casting and multimaterial assemblies are positioning for a wave of demand around electric vehicles and lightweight structural components.
- Regional foundries and diversified metal groups: These players often compete on cost flexibility and local proximity to customers, but face pressure from scaling and decarbonization investments required to stay competitive in regulated markets.
Our report examines the strategic moves and capability footprints of the sector’s leading firms, highlighting where capacity expansions, innovation awards, and sustainability programs are likely to alter competitive dynamics in 2026 and beyond. We also flag where recent capacity additions and awards signal an acceleration in recycling and alloy innovation trends.
What the PW Consulting Report Contains — Operationally Focused
This study is designed as a decision‑maker’s toolkit. Highlights include:
- Transparent market sizing and a 2026‑2032 forecast model with scenario toggles (baseline, policy shock, and demand‑acceleration scenarios).
- Plant archetype cost curves and a levelized cost sensitivity model for key casting processes to support capex prioritization.
- Supplier due‑diligence templates, alloy traceability checklists, and a procurement hedging playbook tailored to aluminum feedstocks.
- A carbon footprint mapping methodology and regulatory impact model (including sensitivity to cross‑border carbon pricing and trade remedies) to stress‑test contracts and pricing.
- M&A playbooks differentiating scale acquisitions, capability buys (e.g., recycling or precision tooling), and regional consolidation strategies — with actionable valuation drivers rather than generic multiples.
- Commercial strategies for OEM engagement, including tiering criteria, joint development structures, and offtake contracting templates.
To preserve the full strategic value for clients and subscribers, detailed regional, process and application splits, proprietary price and cost matrices, and company‑level financial overlays are included exclusively in the complete report.
Concrete Actions for 2026 Decision‑Makers
Translate insight into execution with a prioritized 90‑day plan:
- Immediate (0–90 days): Run feedstock exposure mapping across all plants; institute carbon tracking for major SKUs; initiate supplier dialogues about recycled content commitments.
- Near term (3–9 months): Reprioritize capex to favor recycling, low‑carbon pilot projects and automation; launch commercially binding pilot contracts with strategic OEM customers.
- Medium term (9–18 months): Execute targeted scale or capability acquisitions where due diligence validates payback under downside scenarios; deploy plant retrofits that unlock unit‑cost savings and compliance advantages.
Each action aligns with the tools and templates in our report to shorten execution timelines and reduce implementation risk.
Conclusion — Use Data to Shape Strategy, Not Just Forecasts
For executives making 2026 choices, the aluminum casting market presents predictable growth tempered by distributed risk. The right response is not to chase volume alone but to optimize for margin resiliency and regulatory alignment: secure feedstock, improve process economics, and accelerate circularity. The PW Consulting aluminum casting study is structured to move teams from insight to action — supplying the scenario models, operational templates and competitive diagnostics executives need to allocate capital and win in the coming cycle.
For access to the full dataset, granular segment and regional breakdowns, company‑level profiles and the interactive forecast model, please consult the complete PW Consulting Aluminum Casting Market report and datasets on our website. The rest of the story — including the exact process, application and regional splits that drive tactical decisions — is contained there.
For detailed analysis of this topic, please visit the official page: Aluminum Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


