



PW Consulting: FFC Market to Grow at 6.9% CAGR Through 2032

Flexible Flat Cable (FFC) Market: Strategic Perspectives for 2026 Decision‑Makers
Executive snapshot
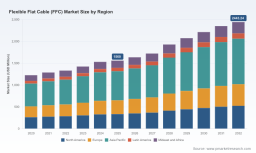
The Flexible Flat Cable (FFC) market has transitioned from a niche interconnect commodity to a strategically important component class for electronics systems architects, procurement leaders and M&A teams. Our analysis — using 2025 as the base year and a forecast window through 2032 — shows a clear, structural expansion driven by higher wire‑count density requirements, electrified vehicle architectures, and continued miniaturization in consumer and medical devices. The market grew steadily during the 2020–2025 historical window and is projected to expand at a compound annual growth rate (CAGR) of 6.9% from 2026 through 2032, reaching a materially larger addressable market by the end of the forecast horizon.
Flexible Flat Cable (FFC) Market
Why this research matters for 2026 decisions
In 2026, decisions around sourcing, product design, and strategic partnerships will determine which organizations capture the enlarged share of the FFC value chain. This study is designed to translate market momentum into repeatable, low-risk commercial actions: it links end‑market trends to supplier capabilities; calibrates sourcing cadence against tariff- and regulation-driven landed cost shifts; and frames M&A targets and partnership models with operational KPIs that procurement and strategy teams can use immediately. Rather than a high‑level narrative, the report delivers operational blueprints that support board-level capital allocation and tactical sourcing choices in the next 12–18 months.
Flexible Flat Cable (FFC) Market
Market trajectory: what the numbers tell us (high‑level)
From the start of the decade through 2025 the market expanded steadily. Between 2020 and 2025 the industry scaled from early‑decade baseline demand to a stronger, more diversified market position. Looking ahead, our base case at a 6.9% CAGR implies a multi‑year enlargement of the addressable market, reflecting both unit growth and modest ASP (average selling price) expansion as higher‑value, high‑speed and ruggedized FFC variants gain traction.
Flexible Flat Cable (FFC) Market
- Structural demand drivers include automotive electronics electrification and driver assistance systems, densification in consumer electronics, and incremental uptake in medical and industrial automation applications.
- Supply and cost dynamics will be shaped by raw material selections (polyimide versus polyester/PET), regulatory compliance considerations (RoHS/REACH, ISO standards) and tariff regimes that favor near‑sourcing for some OEMs.
- Competitive concentration is moderate: the three largest vendors collectively represent a meaningful slice of market capacity, with the top five controlling roughly half of market share — an environment that favors both scale advantages and specialist niches.
Competitive landscape: how incumbents and specialists position
Our vendor analysis evaluates capabilities across four vectors: product breadth and technology leadership; manufacturing footprint and scale; go‑to‑market model (catalog/volume vs custom/engineered); and end‑market focus (automotive, consumer, medical, industrial). Key archetypes emerge:
- Global system vendors with broad interconnect portfolios (e.g., TE Connectivity, Amphenol, Molex) — these players combine global manufacturing, channel reach and engineering services that make them first‑call partners for tier‑1 OEMs and large contract manufacturers. Their pull is in reliability, end‑to‑end supply agreements, and ability to support automotive qualification lifecycles.
- Precision and high‑speed specialists (e.g., Hirose, JAE, Sumitomo, Samtec) — typically focused on miniaturization, high frequency performance, and high‑density connector mating. They capture value where electrical performance or density constraints dominate purchasing decisions.
- Dynamic‑flex and harsh‑environment innovators (e.g., Johnson Electric, Parlex, Cicoil) — engineered for repeated flex cycles, service‑loop durability and ruggedized applications, these suppliers serve robotics, medical devices, and defense segments where lifecycle reliability is paramount.
- Custom and contract manufacturers (e.g., Parlex USA, Meritec, PICA, Miraco, Zhejiang Wenda) — offering design‑for‑manufacturing, rapid prototyping and scalable production, these firms are the execution partners for startups and OEMs seeking low MOQs and fast time‑to‑market.
- Hybrid suppliers and system vendors (e.g., 3M, Nicomatic) — positioned between standardized catalog offerings and value‑add custom assemblies, useful for programs that need both speed and compliance support.
Recent ecosystem activity, such as broad product catalog additions by electronic component distributors, signals improved availability of off‑the‑shelf FFC and FPC interconnects — increasing procurement agility for design teams that prefer shorter lead times and smaller-order flexibility.
Regulation, materials and supply dynamics
Material choices and compliance regimes are central to risk assessment and product roadmaps. Polyimide — widely used for higher‑temperature and outdoor exposure use cases — meets global RoHS and REACH standards and offers UV stability that supports certain outdoor or long‑life applications. Polyester (PET) remains an attractive, cost‑efficient insulation option where temperatures and mechanical requirements permit. Both material families satisfy core environmental regulations, but selection affects processing steps, supplier selection, and qualification timelines.
Trade policy is a practical force multiplier. Tariff shifts on flat and printed circuit connectors have raised landed costs for some OEMs and accelerated nearshoring or dual‑sourcing initiatives in 2025–2026. These dynamics alter total cost of ownership and should be incorporated into sourcing scorecards alongside lead‑time, quality and innovation metrics.
Operationally, prototyping and stocked FFC configurations can ship quickly — frequently within 1–2 weeks — and many suppliers support very low MOQs, enabling iterative design cycles. That agility reduces design risk but places a premium on standardized qualification procedures and supplier process controls as programs scale.
What the report contains: practical, executable intelligence
This study was written as a toolkit for 2026 planning cycles. Highlights include:
- Forecast model (2026–2032) with scenario toggles for ASP, tariff regimes, and regional demand shifts — delivered in a client‑editable format so teams can test internal assumptions alongside our base case CAGR of 6.9%.
- Supplier scorecards and battlecards for the leading vendors, assessing technology roadmaps, capacity constraints, qualification capabilities and strategic fit for different end‑market programs.
- Go‑to‑market playbooks for OEMs and contract manufacturers: sourcing scorecards, negotiation levers, sample RFQs, and qualification timelines mapped to automotive, medical and industrial lifecycles.
- Regulatory and materials playbook: compliance checklists, substitution risks, and recommended material selection frameworks tied to product lifespan and environmental exposure profiles.
- M&A and partnership framework: quantifiable criteria for bolt‑on acquisitions, JV structures for localized manufacturing, and a prioritized list of target profiles (specialists vs scale players) aligned to different strategic objectives.
- Cost and margin benchmarking, including key cost‑driver sensitivities and an approach to capture value via design consolidation, part reduction and supplier co‑development programs.
Actionable strategic recommendations for 2026
- Operationalize dual sourcing for medium‑ and long‑lead FFC technologies where tariff exposure or single‑source risk exists. Prioritize secondary suppliers that can rapidly prototype with MOQs in the single digits.
- Align new product introductions with high‑value FFC variants (high‑speed, ruggedized, and high‑temperature polyimide options). Where possible, design modular interconnect platforms to reduce SKU proliferation and shorten qualification windows.
- Embed regulatory compliance and materials selection early in the design cycle. Confirm RoHS/REACH documentation and ISO alignment before committing to long production runs; polyimide variants provide defensible differentiation for outdoor or long‑service programs.
- Use supplier scorecards to drive strategic partnerships rather than purely transactional sourcing. Suppliers that co‑invest in tooling, qualification and early test vehicles can materially shorten time‑to‑market and reduce total program risk.
- Pursue targeted M&A where access to specialized flex technology (dynamic‑flex, high‑density FFC, or ruggedized ribbons) accelerates product roadmaps — prioritize targets with defensible IP or strong customer anchors in high‑growth end markets.
Scenarios and risk management
We present three short, decision‑centric scenarios in the full report: conservative (slower economic demand, price compression), base (policy and demand trends as currently visible), and aggressive (step‑change adoption in automotive and 5G/edge computing). Each scenario ties directly to recommended sourcing, R&D and M&A responses so management teams can assign probabilities and trigger actions as early‑warning indicators emerge.
Conclusion and next steps
For executives planning 2026 capital allocation, product roadmaps or supply chain redesigns, the FFC market offers both growth and margin expansion if approached with a precision playbook. Our report turns high‑level forecasts into executable steps: supplier selection matrices, regulatory compliance checklists, and a practical M&A filter tuned to the realities of 2026 procurement and trade policy.
We intentionally present here the strategic narrative, core market trajectory and operational implications while preserving the detailed segmentation tables, vendor scorecards and interactive forecast model for the full report. To access the complete dataset, supplier rankings, and the client‑editable forecast model, please visit the report page or contact PW Consulting to request the full subscription package and bespoke advisory engagement.
For detailed analysis of this topic, please visit the official page: Flexible Flat Cable (FFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


