



PW Consulting: Greaseproof Paper Market Set for 5.25% CAGR Through 2032

Greaseproof Paper Market 2026: Strategic Preview for Decision Makers
As global packaging value chains confront tighter food-contact regulations, rising sustainability expectations and fluctuating raw-material costs, greaseproof paper is rapidly moving from a commodity niche to a strategic substrate. This preview synthesizes the macro trends, competitive dynamics and operational levers that PW Consulting’s full Greaseproof Paper Market report (base year 2025) uses to equip executives for high-stakes decisions in 2026. We highlight the headline market trajectory and the strategic questions every C-suite and corporate development team should be tackling—while reserving the segment-level numbers for the full report to protect the actionable intelligence that drives commercial advantage.
Greaseproof Paper Market
Headline Market Trajectory: A Market on a Purposeful Growth Path
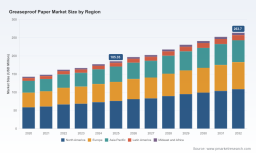
The greaseproof paper market has shown resilient expansion through the 2020–2025 historical window and is forecast across 2026–2032 to continue growing at a compound annual growth rate (CAGR) of roughly 5.25%. Measured in USD (Revenue Unit: Million), the market size in the base year (2025) provides a pragmatic anchor for scenario planning, and the 2032 projection frames medium-term capacity, investment and M&A decisions. For procurement, manufacturing and strategic planning teams, the combination of steady CAGR and upward nominal market scale implies predictable baseline demand but increasing differentiation driven by regulation and product innovation.
Greaseproof Paper Market
Why 2026 Is a Strategic Inflection Point
- RegulatoryTurning Point: The EU PFAS ban and similar regulatory pressure in other jurisdictions are shifting the value equation away from fluorochemistries and toward alternative barrier technologies. This alters technology roadmaps, supplier qualification, and labelling claims required for food-contact materials.
- Sustainability Demands: Certifications and ecolabelling schemes (notably Nordic criteria) increasingly mandate energy-efficiency and limits on fossil-oil dependence—making production footprint and supply-chain transparency decision factors for commercial win-rate and pricing power.
- Cost Environment: Coated and processed paper prices show volatility—industry indices such as the pulp and paper producer price index rose to levels that buyers and sellers must factor into contract terms and hedging approaches.
- Consolidation Levers: Market concentration metrics indicate meaningful scale benefits for top suppliers, shaping potential M&A strategies that can be realized in 2026 as buyers seek integrated capabilities (e.g., coating, barrier application, and logistics).
Market Structure and Segmentation (What We Cover, What We Withhold)
Our full report maps the market by region, by product type (e.g., kraft, sulfite, other specialty grades) and by application (food packaging, industrial wrapping, other uses). We model historical uptake and applied forward-looking scenarios to 2032. In this preview we avoid releasing the granular segment-level shares and precise regional figures; these are retained in the full analysis because they represent the primary commercial intelligence our clients use to prioritise channels, geographies and product investments.
Greaseproof Paper Market
At a conceptual level, segmentation drivers are clear: food-contact grades dominate where regulatory conformity and barrier performance are mandatory; industrial wrapping is more tolerant of recycled-content trade-offs; specialty grades compete on functional coatings and release properties. Raw-material pathways—virgin pulp versus recycled fibre combined with silicone or aqueous polymer coatings—remain the technical spine that determines cost, recyclability and regulatory compliance.
Key Dynamics Shaping Supply and Demand
- Regulation and Compliance: The EU PFAS ban is accelerating reformulation away from per- and polyfluoroalkyl substances in greaseproof applications. Manufacturers and converters investing in PFAS-free barrier systems or alternative release technologies will reduce regulatory risk and gain early-adopter advantages in major markets.
- Ecolabelling and Production Footprint: Nordic Ecolabelling criteria require energy-efficient production and restrict fossil-oil dependence—driving investment in process electrification, renewable energy sourcing and close-loop fibre solutions to maintain market access in northern European and premium segments.
- Raw-Material Price Pressure: The indexed price environment for coated and processed papers is elevated, affecting contract pricing and margins. Buyers should evaluate longer-term supply agreements with indexation mechanics, whereas producers must optimize furnish mixes and coating formulations to preserve margins.
- Recycling Quality Constraints: Standards such as the EN 643 limits for undesirable components in post-consumer fibre impose practical limits on recycled-content use for food-contact greaseproof grades, reinforcing the need for certified supply chains and secondary-fibre innovation.
Competitive Landscape: Who Matters—and Why
The market displays a concentrated upper tier where three to five players capture the majority of value and capabilities. That concentration translates into differentiated access to technology, scale manufacturing and certification credentials. Below we synthesize strategic positions of prominent suppliers, focusing on their capability sets rather than market shares (detailed competitor benchmarking is in the full report).
- Nordic Paper (Sweden) — Nordic Paper has positioned itself around natural, fluorochemical-free greaseproof grades and compost-certified ranges from virgin pulp. Their strategy signals a clear alignment with sustainability-driven procurement and ecolabelling requirements. For buyers targeting premium food-contact applications, Nordic’s portfolio reduces regulatory exposure and supports premium pricing.
- Metsä Tissue (Finland) — As a supplier with significant fresh-fibre capacity and an explicit focus on biodegradable, recyclable baking and cooking papers, Metsä’s integrated supply base supports both scale and traceability claims. Their sizable production footprint in Europe makes them a logical partner for customers needing consistent high-fibre quality and certification compliance.
- delfort group (Austria) — delfort’s specialty-paper capabilities—where greaseproof grades sit within a broader high-performance functional-paper portfolio—provide customization advantages. Their emphasis is on functional differentiation (e.g., release, wet-strength, printability) attractive to converters and branded-packaging customers.
- Mondi Group (Austria) — Mondi’s offering focuses on re/cycle functional barrier papers with tailor-made grease and mineral oil barrier technologies, extending into ultra-high barrier solutions. This technical scope positions Mondi as a partner for complex barrier applications where performance (e.g., OTR/WVTR metrics) matters as much as environmental credentials.
- Ahlstrom (Finland) — Ahlstrom’s FluoroFree® technologies and high-performance release-coated papers deliver a differentiated, low-regulatory-risk alternative to legacy fluorinated chemistries. This technology leadership is a strategic asset for converters and food manufacturers migrating to PFAS-free portfolios.
- KRPA PAPER (Czech Republic) — With a long heritage and export reach, KRPA’s catalogue addresses traditional greaseproof demand and niche markets requiring tailored grammages and functional treatments. Their regional manufacturing footprint supports agile supply to central and eastern European customers.
- Pudumjee Paper Products (India) — Pudumjee combines local scale with a focus on sustainable and FDA-compliant greaseproof grades. For multinational buyers regionalising supply chains in South Asia, Pudumjee offers a pragmatic mix of compliance and cost advantages.
Recent product introductions from companies such as Nordic Paper, Wipak and Lecta underscore the rapid pace of formulation and coating innovation. These launches are not isolated marketing activities; they reflect supplier responses to regulatory timelines and converter demand for recyclable, high-performance wraps.
Market Concentration and Strategic Consequences
Concentration ratios indicate that leading suppliers capture a substantial share of value—underscoring the importance of strategic supplier relationships and, for some players, the logic for horizontal consolidation or vertical integration. In practice, this means that:
- Large converters and retailers can expect fewer but more capable suppliers for high-performance, certified grades.
- Smaller producers must focus on niche differentiation—specialty coatings, regional service, or ultra-low-carbon footprints—to defend margins.
- Private equity and corporate strategists will find synergies in bolt-on acquisitions that add coating capability, barrier chemistries or certification credentials.
Strategic Playbook for 2026 Decision Makers
- Procurement: Re-negotiate contracts to include compliance warranties and indexation clauses tied to pulp & paper indices; qualify multiple PFAS-free suppliers to reduce single-source risk.
- R&D and Product: Prioritize investments in fluorine-free barrier technologies and scalable aqueous coating processes that meet recyclability and EN/food-contact limits.
- Operations: Map capital plans against forecast demand to avoid under- or over-capacity; target energy-efficiency upgrades to pre-empt ecolabelling barriers to market access.
- M&A: Evaluate bolt-on acquisitions that add coating technology, regional logistics or certified pulp feedstock to accelerate time-to-market for compliant grades.
- Commercial: Align go-to-market with sustainability claims backed by third-party certification and transparent supply-chain traceability to capture premium placements with food brands and retailers.
What the Full PW Consulting Report Provides
The complete study (base year 2025, historical 2020–2025, forecast 2026–2032) delivers:
- Granular segment models by region, type and application with scenario sensitivity and demand drivers.
- Supplier scorecards, capability maps and a detailed M&A-ready list of targets.
- Cost-curve analysis incorporating pulp indices, coating chemistry cost profiles and energy assumptions.
- Practical checklists for PFAS-transition implementation, ecolabelling compliance pathways and converter qualification templates.
We intentionally withhold the full segment-level tables and specific regional allocations in this preview to preserve the primary commercial intelligence that informs sourcing, pricing and strategic investment decisions. Access to the complete dataset, including downloadable models and supplier dossiers, is available through the PW Consulting portal and is the recommended next step for executives planning actions in 2026.
Closing: Positioning for 2026 and Beyond
The greaseproof paper market is maturing into a strategically important category at the nexus of regulation, sustainability and functional performance. While headline CAGR and market-size trajectory provide a growth baseline, the real value rests in navigating regulatory transitions, securing certified supply and selectively investing in technologies that enable PFAS-free, recyclable solutions. PW Consulting’s full report equips teams with the quantitative models and practical playbooks needed to move from reactive compliance to proactive market leadership—an imperative for any organization looking to make decisive moves in 2026.
For detailed analysis of this topic, please visit the official page: Greaseproof Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


