



PW Consulting: Bearing Ball Market Set to Grow at 5.1% CAGR

Bearing Ball Market 2026: Strategic Imperatives for Decision‑Makers — A PW Consulting Preview
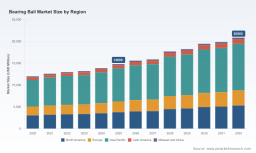
As companies prepare budgets, product roadmaps, and M&A pipelines for 2026, the bearing ball market presents a mixture of enduring industrial steady‑state and accelerating pockets of technical disruption. Our latest market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, shows a market that expanded from roughly USD 12,000 Million in 2020 to an estimated USD 14,800 Million in 2025 and is projected to reach approximately USD 20,860 Million by 2032, driven by a steady compound annual growth rate of 5.1% across the forecast period. This briefing pulls forward the strategic implications senior executives and investors must factor into 2026 planning — illustrating the depth of analysis in the full report while intentionally withholding detailed segmentation to direct practitioners to the underlying data models and dashboards.
Bearing Ball Market
Macro takeaways that should guide 2026 decisions
-
Growth is predictable but uneven: The market’s mid‑single‑digit CAGR masks substantial variation by technology, application and end‑market. For corporate planning, this means treating the bearing ball market as a stable backbone for industrial revenue while selectively prioritizing high‑momentum subsegments for capital and R&D allocation.
Bearing Ball Market -
Technology premiumization continues: Miniaturization for medical and semiconductors, high‑speed precision bearings for servo motors, and hybrid material solutions are recurring themes. These are the vectors where margin expansion and differentiation are most attainable.
Bearing Ball Market -
Supply chain and input risk are strategic constraints: Volatility in chrome steel and alloying metals directly affects cost structures and delivery reliability. Recent standards updates for bearing steels have tightened material specifications, creating both compliance obligations and opportunities for suppliers that move early to qualify advanced grades.
-
Consolidation pressure with room for nimble competitors: Market concentration metrics indicate a meaningful presence of large incumbents alongside numerous specialty players. The sector rewards scale in global OEM channels, but focused technology plays can win niche verticals with premium pricing.
What this means for specific strategic functions in 2026
-
Board & Portfolio Strategy — Prioritize a two‑track approach: protect core industrial and automotive franchises while allocating targeted capital to high‑growth technical subsegments (miniature, hybrid ceramics, ultra‑precision). Use the market’s predictable mid‑term revenue growth to underwrite selective risk.
-
Supply Chain & Procurement — Reassess material sourcing protocols: dual‑sourcing, longer hedging horizons, and strategic alliances with steelmakers will reduce margin volatility. Require material provenance and advanced steel grades validation in supplier contracts to meet evolving ISO requirements.
-
R&D & Product Strategy — Fast‑track miniaturization, noise reduction, and corrosion‑resistant solutions for medical and robotics. Invest in design for manufacturability to lower total cost and shorten time‑to‑market for next‑generation precision bearings.
-
Commercial & Go‑to‑Market — Differentiate through systems expertise (bearing + actuator, bearing + lubrication system, lifecycle services). OEM partnerships and co‑engineering arrangements are increasingly decisive for securing design wins.
-
Corporate Development — M&A should target either capability gaps (e.g., ceramic/hybrid materials, mobile robotics bearings) or geographic manufacturing scale. Financial underwriting must embed raw‑material scenario stress tests and integration plans that accelerate product cross‑sell.
Competitive landscape — strategic signals from leading players
The competitive set is a mix of global incumbents and specialized innovators. Incumbents leverage scale, distribution reach, and deep application engineering; smaller players concentrate on material innovation and niche applications. The full report profiles leading suppliers across capability matrices — from high‑volume deep‑groove products to ultra‑precision and hybrid solutions — and provides an actionable assessment of channel strength, technology roadmaps, and likely future moves.
-
Global leaders remain focused on platform plays and system integration. Several have announced partnerships and product launches that signal a shift from component selling toward co‑engineered solutions for surgical robotics, servo motors and high‑precision tools.
-
Specialists are exploiting material and manufacturing advantages. Recent launches of ultra‑low‑noise miniature bearings, high‑speed servo bearings, and corrosion‑resistant miniaturized solutions show that differentiated IP and manufacturing know‑how can command premium placement in targeted verticals.
-
Recent market moves to monitor: precision product introductions at major industry shows, strategic partnerships with robotics developers, and product lines emphasizing sterilization durability and ultra‑low noise. These reveal where R&D focus is translating into near‑term commercial opportunities.
Regulatory and raw material dynamics — operational playbook
Two technical dynamics require immediate board‑level attention. First, raw‑material volatility — particularly in chrome steel and minority alloy elements — is now a persistent margin risk. Companies should embed commodity sensitivity into pricing and procurement models and pre‑qualify alternative steel grades where feasible.
Second, tightening technical delivery requirements (notably the latest editions of bearing steel standards) raise qualification overheads for any product updates. Early compliance programs and collaboration with steel suppliers on new grades (for example, improved through‑hardening and oxygen control) will reduce time‑to‑market for higher‑value bearings.
What’s in the full PW Consulting report (practical, usable content)
-
Proprietary market model: an interactive forecast model covering 2020–2032 with scenario toggles for commodity shocks, electric/automation adoption curves, and medical device penetration.
-
Supplier intelligence: detailed profiles and capability maps for major manufacturers and fast‑growing specialists, including technology roadmaps, manufacturing footprints, and partnership playbooks.
-
Commercial playbooks: channel strategies for OEM penetration, pricing mechanisms to protect margins under commodity stress, and service models to extend lifecycle revenue.
-
Procurement playbook: material risk matrices, dual‑sourcing templates, and qualification checklists aligned with recent bearing steel standards.
-
Deal pipeline & valuation analytics: a short list of acquisition targets by capability, with valuation guidance and integration risk assessments keyed to 2026 synergies and 3–5 year payback horizons.
-
Technology deep dives: comparative analysis of ceramic/hybrid solutions, miniaturized bearings for medical wearables, and high‑speed designs for servo applications — including manufacturability and cost curves.
90/180/360‑day action roadmap for executives
-
0–90 days: Commission a material risk audit; enforce revised supplier qualification clauses for advanced bearing steels; begin prioritized product performance testing for high‑growth subsegments.
-
90–180 days: Launch at least one co‑engineering pilot with an OEM in either medical robotics or servo motors; finalize procurement hedging strategy and secure strategic supply agreements for critical alloys.
-
180–360 days: Execute targeted M&A or joint‑venture plays to acquire missing capabilities (e.g., hybrid ceramic expertise, ultra‑precision miniaturization) and roll out commercial pilots that translate new products into multi‑year contracts.
Final note — why this preview and why now
This preview demonstrates the pragmatic intelligence and scenario planning embedded in PW Consulting’s full Bearing Ball Market study: robust top‑line growth, clear technical vectors for differentiation, and pressing supply‑side governance requirements. We intentionally omit detailed regional, type, and application split figures here to preserve the value of our proprietary segmentation and to invite decision‑makers to review the full models and data tables, which are the basis for executable 2026 strategies.
For executives planning capital allocation, procurement policy, or M&A activity in 2026, the full report provides the empirical foundation and tactical templates to convert market trends into defensible actions. Contact PW Consulting to obtain the full dataset, interactive forecast model, and a tailored briefing that maps these insights directly to your portfolio.
For detailed analysis of this topic, please visit the official page: Bearing Ball Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


