



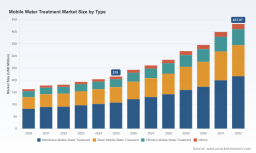
PW Consulting: Mobile Water Treatment Market to Hit USD 431.97M by 2032 at 10.5% CAGR

Mobile Water Treatment Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
By 2026 the global mobile water treatment market steps into a new strategic phase — one defined by accelerating demand, tighter regulatory guardrails, and an intensified race to deliver rapid, compliant, and cost‑efficient field solutions. Our PW Consulting study shows the market expanding from a 2025 base to materially larger levels through the 2026–2032 forecast window, underpinned by a compound annual growth rate (CAGR) of 10.5%. This upward trajectory reflects persistent needs across emergency response, municipal surge capacity, industrial pretreatment, and off‑grid desalination/fit‑for‑purpose supply.
Mobile Water Treatment Market
Why this brief matters for 2026 planning
Senior leaders preparing budgets, M&A pipelines, product roadmaps, or regional go‑to‑market strategies must reconcile short horizon operational realities with medium‑term structural shifts. Our research translates market momentum and regulatory inflection points into prescriptive options: where to invest in R&D, which partner archetypes to target, and how to staff and price mobile service offerings to preserve margin in a tight supply environment. The analysis is intentionally practical — designed to be applied in quarterly planning cycles while also informing three‑year capital and capability decisions.
Mobile Water Treatment Market
Market dynamics shaping strategic choices
-
Regulatory acceleration: The U.S. EPA’s 2024 National Primary Drinking Water Regulation — establishing enforceable Maximum Contaminant Levels for six PFAS compounds — and subsequent implementation activity have moved PFAS mitigation from foresight to procurement driver for mobile systems used by water utilities and emergency response teams. New federal proposals announced in mid‑May 2026 further refine implementation mechanics, increasing demand for adaptable mobile treatment units that can be rapidly deployed to meet evolving compliance requirements.
Mobile Water Treatment Market -
Cost and supply pressure: Raw material and chemical cost volatility — with bulk treatment chemicals experiencing significant price swings over recent years — combined with higher labor and logistics costs, compresses margins and shifts buyer preferences toward systems that reduce OPEX through higher recovery, lower chemical consumption, or simplified service models.
-
Technological convergence: Advances in membrane systems, mobile electrodialysis, modular containerization, and trailerized configurations are enabling higher throughput and faster time‑to‑service. Proprietary enhancements in pre‑treatment and automation are becoming differentiators in competitive bids where uptime and lifecycle cost matter more than headline capital expenditure.
-
Market structure: Concentration metrics indicate a market where a handful of global providers hold meaningful share (CR3 and CR5 levels reflect a moderately concentrated competitive environment). This creates both barriers and opportunities: large incumbents bring deployment scale and service networks; specialised suppliers unlock niche technical advantages and flexible commercial models.
Competitive landscape — who matters and why
Our competitive mapping focuses on companies that matter in the short and medium term for enterprise buyers and strategic investors. Each firm brings a distinct mix of technical capability, channel presence, and commercial model:
-
Veolia Water Technologies (Paris) — Deep expertise in emergency and municipal mobile services, now expanding footprint in Latin America with new service centers. Veolia’s advantage is integrated service capability: equipment + rapid logistics + remediation knowledge, making it a go‑to for large municipal projects and disaster response contracts.
-
Xylem Inc. (Washington, DC) — Strength in engineered, trailer‑based solutions and rapid‑deployment units. Xylem’s R&D and channel networks position it well for public sector and utility partnerships where reliability and interoperability with existing assets are procurement priorities.
-
SUEZ Water Technologies & Solutions (Paris) — Containerized, industrial‑grade equipment and broad industrial client relationships. SUEZ competes on turnkey projects and large temporary augmentations of plant capacity.
-
Pentair plc (St. Paul) — Focus on membrane filtration and modular mobile options that emphasize rapid setup and standardized maintenance protocols. Pentair appeals to operators seeking lower lifecycle complexity.
-
Aquatech International (Canonsburg) — Notable for innovation in desalination and treatment; recent product introductions in electrodialysis reversal (EDR) target high‑recovery mobile desal and reuse segments, offering an alternative to traditional RO‑centric approaches.
-
Aria Filtra (Canada), NEWater (China), Ampac USA, Pure Aqua Inc., Craftsmen Industries — A set of specialist and regionally focused suppliers that excel at containerized FAST solutions, plug‑and‑play systems, and bespoke field units. These vendors are often agile partners in pilot deployments or localized service rollouts.
Recent industry moves worth noting
-
Veolia’s new Mobile Water Service Center opened in São Paulo (April 2025) — a clear signal of incumbent investment in regional service capabilities to shorten deployment lead times and reduce logistics costs for municipal and industrial customers.
-
Aquatech’s launch of the EDR‑Q™ system (May 2025) — highlights a technology pivot toward higher‑recovery, lower‑energy mobile desalination and reuse applications which will influence OPEX considerations across cost models.
What PW Consulting’s report delivers — practical contents
This study is structured to convert market intelligence into executable choices. Key deliverables include:
- Scenario‑based demand forecasts covering near‑term surge, regulatory compliance, and industrial capex cycles (2026–2032).
- Provider scorecards and comparative matrices that evaluate technology fit, deployment speed, compliance readiness, and lifecycle cost across vendor archetypes.
- Regulatory impact assessments that translate recent and proposed PFAS rules, EU water policy shifts, and emerging discharge standards into equipment specifications and service prerequisites.
- Commercial playbooks — procurement checklists, RFP templates, and SLA benchmarks — to accelerate vendor selection and contract negotiation.
- CapEx/Opex modeling templates with sensitivity analyses for recovery rates, chemical consumption, labor inputs, and transport logistics.
- Use cases and field‑level lessons from municipal, emergency response, and industrial pilots with prescriptive recommendations on deployment sequencing and training.
- M&A and partnership screening tools to identify target profiles based on tech differentiation, service coverage, and integration complexity.
How to convert insight into 2026 actions — a pragmatic playbook
-
Prioritise compliance‑ready modularity: Invest in modular systems that can be reconfigured for PFAS treatment, high‑recovery desalination, or rapid potable supply. Cross‑walking regulatory scenarios to equipment spec sheets reduces retrofit costs and shortens time‑to‑revenue.
-
Design procurement for volatility: Structure contracts with indexed chemical and logistics clauses and include performance‑based components tied to recovery and uptime. This shields margins from raw material and labor cost swings.
-
Pursue selective partnerships: For incumbents, pursue alliances with specialist tech players to add high‑recovery desalination or niche pretreatment capabilities without full internal R&D cycles. For smaller suppliers, look to regional service partners to scale deployment footprints efficiently.
-
Operationalize deployment readiness: Create regional staging centers or partner networks to reduce lead times and transportation costs — a strategy already being adopted by system leaders to win municipal and emergency contracts.
-
Embed lifecycle economics into sales motions: Shift customer conversations from CAPEX to total cost of ownership, using standardized templates that quantify savings from reduced chemical use, lower energy consumption, and higher recovery.
Risk calibration and near‑term monitoring
Executives should monitor three risk vectors closely:
- Regulatory revisions and enforcement timetables for PFAS and other priority contaminants — changes can rapidly shift demand composition.
- Supply chain disruptions or rapid input cost inflation in treatment chemicals and membrane materials that will affect both pricing and service economics.
- Competitive moves by global incumbents to vertically integrate deployment, which can compress margins for specialist vendors but also opens partnership windows for complementary technologies.
How clients use this research
Clients have employed our report to:
- Shape 2026 capex allocations and justify accelerated investment in mobile treatment fleets.
- Underpin M&A diligence and carve‑out valuations in vendor and service segments.
- Define product roadmaps that align new features with likely regulatory and customer procurement timelines.
- Recraft commercial models to capture recurring service revenue from mobile deployment, maintenance, and consumables.
Conclusion — the strategic imperative for 2026
The mobile water treatment market in 2026 is not simply larger; it is structurally different. Regulatory mandates, technological innovations, and delivery economics are converging to privilege suppliers and buyers who can move fast, demonstrate compliance, and quantify total cost of ownership. Our analysis — grounded in a robust forecast and comparative competitive mapping — equips executives to make targeted investments, structure defensible commercial models, and choose partners that reduce deployment risk.
PW Consulting’s full report contains the detailed numeric breakdowns, vendor scorecards, scenario models, and procurement tools that translate the strategic direction outlined here into executable programs. Contact PW Consulting or visit our report landing page to access the full dataset and actionable annexes required for 2026 implementation.
For detailed analysis of this topic, please visit the official page: Mobile Water Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


