



PW Consulting: Hematology Analyzer Market to Reach USD 6.5B by 2032 at 5.97% CAGR

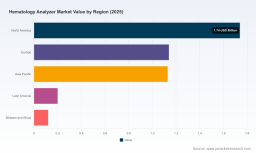
Hematology Analyzer Market — Strategic Briefing for 2026 Decision-Making
Executive summary
As healthcare providers and laboratory service operators enter 2026, the hematology analyzer market is entering a period of structurally steady expansion driven by diagnostic modernization, rising throughput needs, and selective automation adoption. PW Consulting’s latest Hematology Analyzer Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative market trajectories with tactical playbooks for procurement, product positioning, and capital planning. The global market, measured in USD billions, has grown from the low single‑digit billions in 2020 to a materially larger base in 2025 and is forecast to continue expanding through 2032 at a Compound Annual Growth Rate (CAGR) of 5.97% — a profile that favors disciplined investment in differentiated hardware, software-enabled services, and consumables ecosystems.
Hematology Analyzer Market
Why this study matters for 2026 corporate strategy
-
Timing: 2026 is a transition year where near-term reimbursement and regulatory milestones converge with next‑generation product deployments. Decisions made now will lock in multi‑year cost structures, service footprints, and vendor relationships.
Hematology Analyzer Market -
Capital allocation: Buyers face tradeoffs between high-throughput instrumentation and distributed point‑of‑care solutions. Our study translates market growth signals into capital prioritization frameworks that align total cost of ownership (TCO) considerations with throughput, accuracy, and workflow integration requirements.
Hematology Analyzer Market -
Competitive advantage: Vendors and distributors seeking growth must choose between feature-led differentiation (AI-assisted flagging, cloud analytics), operational excellence (service reliability, reagent logistics), and channel expansion. The report maps where each approach delivers the strongest ROI by clinical setting and lab scale.
-
Risk management: Supply‑chain exposures and component cost pressures are reshaping manufacturing economics. The study provides scenarios that quantify margin sensitivity to raw‑material cost swings and critical component availability, enabling stress‑tested procurement strategies.
Market outlook — what the macro numbers tell us
Between 2020 and 2025 the total hematology analyzer market expanded materially, reflecting sustained demand for routine CBC testing, rising automation in clinical labs, and selective replacement cycles. With a base year of 2025, our forecast to 2032 assumes a mid‑single digit CAGR of 5.97%, which translates into steady incremental revenue pools for vendors that can combine hardware sales with consumables and service contracts. The growth trajectory favors vendors that can scale both installed base and recurring revenue streams, while also offering interoperable software that reduces laboratory labor and error rates.
Importantly, market concentration remains meaningful: the top three firms control a substantial share of revenue, and the top five extend that dominance further. This concentration creates both barriers and opportunities — established players can leverage scale to deepen service networks, while challengers that prove clinical performance or dramatically lower TCO can carve niches rapidly.
Key dynamics shaping 2026 choices
-
Regulatory momentum: 2024–2025 product clearances for several flagship analyzers have accelerated adoption in regulated markets. Recent FDA 510(k) clearances for new automated platforms underscore the regulatory pathway’s centrality to commercial expansion in North America and influence purchasing cycles for high-volume labs.
-
Reimbursement and testing economics: Hematology testing typically sits within broader diagnostic reimbursement bundles rather than being reimbursed as an isolated technology. Procurement decisions therefore hinge on operational savings and downstream throughput gains rather than on incremental test fee captures alone.
-
Capital vs. outsourcing calculus: Facilities evaluating on‑premises investment versus outsourcing are prioritizing demonstrable first‑year and run‑rate cost impacts. High‑throughput systems today deliver compelling economics for medium to large hospital labs, particularly when reagent and service economics are included in vendor agreements.
-
Supply‑chain and component exposure: Optical and electrical sensing subsystems constitute a dominant share of manufacturing operating expenses. This concentration creates vulnerability to component price shifts and supplier consolidation — factors that operators and OEMs must incorporate into multi‑year sourcing and pricing models.
-
Technology convergence: AI‑assisted flagging, cloud analytics, and LIS connectivity are no longer optional features for buyers aspirational about workflow optimization. These capabilities are becoming competitive table stakes in mid‑ and high‑volume segments and are accelerating differentiation among vendors.
Competitive landscape — strategic implications from vendor activity
The competitive map in 2026 is defined by a mix of established instrument OEMs and focused regional players. Vendor strategies cluster around three archetypes: scale incumbents leveraging installed-based services; feature-driven innovators pushing AI and cloud integrations; and cost-conscious challengers offering compact, low‑maintenance systems for decentralized settings.
-
Sysmex Corporation (Kobe, Japan) — Sysmex continues to push the envelope in automated, high-throughput systems with AI-assisted flagging and deep LIS integration. Recent regulatory success and expanded throughput capabilities reinforce their leadership posture in clinical laboratories that prize accuracy and workflow automation. Strategic consideration for buyers: Sysmex’s strength is system-level integration and analytics — ideal where laboratories prioritize consolidated instrument fleets and centralized data management.
-
Beckman Coulter (Indianapolis, USA) — Beckman’s portfolio emphasizes robust sample integrity features and real‑time monitoring for mid‑to‑high-volume workflows. Their recent regional product introductions position them to capture growth in markets upgrading legacy fleets. Strategic consideration: Beckman is a logical partner where operational continuity and high-volume throughput are mission-critical.
-
HORIBA Medical (Montpellier, France) — HORIBA’s next‑generation high‑throughput analyzers combine advanced QC management with reagent stewardship. Their product roadmap signals a focus on sustainable reagent systems and laboratory QC efficiency. Strategic consideration: HORIBA appeals to networks seeking high throughput with a focus on QC robustness and reagent lifecycle management.
-
Siemens Healthineers (Munich, Germany) — Siemens is integrating AI-driven workflow optimization and cloud analytics into hematology platforms, targeting laboratories that view analytics as a lever for operational transformation. Strategic consideration: Choose Siemens when analytics-driven decision support and enterprise-level integration are prioritized.
-
Diatron (Budapest, Hungary) — Diatron’s compact, low‑maintenance units target decentralized and resource-constrained labs. Their product updates enhance reagent compatibility and bench-top performance, reinforcing appeal in markets where space and operator skill are constraints. Strategic consideration: Diatron is attractive where cost efficiency and simplicity outweigh the need for ultra-high throughput.
Notable recent developments — product launches, regulatory clearances, and catalog updates in 2024–2025 — should be read as more than product-level noise. They represent shifts in procurement timetables, regional competitive intensity, and the vendor feature sets buyers now expect. For procurement teams, these events affect negotiating leverage and replacement timelines; for OEMs, they reshape go‑to‑market priorities.
What the PW Consulting report contains — practical outputs
The report is designed as a decision support toolkit, not an academic compendium. It includes:
-
Market sizing and forward demand models (2020–2032) at the macro level with scenario sensitivity to adoption rates, unit pricing, and consumables penetration.
-
A vendor scorecard that benchmarks installed base maturity, software capability, service footprint, and consumables margins — enabling head-to-head comparisons that inform RFP design.
-
Procurement playbooks that translate TCO modeling into procurement levers (capital lease vs. purchase, reagent bundling, multi-year service agreements).
-
Regulatory and reimbursement mapping that identifies near‑term clearance timelines and how reimbursement frameworks influence purchase viability in major markets.
-
Operational case studies and lab-level workflow impact assessments that quantify staffing, throughput and error‑rate improvements for representative use cases.
-
Supply‑chain risk dashboards highlighting component concentration and mitigation strategies for OEMs and contract manufacturers.
How to use the study in 2026 planning
-
For buyers: use the vendor scorecards and TCO scenarios to structure multi‑bid procurements that prioritize lifecycle cost, uptime SLAs, and interoperability with LIS/EMR ecosystems.
-
For OEMs: prioritize investments in AI-assisted diagnostics, cloud analytics, and reagent lifecycle management to capture higher-value recurring revenue pockets.
-
For investors and M&A teams: concentrate diligence on installed base economics, consumables attachment rates, and geographic service scalability — those metrics determine valuation premia beyond headline device sales.
-
For policy teams: understand how regulatory clearances and testing reimbursement arrangements alter market access; anticipate procurement cycles in public health systems and large hospital networks.
Closing perspective and next steps
The hematology analyzer market in 2026 is neither a boom nor a bust — it is a pragmatic growth market characterized by consolidation, feature convergence, and service-driven margin capture. The macro trajectory and concentration metrics favor organizations that combine reliable hardware with smart software and dependable service networks. PW Consulting’s study converts these macro realities into actionable decisions: which platforms to trial, how to shape procurement terms, and where to invest in product innovation.
To access the detailed segmentation datasets, vendor revenue models, and the full suite of decision tools referenced in this briefing, please consult the full Hematology Analyzer Market report and its interactive dashboards on our website. The briefing above intentionally omits granular split‑level datasets to preserve the report’s unique analytical value and to direct decision‑makers to the validated source material that supports 2026 planning.
For detailed analysis of this topic, please visit the official page: Hematology Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


