



PW Consulting: FRC Market to Reach USD 2,915 Million by 2032 at 7.15% CAGR

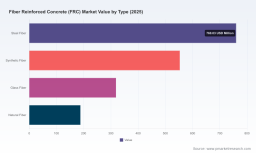
Fiber Reinforced Concrete (FRC) Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As lead industry analysts at PW Consulting, we present a concise, decision‑centric perspective on the Fiber Reinforced Concrete (FRC) market to inform capital allocation, product strategy, and commercial planning in 2026. The sector has moved from a niche engineering solution to an increasingly mainstream specification across infrastructure and industrial applications. At the macro level, the market expanded from approximately USD 1,350.25 Million in 2020 to USD 1,820.0 Million in 2025 (base year). Under our forecast horizon (2026–2032), the market is projected to continue growing at a compound annual growth rate (CAGR) of about 7.15%, reaching roughly USD 2,915.0 Million by 2032. The 2026 opening year estimate is ~USD 1,903.23 Million.
Fiber Reinforced Concrete (FRC) Market
Why this research matters for 2026 corporate decisions
-
Portfolio prioritization: When a market grows mid-single digits consistently, product and channel investments must be timed to capture structural adoption rather than transient demand spikes.
Fiber Reinforced Concrete (FRC) Market -
Specification and standards-driven wins: Emerging test methods and code updates make timely standards engagement a commercial advantage for suppliers and specifiers.
Fiber Reinforced Concrete (FRC) Market -
M&A and consolidation logic: The market’s current concentration metrics indicate meaningful regional champions alongside a long tail of specialists — an environment ripe for targeted consolidation to accelerate scale and distribution.
-
Supply‑chain and raw‑material strategy: Volatility in steel and polymer inputs, plus sustainability requirements, change total cost‑of‑ownership calculus for both producers and end users.
-
Risk management for tenders and specifications: Owners and contractors must integrate FRC performance data into contract language to avoid rework and downstream liability.
What this report delivers (operational contents)
We designed the study to be actionable for executives, product managers, and commercial teams. The report combines quantitative market models with implementable toolkits, including:
-
Transparent market‑sizing and scenario models (historical 2020–2025, base year 2025, forecasts 2026–2032) with sensitivity levers for price, adoption rate and raw material shocks.
-
Demand‑driver analysis across infrastructure, building, and industrial use cases — with adoption pathways, tender dynamics and buyer personas.
-
Technology and product deep dives covering steel, synthetic, glass and natural fiber architectures, plus hybrid and blended solutions; innovation roadmaps and cost‑to‑benefit frameworks.
-
Competitive benchmarking and supplier landscaping with capability matrices, service differentiation, and go‑to‑market playbooks.
-
Regulatory & standards tracker (ACI, ASTM, FIP and industry association developments) and the commercial impacts of proposed test methods.
-
Commercial implementation tools — specification templates, lab trial protocols, prequalification checklists, and an RFP playbook for FRC‑inclusive projects.
-
Investment and M&A pack — valuation comparables, consolidation scenarios and integration checklists for bolt‑on and transformative transactions.
Note: in keeping with this briefing’s “trailer” approach, we intentionally avoid publishing segment‑level revenue splits and regional/applicational micro‑breakouts here. Those detailed cells and the underlying data tables are available in the full report.
Market dynamics and high‑level implications
The last half‑decade shows sustained adoption: overall market value grew materially between 2020 and 2025, driven by a combination of higher specification rates in infrastructure projects, expanded use in industrial flooring and growing acceptance in mainstream building workflows. The forecasted 7.15% CAGR through 2032 reflects both steady demand in retrofit and new build sectors and incremental share gains where FRC offers lifecycle, labour and performance advantages versus traditional reinforcement.
Several dynamics deserve special strategic attention:
-
Standards and test methods are converging on performance‑based specification. Proposed procedures, like the new tensile evaluation methods under consideration, will raise the bar for product validation and offer first‑mover advantages to manufacturers who invest early in accredited testing.
-
Material substitution is not uniform: labor shortages, formwork savings and the economics of precast manufacturing tip some applications toward fiber solutions faster than others. Companies must map their sales funnel to these differential adoption rates rather than assuming homogeneous uptake.
-
Sustainability and whole‑life cost assessments are increasingly decisive. Life cycle and CO2 metrics are increasingly used in public tenders and green procurement, favoring suppliers who can document reduced embodied carbon or introduce recycled/resin‑efficient products.
-
Market structure remains moderately fragmented. Market concentration metrics show a small set of global leaders with a sizeable long tail of regional specialists—creating opportunities for scale players to buy distribution and for niche innovators to partner with larger platforms.
Competitive landscape — who matters and why
The competitive field comprises global multinationals, regional manufacturers, and highly specialized fiber innovators. Key active players include (representative, not exhaustive):
-
Sika AG — global breadth, branded fiber systems and strong integration with admixtures and concrete additives; positioning is one of system sale and specification influence.
-
Bekaert NV — deep heritage in steel fibers and increasingly in blended structural solutions; recent product introductions emphasize durability and sustainability for heavy civil uses.
-
The Euclid Chemical Company — U.S.‑focused supplier with strong ties to contractors and a portfolio of synthetic fibers aimed at construction practice and flooring.
-
FORTA Corporation — specialty fiber maker with a clear focus on high‑performance systems for concrete reinforcement and an established commercial presence.
-
W.R. Grace and other specialty additives producers — leveraging chemical and fiber synergies to deliver performance‑engineered mixes for demanding applications.
-
Regional and niche suppliers (Nycon, BarChip, ABC Polymer, Monahan FiberWorx and others) — differentiated by product engineering, cost competitiveness, or local channel advantages.
Recent industry developments underline the speed at which standards and product launches can re‑shape procurement. Examples include a 2026 product rollout by a major steel fiber producer targeting tunnelling segments, and industry association presentations that continue to spread ACI/industry design tools. ASTM’s proposed test method for tensile performance (developed in late 2025) is an immediate commercial inflection — suppliers with validated test data will be shortlisted for specification‑led projects.
Strategic imperatives and recommended actions for 2026
-
Prioritize standards alignment and test data. Fund accredited lab validation now to be on prequalification lists for public and large private tenders.
-
Adopt a two‑track product strategy: defend high‑value engineered systems while piloting lower‑cost blended solutions for price‑sensitive, high‑volume applications.
-
Secure raw‑material optionality. Hedge polymer and steel exposures through multi‑sourcing, offtake agreements and recycled feedstock programs to protect margins.
-
Leverage partnerships with concrete producers, EPCs and precasters. Embed fibers in system bundles to capture specification inertia and reduce buyer switching costs.
-
Use targeted M&A to accelerate access to distribution or specialized IP; prioritize acquisitions that add testing capabilities, regional approvals or life‑cycle assessment data.
-
Commercialize lifecycle value narratives. Equip sales teams with TCO calculators that convert performance benefits into reduced maintenance and whole‑life cost for owners.
How to apply this briefing
Use the data and frameworks in this research to stress‑test your 2026 budget, product roadmap and M&A pipeline. The full PW Consulting deliverable provides the granular segmentation, regional and application-specific models, vendor scorecards, and executable playbooks you need to operationalize the strategies above. If your organization is preparing tenders, assessing acquisition targets, or defining 3‑year product investment plans, the proprietary tables and scenario workstreams in the full report will materially reduce execution risk and accelerate time to specification.
For access to the complete dataset, segment‑level forecasts, and the implementation toolkits referenced above, consult the full PW Consulting FRC Market report. Our team can also deliver a tailored executive workshop to convert insights into a 90‑day commercialization plan.
For detailed analysis of this topic, please visit the official page: Fiber Reinforced Concrete (FRC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


