



PW Consulting: Microfiber Cleaning Cloths Market to Reach USD 1,117.43 Million by 2032 (4.5% CAGR)

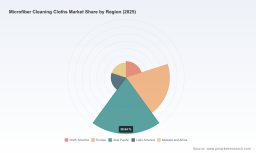
Microfiber Cleaning Cloths Market 2026: Strategic Preview for Enterprise Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry briefing designed to orient executive decisions for 2026. This article distills the strategic implications from our full Microfiber Cleaning Cloths Market study — situating market momentum, competitive posture, regulatory drivers, and operational levers that will matter most to manufacturers, distributors, retailers, and investors over the next planning horizon.
Microfiber Cleaning Cloths Market
Why this study matters for 2026
-
Timing: The market is moving from recovery into structural growth. With a compound annual growth rate projected at 4.5% across our forecast window (2026–2032), the microfiber cloths category is re-establishing demand patterns and opening margins for innovation-led players.
Microfiber Cleaning Cloths Market -
Decision focus: Companies that act in 2026 will define channel footprints, supply resilience, and sustainability positioning for the coming cycle. Our study turns market-level trends into executable choices — which SKUs to prioritize, which channels to expand, where to invest in production technology, and when to pursue M&A.
Microfiber Cleaning Cloths Market -
Risk/reward calibration: The market shows moderate concentration — the top three players control a meaningful share and the top five expand that edge — creating both scale advantages and white-space opportunities for focused challengers. Understanding this competitive geometry is critical to both defensive and offensive strategies.
Market snapshot (what the macro picture tells us)
-
Base year and trajectory: Using 2025 as the analytical base, the global microfiber cleaning cloths market has rebounded from pandemic-related volatility and is forecast to expand steadily through 2032. The study models demand drivers and elasticity across household, commercial, industrial and precision-cleaning use cases.
-
Growth profile: A steady mid-single-digit CAGR through our forecast reflects a balance of tailwinds — regulatory shifts toward reusables, improved manufacturing economics, and consumer preferences for chemical-free cleaning — against headwinds such as raw material cycles and channel commoditization.
-
Concentration and competitive dynamics: Market concentration metrics indicate an industry where established brands retain scale advantages, but fragmentation at the lower-price tiers keeps distribution and private-label opportunities fluid. This combination incentivizes differentiated product performance, sustainability claims, and channel-specific playbooks.
Key demand drivers and regulatory context
-
Regulatory redirection: Policies to curtail single-use plastic waste — including directives in Europe and parallel measures at national/state levels in other advanced markets — are accelerating substitution toward high-performance reusable textiles. This regulatory momentum is not binary; it changes procurement specifications in commercial cleaning, hospitality and institutional purchasing.
-
Consumer behavior: A durable swing toward reusable, chemical-free cleaning solutions has elevated premium microfiber positioning. Buyers increasingly value demonstrable lifecycle benefits (durability, washability, biodegradability) alongside efficacy claims.
-
Manufacturing innovation: Advances in fiber splitting and blend engineering are shrinking the cost premium for higher-performance microfiber, making technical upgrades feasible at commercial scale. This creates a practical path to upgrade product mixes without sacrificing gross margin.
Channel and commercialization implications
-
Retail mix: The household segment continues to be shaped by e-commerce assortment strategies, private label competition, and value bundles. Retailers that combine performance messaging with demonstrable sustainability credentials win higher attachment rates and lower returns.
-
Commercial procurement: Bids in institutional cleaning and healthcare increasingly specify technical performance and life-cycle cost — favoring vendors that can validate lab-tested efficacy and supply-chain traceability.
-
Specialty and precision niches: Eyewear, electronics, and medical applications demand tighter specifications and enable premium pricing. Companies that develop tailored offerings backed by certification and co-marketing arrangements can create defensible niches.
Competitive landscape — strategic positioning and implications
The market features incumbent brand power and nimble specialists. Below are strategic vignettes that highlight how different player archetypes are shaping the competitive field and what that means for strategy.
-
Global diversified incumbents (example: 3M Company) — Strengths: broad distribution, cross-category credibility, and multi-channel reach. Strategic implication: these firms can use brand trust to expand into professional and household segments simultaneously; challengers should seek vertical specializations or cost leadership to compete.
-
Premium sustainable specialists (example: Norwex) — Strengths: sustainability narrative, proprietary treatments (e.g., antimicrobial, plant-based enhancements), and direct-to-consumer relationships. Strategic implication: high-margin, mission-led players can pressure mainstream brands on premium segments and force regulatory-compliant product innovation.
-
Technical material leaders (example: Toray Industries) — Strengths: advanced fiber technology and precision products suitable for specialty cleaning. Strategic implication: partnerships with OEMs and medical suppliers open higher-margin channels where technical specifications limit competition.
-
Commercial solutions providers (examples: Freudenberg, Unger) — Strengths: integrated systems for facilities management and professional cleaning. Strategic implication: bundling cloths with services and equipment increases switching costs and improves lifetime value per customer.
-
Niche and wholesale players (examples: E-Cloth, Zwipes, Atlas Graham Furgale, Microfiber Wholesale) — Strengths: focused product portfolios, cost-competitive supply chains, and rapid response to channel demand. Strategic implication: they can erode share in value tiers or act as acquisition targets for scale players seeking product breadth.
-
Specialized healthcare suppliers (example: Medline Industries) — Strengths: regulatory credentials and distribution into hospitals/clinics. Strategic implication: compliance and certification create entry barriers for non-healthcare players, making this an attractive route for premiumization.
Recent industry moves to watch
-
Product innovation and reviews are influencing purchase flows: independent testing and review platforms continue to identify best-in-class products across price tiers, impacting short-term demand spikes.
-
Notable launches highlight two simultaneous trends: biodegradable and plant-infused microfiber formulations, and precision-targeted collections for eyewear and electronics — both signaling segmentation by sustainability and use-case performance.
-
Manufacturers are publicly advancing production technologies that reduce labor and material intensity, compressing cost curves and enabling more sustainable blends at scale.
Where value will accrue in 2026 — strategic playbook
-
Product architecture: Prioritize a two-track portfolio — a performance line for institutional and precision use cases, and a sustainability-branded retail line for households. Ensure modular packaging and SKU rationalization to minimize SKU proliferation costs.
-
Supply chain and manufacturing: Invest selectively in fiber-splitting and finishing capabilities that deliver measurable durability and wash-life gains. Seek backward integration or long-term supplier contracts to mitigate polymer price volatility.
-
Channel strategy: Accelerate partnerships with B2B distributors and facilities management firms while optimizing DTC and e-retail presence. Use data-driven assortment testing in e-commerce channels to identify top-converting claims (e.g., chemical-free, reusable X washes).
-
Commercial and institutional sales: Develop RFP-ready documentation, lab certifications, and lifecycle cost calculators to win specification-based contracts.
-
M&A and partnerships: Target bolt-on acquisitions that add technical capability (fiber tech or specialty finishing) or expand access to institutional contracts. Strategic partnerships with certification labs and sustainability NGOs can speed time-to-market for premium claims.
What the full PW Consulting report delivers
-
Practical toolkits — go-to-market playbooks for the four major end-use clusters, pricing sensitivity matrices, and SKU rationalization templates.
-
Channel and distribution models — scenario-modeled demand by retail vs. commercial channels, with prescribed inventory and promotional strategies for 2026.
-
Cost and margin analytics — raw-material passthrough scenarios, manufacturing technology ROI models, and break-even analyses for premium vs. value product lines.
-
Competitive maps — positioning matrices, capability heatmaps for the leading and emerging players, and acquisition target shortlists with synergy estimates.
-
Regulatory and sustainability playbook — compliance checklists, certification pathways, and consumer communication frameworks to translate policy shifts into market share gains.
Actionable recommendations for 2026
-
For manufacturers: Prioritize a capital allocation plan that balances incremental upgrades in production technology with immediate investments in product-testing and certification to win institutional contracts.
-
For retailers and distributors: Re-assess private-label margins against branded sustainability propositions; deploy targeted assortments and bundle offers in e-commerce channels to capture premium buyers without eroding value tiers.
-
For investors: Screen opportunities for platform buys that consolidate regional wholesale suppliers or acquire fiber-technology specialists that can be scaled across existing retail relationships.
-
For innovators: Focus on validated claims (biodegradability, wash-life, antimicrobial efficacy) and prepare a certification roadmap before large-scale commercial rollouts.
Closing — the strategic line for 2026
The microfiber cleaning cloths market in 2026 is a classic market of steady growth and strategic inflection. Regulatory pressures and consumer preferences favor reusable, higher-performing products; manufacturing innovations lower the cost to play at a premium; and the competitive landscape rewards both scale and technical differentiation. PW Consulting’s full report converts these dynamics into replicable actions — from SKU-level decisions to M&A targets and channel tactics.
To access the detailed segment-level models, proprietary demand scenarios, supplier scorecards, and downloadable execution toolkits that underpin these recommendations, consult the full Microfiber Cleaning Cloths Market report on our site. The public preview you have read is designed to establish the analytical framing — the full intelligence contains the tactical granularity required to execute effectively in 2026.
For detailed analysis of this topic, please visit the official page: Microfiber Cleaning Cloths Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


