



PW Consulting: Small Wind Turbines Market to Reach USD 344.8M by 2032 at 9.2% CAGR

Small Wind Turbines Market 2026 Preview: Strategic Signals for Corporate Decision‑Makers
As organizations plan capital allocation, product roadmaps, and partnership strategies for 2026, the small wind turbines market is emerging from the niche phase into a more structured, investment‑grade segment. PW Consulting’s forthcoming Small Wind Turbines Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market trajectories, technology inflection points, regulatory levers, and competitor positioning into an operational playbook for executives. This introduction highlights the study’s strategic value for 2026 decisions while preserving the granular segment intelligence available exclusively in the full report.
Small Wind Turbines Market
Macro trajectory: growth with defined momentum
The small wind turbines market has moved from an exploratory growth pattern during 2020–2024 into a clearer expansion phase by 2025. Our dataset shows the market at USD 215.0 Million (base year 2025), with a steady compound annual growth rate of 9.2% projected across the 2026–2032 forecast window. That trajectory implies the market expands meaningfully year‑over‑year, reaching the mid‑hundreds of millions by the end of the forecast period.
Small Wind Turbines Market
For corporate planners, that macro picture matters for three reasons:
Small Wind Turbines Market
- Capital planning: predictable market expansion supports multi‑year R&D budgets and staged capacity investments rather than one‑off bets.
- Commercial timing: accelerating adoption windows create opportunities for first‑mover pricing premiums in specialized niches (for example, hybrid off‑grid systems and integrated building solutions).
- Partnership windows: a steadily growing addressable market improves the ROI profile for channel partnerships, OEM supply agreements, and public‑private pilots.
Market structure and competitive concentration
The small wind segment remains fragmented relative to utility‑scale wind, with the combined revenue share of the three largest firms around the high‑20s percent and the top five firms covering the low‑30s percent of revenues. This level of concentration signals a competitive landscape with multiple viable independent vendors and space for regional specialists and technology innovators to capture value.
Key strategic implications:
- Opportunities for consolidation: modest concentration suggests roll‑up economics can create scale advantages in procurement, certification, and service networks.
- Room for differentiation: entrants that focus on system integration, digital O&M, or niche applications can build defensible positions without needing to be global leaders.
- Channel and after‑sales as moats: in a fragmented market, service capability and warranty programs often drive buying decisions more than headline nameplates.
Technology and cost signals
Our analysis integrates engineering cost benchmarks and levelized cost outputs that are central to commercial viability. Installed cost data indicate that small turbine systems (on the order of ~100 kW) carried material installed capital costs in recent years, while system LCOE for residential distributed wind has remained substantially higher than mainstream distributed solar—creating a heavy premium on innovations that improve energy capture and reduce balance‑of‑system costs.
What to watch in 2026:
- Direct‑drive permanent‑magnet machines and carbon‑composite blades: these technologies can reduce downtime and increase energy density for distributed applications.
- Integrated power electronics and hybridization with storage: pairing turbines with batteries and smart controllers materially improves dispatchability and utility interaction.
- Cost compression levers: modular tower systems, standardized permitting packs, and pre‑engineered foundations are immediate levers to lower installed cost per kW.
Regulatory catalysts and deployment activity
Policy is a proximate demand driver in the near term. Certification activity and targeted incentives are shaping developer and buyer behavior: by mid‑2025, certified small wind models are being tracked more closely by grid operators and grant programs; planned capacity additions and federal tax provisions with wage and apprenticeship clauses are anchoring commercial project economics.
- Certification growth: regulatory recognition reduces off‑taker and insurer friction, increasing commercial procurement readiness.
- Production tax credits and similar incentives: where projects meet stipulated requirements, per‑kWh credits materially improve payback metrics—an important consideration for project finance in 2026.
- State and utility pilots: planned capacity additions across multiple states show a willingness to test distributed wind in diverse operational contexts—opportunities for suppliers to secure demonstration pipeline work.
Competitive landscape — strategic profiles
The full report includes a systematic competitive matrix and supplier scorecards. Below are high‑level strategic profiles of established specialists and their relevant value propositions:
- Bergey Windpower Co. (Fort Collins, Colorado) — Deep experience with horizontal‑axis grid‑tied turbines. Products emphasize durable blade materials and direct‑drive simplicity, positioning Bergey for customers prioritizing long lifecycle costs and proven designs.
- Northern Power Systems Corp. (Waitsfield, Vermont) — Offers turbines up to roughly small‑utility/large‑commercial scales with an emphasis on broader application ranges (residential to rural commercial). Their strategic strength is modular product scalability.
- Eocycle Technologies Inc. (Montreal, Quebec) — Focused on direct‑drive permanent‑magnet machines for commercial and agricultural off‑grid applications. Eocycle’s technology proposition centers on reliability and minimal maintenance in isolated installations.
- Kingspan Group Plc (Kilkenny, Ireland) — Integrates small wind solutions into distributed power and building systems. Kingspan’s corporate strength is systems integration across thermal, storage, and generation—appealing to commercial real estate and industrial customers.
- XZERES Wind Corporation (Portland, Oregon) — Targets residential and commercial distributed generation with user‑oriented offerings and channel distribution strategies.
- Aeolos Wind Energy Ltd. (London, UK) — Focuses on compact horizontal‑axis turbines for residential and telecom applications, leveraging lightweight designs optimized for constrained sites.
For 2026, incumbent manufacturers and newcomers alike will need to pick a defensive axis—whether technology performance, integrated services, or channel breadth—to scale profitably in a market where service and certification are rising decision factors.
Practical content in the report — what executives will use immediately
PW Consulting’s report is engineered to support executable decisions rather than academic debate. Key operational modules include:
- Investment readiness checklist: a staged framework for assessing manufacturing scale, certification pipeline, and balance‑of‑system sourcing that aligns capex timing to demand windows.
- Go‑to‑market blueprints: product positioning templates and channel maps tailored for residential, commercial, and off‑grid applications, with suggested KPIs for pilot to scale conversion.
- Regulatory playbooks: step‑by‑step guidance for leveraging tax credits and certification pathways, including wage/apprenticeship compliance triggers and documentation templates.
- Procurement and supply risk assessment: supplier scorecards and contingency plans for material cost volatility, labor constraints, and critical component lead times.
- Scenario modeling tools: pre‑built financial models that stress test project economics under different LCOE, incentive, and uptime assumptions—designed for board‑level investment discussions.
Strategic moves to prioritize in 2026
Based on the integrated market and competitive analysis, PW Consulting recommends that companies evaluate an action plan organized around three pillars:
- De‑risk commercialization: Prioritize certification and standardized site permitting packages to reduce sales cycle friction. In 2026, buyers will discount suppliers without validated performance data and ready‑to‑deploy documentation.
- Differentiate through system outcomes: Shift selling propositions from turbine specifications to energy service outcomes—guaranteed uptime, integrated storage, and hybrid control systems that enable predictable dispatch and revenue.
- Build scalable service networks: Invest in regional service hubs and remote monitoring operations. Because balance‑of‑system and O&M determine lifetime cost, after‑sales presence will be a decisive competitive advantage.
Risks and leading indicators
Key risks to watch that could alter 2026 planning include raw material price shocks, labor cost inflation in key manufacturing hubs, and slower‑than‑expected adoption if LCOE improvements do not materialize. Leading indicators we track monthly include certified model counts, announced capacity pilot projects, and shifts in installed cost per kW. These indicators give early warning for tactical adjustments to production cadence and channel investments.
Why this matters for your 2026 boardroom conversation
In 2026, strategic choices in the small wind space will hinge on timing and focus. The macro growth rate and market size dynamics show a market that is large enough to justify targeted investment but small enough that inefficient capital allocation can be costly. The tactical guidance in our report helps executives answer high‑impact questions:
- When should we move from R&D demonstration to commercial production?
- Which certification and incentive pathways are prerequisites to meaningful commercial traction?
- Is it better to partner with an integrator, pursue acquisition, or focus on niche verticals?
Our 2026‑oriented recommendations give procurement, product, and corporate development leaders the concrete steps to align internal roadmaps with market windows—without overcommitting before certification and channel pull-through are validated.
Next steps
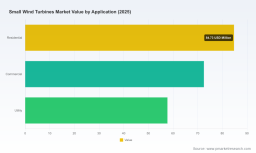
This article highlights the strategic signals and operational modules that PW Consulting considers most relevant for 2026 decision‑making. The full Small Wind Turbines Market report contains the granular segmentation, regional and application splits, detailed supplier scorecards, and downloadable financial models that will enable deal‑level diligence and investment memos.
Accessing the full report will provide the granular insights and numeric appendices needed to finalize budgets, select partners, and construct pilot programs for 2026. PW Consulting’s analysts remain available for tailored briefings and scenario workshops to translate the report’s findings into executable plans.
For detailed analysis of this topic, please visit the official page: Small Wind Turbines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


