



PW Consulting: FIBC market to reach USD 205.6 Million by 2032 at 5.42% CAGR

FIBC Market 2026: A Strategic Preview for Decision-Makers
As the flexible intermediate bulk container (FIBC) market enters a pivotal phase, 2026 presents leadership teams with a narrow window to convert regulatory disruption, material-cost volatility and shifting customer demands into durable competitive advantage. PW Consulting’s new FIBC Market study—anchored on a 2025 base year and stretching through 2032—was designed as a decision-grade toolkit for procurement directors, product leaders, corporate strategists and private-equity sponsors planning moves this year. The study synthesizes a clear macro narrative: the global market expands from USD 110.5 Million in 2020 to USD 141.6 Million in 2025 and is forecast to reach USD 205.6 Million by 2032, growing at a compound annual growth rate (CAGR) of 5.42% over the 2026–2032 forecast horizon. What follows is a focused preview of the strategic insights the full report contains and how executives should translate those insights into 2026 actions.
FIBC (Flexible Intermediate Bulk Container) Market
Why this study matters in 2026
-
Regulatory inflection: The EU’s Packaging and Packaging Waste Regulation (PPWR) starts to bite from mid‑2026, creating immediate compliance obligations (including documented recycled-content thresholds and harmonised recyclability declarations) that will re-shape sourcing, product design and supplier selection across supply chains that touch Europe.
FIBC (Flexible Intermediate Bulk Container) Market -
Material & margin pressure: Polypropylene remains the dominant fabric for FIBCs, and its feedstock economics remain tightly coupled to crude oil and refinery operations. That linkage injects episodic margin stress during refinery outages and commodity spikes—forcing manufacturers and end-users to re-evaluate pricing models and hedging strategies.
FIBC (Flexible Intermediate Bulk Container) Market -
Commercial and reputational risk: Buyers and brand-owners increasingly demand documented closed-loop recycling and chain-of-custody for packaging. Rapid movers that can demonstrate low-carbon FIBC options and verifiable recyclability will command a multiple in tender processes and long-term supply agreements.
What the PW Consulting FIBC study delivers (practical, executable content)
-
Transparent market sizing and trend tracking: a year-by-year historical view (2020–2025) and a granular forecast (2026–2032) that quantify the growth trajectory and allow you to stress-test demand scenarios across macroeconomic and regulatory outcomes.
-
Scenario modelling toolkit: embedded financial models that let you compare upside and downside cases—e.g., accelerated recycled-content mandates, sustained crude-price inflation, or rapid adoption of recycled feedstocks—so you can test portfolio outcomes and capital plans.
-
Commercial playbooks: tender templates, supplier-selection scorecards, pricing-index clauses and contract language designed to preserve margins amid raw-material volatility and regulatory transitions.
-
Product and compliance roadmap: step-by-step actions to meet PPWR-style recycled-content rules and recyclability labeling, including suggestions for pilot programs, supply-chain traceability and third-party verification.
-
Competitive benchmarks and opportunity maps: anonymised company-level benchmarking, manufacturing-capacity overlays and go-to-market heatmaps that identify logical consolidation targets, partnership prospects and green-innovation collaborators.
-
M&A and partnership worksheets: prioritised criteria for targets (capabilities, geography, vertical integration, recycling capability), valuation sensitivity, and earn-out structures aligned to regulatory milestones.
-
Procurement & operations diagnostics: supplier risk heatmaps, inventory and safety-stock optimization under commodity stress scenarios, and suggested specification changes to reduce TCO without sacrificing safety or compliance.
Competitive landscape — structure, players and strategic implications
The FIBC market exhibits a mixed structure: moderate concentration at the top and a long tail of regional specialists. Our analysis finds that the top three companies represent a notable share of the market and the top five capture a majority but not an overwhelming dominance—an environment that supports both scale advantages and niche competition. This structure produces three strategic archetypes you should be tracking and engaging with in 2026:
-
Integrated global packaging platforms: multi‑national groups that combine manufacturing scale, upstream raw-material sourcing and global distribution networks. These players can internalise recycled-feedstock procurement and amortise compliance investments across volumes, making them preferred partners for multinational buyers seeking standardised supply.
-
Regional specialists and exporters: smaller producers concentrated in Europe, South Asia, and North America that compete on speed-to-market, customisation and local logistics. They are often quicker to pilot material innovations and can be attractive bolt-on targets for larger acquirers looking to extend regional reach.
-
Innovation and sustainability leaders: firms that are developing commercially viable recycled-FIBC lines, closed-loop takeback programs or certification/traceability services. Early product launches (for example, a new 100% recycled rPET-based FIBC claiming significant carbon reduction) signal the beginning of a differentiation race where sustainability credentials increasingly determine tender outcomes.
For 2026, a clear priority for strategic sourcing teams is to map suppliers against these archetypes and to weight selection not only by price but by compliance readiness, recycling partnerships and traceability capabilities.
Market dynamics and near-term implications
-
Compliance timing is real—plan procurement and certification now: The mid‑2026 start of PPWR‑style recycled-content requirements leaves little runway for late movers. Companies must sequence compliance investments (testing, certification, documentation) to avoid supply interruptions and tender disqualification.
-
Recycled content changes input mix and cost dynamics: Expect short-term feedstock tightness for certified recycled polymers and a developing arbitrage between virgin polypropylene and rPP/rPET. Contract structures that allocate risk on recycled content sourcing will dominate supplier negotiations in 2026.
-
Innovation will be both product- and process-driven: successful market incumbents will combine material substitution (rPET, rPP), design-for-recycling, and third-party-proof-of-recycling to meet both regulatory and procurement screening criteria.
-
Events and product launches matter: keep an eye on industry milestones—recent product launches claiming steep carbon reductions and major association conferences scheduled for 2026 will set the market narrative and accelerate adoption curves.
Strategic playbook for 2026 — immediate, medium and strategic actions
-
Immediate (0–12 months): conduct a PPWR readiness audit; re-specify key SKUs for minimum recycled content pilots; build a prioritized supplier list segmented by compliance capability; insert index-linked clauses into new supply contracts to protect margins against polypropylene shocks.
-
Medium term (12–36 months): negotiate long-term supply agreements with recycled-feedstock clauses and shared investment in recycling capacity; deploy pilot closed-loop programs with selected customers; invest in labeling and digital traceability that satisfy harmonised recyclability declarations.
-
Strategic (36+ months): evaluate vertical integration into recycling or polymer compounding; pursue targeted acquisitions of regional specialist manufacturers to secure capacity and distribution; consolidate R&D investments to protect proprietary, low-carbon FIBC designs.
How to use this report in boardroom and operational decision cycles
The full PW Consulting report was built to be a living decision tool—not just a retrospective. It includes downloadable financial models, a supplier scorecard template, procurement negotiation scripts, and a regulatory-compliance calendar aligned to 2026 milestones. Use it to: run board-level scenario sessions, stress-test cash flow under commodity and compliance shocks, prioritise capex and M&A candidates, and operationalise sustainability commitments into commercial bids.
What we hold back (and why you’ll want the full study)
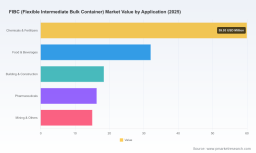
In this preview we deliberately surface the analytic framework, market trajectory and strategic implications while omitting granular regional and application-level splits and company market-share tables. Those precise segmentations, plant-level capacity maps and anonymised company revenue breakouts are central to transactional decisions—procurement tenders, M&A target screening and plant rationalisation—and are provided in full in the subscription report and accompanying data pack. That level of granularity is what transforms strategic intent into executable programs in 2026.
If your 2026 roadmap includes compliance sequencing, supplier consolidation, recycled‑feedstock sourcing or M&A, this study delivers the analytical backbone you need. The market is growing and evolving—companies with an evidence-based, scenario-informed plan executed in the first half of 2026 will convert regulatory risk into a sustainable advantage.
For detailed analysis of this topic, please visit the official page: FIBC (Flexible Intermediate Bulk Container) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


