



PW Consulting: Calcium Formate Market to Reach USD 1,140.46M by 2032 at 7.2% CAGR

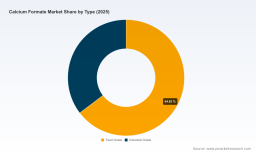
Calcium Formate Market — Strategic Imperatives for 2026 Decision-Making (PW Consulting)
As the calcium formate market accelerates from a mid‑decade inflection into a structurally larger industry, corporate strategies executed in 2026 will disproportionately determine competitive positions through the next investment cycle. PW Consulting’s industry synthesis uses a 2025 base year and an integrated forecast horizon to translate market movement into operational choices: the global market expanded from roughly 495 million USD in 2020 to about 701 million USD in 2025 and, at a compound annual growth rate of 7.2% over the forecast window, is directed toward just over 1.14 billion USD by 2032. This growth trajectory is real, measurable, and unevenly distributed across use-cases, geographies and grade types — a pattern that creates both concentrated opportunities and avoidable risks for manufacturers, feed companies, chemical distributors and investors.
Calcium Formate Market
Why this study matters in 2026
-
Timing matters: 2026 is the first full planning year after several structural shifts — regulatory clarity around feed use, raw‑material price turbulence and rising demand from construction and animal nutrition. Executives who translate these signals into tactical plans now will capture sustainable margin expansion.
Calcium Formate Market -
Cost volatility is no longer episodic: a March 2026 adjustment by a major formic acid supplier raised European formic acid prices by 250 EUR/MT, directly pressuring calcium formate production costs and tightening near‑term margins (BASF, March 2026). The incident is diagnostic: upstream commodity shocks propagate quickly through the value chain, and not all players have the same hedging or pass‑through capability.
Calcium Formate Market -
Regulatory enablers unlock demand: industry authorities have clarified safe use levels for calcium formate as a feed acidifying agent in swine and poultry (up to 1.2% of complete feed), lowering technical adoption barriers (AAFCO, Aug 2024). Simultaneously, Canada’s 2026 consultation on pre‑market amendments signals imminent market access expansion in North America (CFIA, Apr 2026). These developments change commercial priorities — registration, label claims, supply security, and channel partnerships — overnight.
What the full PW Consulting report delivers
-
Actionable demand model: a dynamic model that translates macro drivers (construction cycles, feed demand, seasonality) into revenue and volume scenarios under multiple policy and price pathways.
-
Cost‑to‑serve and margin blueprints: sensitivity analysis incorporating formic acid volatility, energy cost scenarios, logistics and packaging, and likely pass‑through thresholds by market.
-
Supplier risk heatmap: an evidence‑based ranking of raw‑material and intermediate exposures with recommended mitigation levers (contract terms, forward purchasing, tolling, backward integration).
-
Commercial playbooks: differentiated GTM strategies for industrial‑grade vs feed‑grade formulations, including channel architecture, pricing levers and product bundling approaches tailored to customer segments.
-
M&A and partnership screening: criterion‑based target shortlists and valuation sensitivities informed by likely consolidation vectors and regulatory tailwinds.
-
Regulatory tracker and registration roadmap: stepwise playbook to prioritize market entries, label claims and compliance actions across leading jurisdictions.
-
Executable 90/365/1,000 day roadmap with KPIs that link strategic choices to measurable outcomes for sales, margin, and working capital.
Competitive landscape — who shapes the market
The calcium formate competitive field combines specialty western manufacturers, integrated chemical groups, and a broad set of Chinese producers serving local and export markets. Competitive behavior ranges from technology and purity differentiation to price and volume plays. Key firms reviewed in this analysis include:
-
LANXESS AG (Germany) — positioned as a high‑purity specialty supplier with channel relationships in construction chemicals and adhesives; relevant for players prioritizing technical specifications and global distribution.
-
Perstorp Holding AB (Sweden) — highlighted for a sustainability and “green” product positioning, with explicit focus on feed additives and construction chemicals; attractive to customers seeking low‑footprint formulations.
-
MIKEM CHEMICAL (United States) — a specialist in mortars, tile adhesives and cold‑weather accelerators; represents a model of niche vertical integration and application engineering.
-
WOTAIchem, LANDU Chemical, Yuanwang Group, Jiangxi Kosin and Shandong Baoyuan (China) — collectively constitute a sizeable manufacturing base with cost‑competitive supply and proximity advantages in regional markets. Their strategic choices around export orientation, quality certification, and off‑take terms will influence global price dynamics.
-
American Elements and GEO Specialty Chemicals (United States) — supply industrial and laboratory grades, serving research, specialty industrial customers and small‑volume high‑margin applications.
From a structural perspective, the market shows a low-to-moderate degree of concentration: multiple credible producers coexist with differentiated routes to market (technical sales vs commodity distribution). That means price competition is real for bulk commodity grades, while technical and regulatory competence can sustain premium differentials for feed‑ and high‑purity products.
Recent dynamics that change playbooks
-
Raw material shock — BASF’s formic acid price action (Mar 2026) underscores the need for scenario planning and supply agreements that explicitly address feedstock pass‑through and force majeure language.
-
Regulatory clarifications for feed use (AAFCO, 2024) expand addressable market but raise registration and compliance costs: producers and feed formulators must operationalize safe‑use communications and quality assurance chains.
-
Policy windows — Canada’s regulatory consultation in 2026 creates a first‑mover advantage for firms that prepare pre‑market dossiers, sampling strategies, and local partner networks.
Strategic scenarios and recommended responses for 2026
-
Scenario: Cost‑push inflation from recurring formic acid spikes. Response: Lock in multi‑tier supplier contracts, implement raw‑material indexation clauses, and evaluate tolling or captive production where scale and capital economics justify it.
-
Scenario: Feed adoption accelerates post‑regulatory approval. Response: Prioritize feed‑grade GMP certification, launch targeted co‑development pilots with large integrators, and redesign packaging and logistics to fit feed‑mill purchasing patterns.
-
Scenario: Consolidation wave among mid‑tier producers. Response: Prepare a defensive M&A playbook — audit internal EBITDA drivers, identify bolt‑on capabilities (distribution, formulation know‑how), and set trigger valuations for opportunistic buys.
-
Scenario: Differentiation via sustainability claims and low‑carbon inputs. Response: Invest selectively in green chemistries, life‑cycle analysis, and transparent carbon accounting; use these as commercial levers in regulated and premium markets.
90‑day, 12‑month and 36‑month priorities
-
90 days — Rapid risk reduction: stress‑test supplier contracts, implement temporary cost‑recovery pricing bands, and launch a regulatory readiness sprint for priority markets (Canada and major feed markets).
-
12 months — Build capability: negotiate medium‑term supply agreements, launch at least one co‑developed feed product pilot, and upgrade QA/QC processes to support premium feed‑grade claims.
-
36 months — Structural moves: pursue selective backward integration or tolling arrangements, execute M&A or JV opportunities if they meet IRR and strategic fit thresholds, and scale differentiated product lines into new geographies.
How to use the report in board and investor conversations
Leaders will find the report particularly valuable in three contexts: capital allocation (capex vs buying), commercial strategy (price architecture and channel selection), and risk management (contracting and inventory policy). The materials are structured to support board decks and investor Q&A: executive summaries with one‑page scenario outcomes, a quantitative model that can be re‑run under user assumptions, and an annex with regulatory milestones and a supplier matrix.
PW Consulting’s edge
Our analysis combines primary interviews across the value chain, proprietary cost build‑ups, regulatory document mapping and scenario stress‑testing. We intentionally present a deep, actionable line of sight while withholding granular segment tables and exact regional shares in this preview; those finer allocations and the full excel model are available in the complete research pack. This “trailer” approach lets you validate the direction and implications quickly while reserving the detailed levers needed for transaction execution.
If your team is planning procurement strategies, product launches, or M&A activity in 2026, the decisions you make now will set the P&L trajectory through 2032. PW Consulting’s full Calcium Formate Market report equips you with the numbers, scenarios and playbooks required to act decisively — from immediate margin protection to long‑term positioning in feed, construction and specialty industrial channels.
For detailed analysis of this topic, please visit the official page: Calcium Formate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


