



PW Consulting: Glycated Albumin Market to Reach USD 425.6M by 2032 at 8.4% CAGR

Glycated Albumin Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
The Glycated Albumin (GA) market is transitioning from a niche laboratory assay to an established clinical adjunct for glycemic assessment — a shift with measurable commercial consequences for 2026 strategy. Our analysis shows the market expanding steadily from an estimated USD 163.15 Million in 2020 to USD 243.10 Million in 2025, and, under the base-case trajectory in this study, continuing to grow to approximately USD 425.6 Million by 2032 at a compound annual growth rate (CAGR) of 8.4% over the forecast period. Market concentration is moderate: the leading three and five companies account for meaningful but not dominant shares (CR3 ≈ 38.5%; CR5 ≈ 47.8%), reflecting an industry in which scale, regulatory positioning, and channel reach materially influence outcomes.
Glycated Albumin Market
Why 2026 is a strategic inflection point
-
Regulatory momentum and product approvals are lowering adoption barriers. Recent 510(k) clearances — notably a new FDA clearance for an enzymatic GA assay in early 2026 — shift the competitive landscape from «proof-of-concept» to «scale and reimbursement» execution.
Glycated Albumin Market -
Payer dynamics are stabilizing around established coding pathways for glycated proteins and hemoglobin measurements. Existing CPT-oriented reimbursement frameworks and leading private payer policies create a clearer commercial pathway for laboratories and device manufacturers that can demonstrate clinical utility and cost-effectiveness.
Glycated Albumin Market -
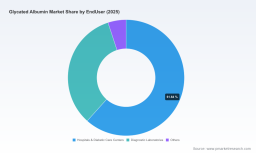
Buyer sophistication is rising. Hospitals, centralized diagnostic laboratories, and diabetes care centers increasingly demand validated, automation-friendly solutions that fit routine chemistry analyzers and integrated care workflows.
Market dynamics: what is driving growth
-
Evolving clinical use cases — beyond traditional hemoglobin A1c — are driving demand for GA assays as complementary markers in contexts such as short-term glycemic monitoring, pregnancy, and conditions where A1c is unreliable. These clinical niches are creating reproducible laboratory volumes that underpin commercial models.
-
Automation and analyzer compatibility are central. Assays designed to run on common high-throughput chemistry platforms shorten adoption cycles for hospital and reference labs and materially improve per-test economics.
-
Supply-chain and reagent commoditization pressures coexist with opportunities for differentiation. While antibodies, reagents and assay kits are increasingly available from multiple suppliers, manufacturers who combine robust validation datasets, strong distribution channels and analyzer partnerships maintain pricing power and uptake momentum.
Competitive landscape — what to watch in 2026
The competitive field spans multinational assay vendors, specialized reagents suppliers, laboratory service networks and distributor aggregators. Each player occupies strategic roles that set the agenda for partnerships, M&A and competitive responses.
-
Asahi Kasei Pharma Corporation (Tokyo) — A long-standing mover with an enzymatic GA assay designed for automated chemistry analyzers; regulatory clearances and CE marking give it credibility in hospital and laboratory channels. Its strategic advantage is validated assay performance combined with established distribution in key markets.
-
Diazyme Laboratories Inc. (Poway, CA) — Recent 510(k) clearance in March 2026 for an enzymatic GA assay compatible with major automated analyzers accelerates North American commercialization opportunities and intensifies competition on advanced automation and analyzer integration.
-
EKF Diagnostics Holdings plc (Cardiff, UK) — Acts as a regional distributor and facilitator for FDA-cleared products in certain markets, a role that underscores the value of channel partnerships for manufacturers seeking rapid geographic reach.
-
Lab networks and service providers (e.g., Laboratory Corporation of America) — In-house testing capabilities offered by national reference labs create a parallel commercialization route: they can both drive adoption and compress price realization for kit manufacturers unless captured via preferred supply agreements or co-marketing arrangements.
-
Reagent and R&D suppliers (Maccura, Abbexa, LifeSpan, Abnova, Geno Technology, Biocompare) — These vendors underpin assay development and validation. Their presence reduces technical barriers for new entrants but elevates the importance of clinical evidence, quality control and supply assurances as differentiators.
Strategic implications for suppliers and investors
-
Prioritize analyzer partnerships. Compatibility with major chemistry platforms materially shortens sales cycles for hospital labs and reference centers; assay format and automation readiness should be treated as core product requirements, not optional features.
-
Invest in payer evidence and coding strategy early. While reimbursement pathways exist for glycated protein testing, prospective and real-world evidence demonstrating impact on clinical decision-making — and on downstream cost metrics such as hospitalization or complication reduction — will determine adoption velocity and price realization.
-
Segment go-to-market by customer economics, not geography alone. Different end-users (hospital labs vs. reference labs vs. specialty diabetes centers) have distinct procurement cadences, capital access and throughput needs. Tailored commercial models — reagent-only, kit plus instrumentation, or service-led testing — will maximize penetration.
-
Consider consolidation and channel aggregation. Moderate concentration metrics indicate room for scale-driven deals: strategic mergers, exclusive distribution agreements, or lab-network partnerships can produce defensible scale and accelerate margin expansion.
-
Protect against commoditization with quality and support. Certification, lot-to-lot consistency, onboarding support, and local regulatory coverage (e.g., CE marking, FDA clearances) remain key purchase criteria that justify premium pricing.
What PW Consulting’s full study provides (practical deliverables)
Our Glycated Albumin Market report combines strategic narrative with operational toolkits. Key practical elements include:
-
Validated market sizing and trends (historical window 2020–2025, base year 2025) and scenario-based forecasts for 2026–2032, with sensitivity to reimbursement and regulatory timelines.
-
Commercial playbooks for three distinct supplier archetypes: global kit manufacturers, reagent innovators, and reference lab service models — including pricing levers, margin modeling and suggested contract structures.
-
A competitor product atlas and regulatory tracker mapping approvals, analyzer compatibility and clearance status across priority markets.
-
Go-to-market sequencing and roll-out templates that prioritize launches based on payer receptivity, lab automation density and clinical need clusters.
-
Evidence generation blueprints (study designs, endpoints, KOL engagement roadmaps) tailored to accelerate reimbursement and guideline inclusion.
-
M&A and partnership shortlist with high-level rationale and due-diligence checklists calibrated to the market’s consolidation dynamics.
-
Interactive financial models and ROI calculators that allow executives to test pricing, volume and channel scenarios against the provided macro forecast.
Immediate tactical recommendations for 2026
-
If you are a kit or reagent vendor: accelerate FDA/CE/region-specific submissions where needed; lock in analyzer OEM compatibility and prioritized distribution agreements; develop payer dossiers now rather than later.
-
If you are a reference lab: evaluate captive testing versus supplier partnerships; negotiate exclusivity or preferred-supplier pricing where assay quality and supply chain resilience justify it.
-
If you are an investor or M&A leader: target assets that combine validated clinical evidence with access to automation platforms and established distribution to capture scale as adoption moves from clinical niches to routine use.
Conclusion — the commercial window and how to access the full intelligence
By 2026 the Glycated Albumin market will reward players who combine regulatory foresight, payer evidence and channel integration. The market’s projected trajectory — from USD 163.15 Million in 2020 to an estimated USD 425.6 Million by 2032 at an 8.4% CAGR — signals a durable growth runway, but one that is outcome-dependent: technical compatibility, evidence generation and commercial partnerships will determine winners.
The overview above highlights the strategic imperatives and competitive moves that will shape 2026 outcomes. Our full PW Consulting report contains the detailed segmentation, modelled scenarios, company scorecards and downloadable financial models that decision-makers need to execute with confidence. Contact PW Consulting to access the complete dataset, interactive workbooks and a bespoke advisory session tailored to your role in the Glycated Albumin ecosystem.
For detailed analysis of this topic, please visit the official page: Glycated Albumin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


