



PW Consulting: Ultra Fine Aluminium Hydroxide Market to grow at 6.5% CAGR through 2032

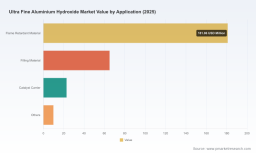
Ultra Fine Aluminium Hydroxide: Strategic Intelligence for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our Ultra Fine Aluminium Hydroxide (UF-AH) Market study — the actionable intelligence that will shape boardroom decisions in 2026. This piece distills the study’s core macro-trends, competitive dynamics, and decision-ready workstreams, while intentionally withholding the granular segment datapoints reserved for the full report. Use this as your operational compass: it explains where value will concentrate, which levers to pull this year, and how to structure near-term investments to capture the next wave of demand.
Ultra Fine Aluminium Hydroxide Market
Market snapshot: the growth vector you cannot ignore
UF-AH is no longer a niche additive — it sits at the intersection of regulatory-led product substitution, electrification of transport, and higher-performance polymerization. Our base year is 2025, and the market has expanded from roughly 212 Million USD in 2020 to an estimated 278.8 Million USD in 2025. Under the model used in this study the market continues to grow through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of roughly 6.5%, reaching an anticipated market size north of 400 Million USD by 2032.
Ultra Fine Aluminium Hydroxide Market
Why this matters for 2026: a sustained mid-single-digit CAGR combined with accelerating regulatory tailwinds converts steady top-line growth into strategically significant demand uplift for players that can match product performance with reliable supply. For decision-makers, the math is simple — scale matters because ultrafine performance is process- and capital-sensitive. The market is meaningfully consolidated: the top three suppliers account for a clear majority share, and the top five capture an even larger slice of industry shipments. That concentration creates opportunity for second-tier players with differentiated capabilities, and risk for buyers concentrated behind a small set of suppliers.
Ultra Fine Aluminium Hydroxide Market
Key structural dynamics shaping 2026 choices
- Regulatory substitution: Over 50 jurisdictions have tightened controls on halogenated flame retardants. This regulatory vector is structurally raising demand for non-halogen solutions such as ultra-fine aluminium hydroxide across transport, electronics, and consumer goods markets.
- Raw material and logistics pressure: Bauxite consumption in the wider supply chain increased year-over-year recently, tightening upstream availability. Concurrently, powdered chemical transport protocols have added measurable logistical complexity and cost, reducing trade flexibility and favouring geographically proximal production or vertically integrated suppliers.
- Product-performance premium: Sub-micron particle engineering, surface treatment, and slurry handling are differentiators. Buyers increasingly prize suppliers who can guarantee dispersion, low impacts on polymer rheology, and consistent flammability performance under real-world processing conditions.
- Consolidation and capability M&A: Capacity expansions and strategic asset transactions in 2024–2025 are evidence that incumbent players are investing to capture demand in automotive, electronics, and other high-margin end markets.
What this means for corporate strategy in 2026
For executives balancing growth and capital discipline, three strategic priorities should dominate planning cycles in 2026:
- De-risk supply via capability mapping: Ensure procurement strategies differentiate between particle-engineering capability (micronization, precipitation) and pure volume capacity. The latter will be necessary, but the former will command price and long-term contracts in high-value applications.
- Prioritise application-specific product roadmaps: Invest selectively in product formulations and surface treatments that reduce filler load while delivering flame-retardant performance and smoke suppression in polymers used in EVs, public transport, and consumer electronics.
- Localise or cluster production: Rising transport constraints and handling protocols make near-market or clustered capacity more attractive. Shorter supply chains reduce logistics risk and improve responsiveness for customers with strict delivery or qualification timelines.
Competitive landscape — who to watch and why
The competitive map is a mix of specialised European and Japanese technology players, global engineered-materials groups, and capacity-focused suppliers in China. Each archetype suggests different partnership or competitive tactics.
- Nabaltec AG (Schwandorf, Germany): Focuses on specialised ultra-fine grades optimized for flame-retardant efficacy. Its technical depth makes it an attractive partner for polymer formulators seeking performance predictability in demanding applications.
- Huber Engineered Materials (Atlanta, USA): Markets branded ultra-fine product lines noted for sub-micron particle control and smoke suppression. Recent corporate moves have expanded its product breadth, and the business model favours close commercial collaboration with OEMs.
- Resonac Corporation & Sumitomo Chemical (Tokyo, Japan): Two distinct Japanese manufacturers that bring precision precipitation and high-performance product portfolios suited to water-based systems and electronics-grade formulations.
- Almatis GmbH (Ludwigshafen, Germany): Known for high-purity ultra-fine grades targeting advanced ceramics and technical niches where impurity control and particle morphology are decisive.
- Chinese producers (Luoyang Zhongchao; CHALCO; Zibo Pengfeng): Competitive on scale and cost, with investments in automated micronization and capacity increases targeted at paints, rubber, and filler markets. These suppliers are important partners for cost-sensitive volumes and rapid qualification cycles in regional markets.
- Albemarle Corporation (Charlotte, USA): Announced capacity expansion efforts to meet vehicle electrification and electronics demand—evidence that large specialty chemical players view UF-AH as a strategic growth segment.
These profiles are not a list of recommended suppliers; they are a framework to evaluate strategic fit: technology-lead versus scale-lead, regional proximity, product purity, and service model.
Recent moves to factor into 2026 plans
- Capacity expansion by major players: Large material groups have publicly invested to enlarge ultrafine production, signalling a shift to treat UF-AH as core to their advanced-materials portfolios.
- Consolidation activity: Notable M&A transactions have aggregated capabilities — assets changing hands have included ultra-fine grades and downstream distribution channels, tightening the avenue for new entrants and raising the strategic value of bolt-on acquisitions for mid-size producers.
- Upstream volatility: Higher upstream throughput and tightened logistics protocols are increasing the cost-to-serve profile for trade-oriented supply chains, advantaging players that reduce handling steps or internalize key processing stages.
What the full PW Consulting report gives you (practical deliverables)
Our study is designed for corporate practitioners who must trade certainty for speed in 2026. The full deliverable includes:
- Market-sizing with a calibrated growth model (2020–2025 historical base; 2026–2032 forecast), and scenario casework for slower vs. faster adoption curves.
- Supplier-level capability maps and a procurement scorecard that ranks partners across particle control, surface chemistry, quality consistency, lead-times, and logistical risk.
- Commercial playbooks for suppliers and buyers: value-capture pricing approaches, contract structures (take-or-pay, throughput-linked pricing), and qualification timelines by end-market.
- CapEx/Opex modelling templates: plant-scale economics, micronization vs. precipitation process comparisons, break-even timelines under different demand ramp scenarios.
- Regulatory impact model: quantifies adoption drivers from halogen bans and offers sensitivity analyses for key jurisdictions.
- Risk matrix and mitigation strategies: raw-material sourcing scenarios, inventory hedging recommendations, and logistics-contingency planning for powdered-chemical handling.
- Deal origination briefings for M&A and joint-venture opportunities, including target selection filters and integration checklists.
How to use the intelligence in your 2026 planning cycle
- CEOs / Strategy Leads: Use the report’s scenario outputs to set investment bands for 2026–2028 CAPEX and to prioritize end-markets where premium pricing is sustainable (e.g., EV platforms, regulated transport interiors).
- Commercial Heads: Apply the procurement scorecard to reallocate sourcing across strategic suppliers, and pilot advanced specification contracts with performance-based SLAs tied to dispersion and smoke metrics.
- Supply Chain / Operations: Re-evaluate logistics footprints given tightened powdered-chemical protocols; consider clustered production close to major customers to reduce complexity and lead-times.
- Corporate Development: Use M&A filters to shortlist bolt-on targets that provide either particle-engineering IP or proximity to high-growth end-markets.
Risks you must monitor in 2026
- Upstream shocks: Any disruption to bauxite or alumina feedstocks will transmit quickly given the capital-intense nature of refining and micronization.
- Logistics & regulatory friction: Evolving transportation safety rules for powders can alter landed costs and qualification timelines; these must be modelled into supplier SLAs.
- Technology substitution: Competing flame-retardant chemistries or polymer-level innovations could change required ATH characteristics, pressuring legacy assets.
Conclusion — the strategic imperative for 2026
Ultra-fine aluminium hydroxide represents a mid-sized but strategically important market. Its combination of regulatory-driven demand, technical differentiation, and capital-intensity creates both barriers and opportunities. For firms that act in 2026 — by aligning procurement to capability, allocating capital to the right process technologies, and executing narrowly targeted commercial plays — there is potential to convert steady market growth into outsized margin recovery and sustained customer relationships.
The full PW Consulting Ultra Fine Aluminium Hydroxide Market report contains the granular segmentation, interactive models, and supplier-score templates that operational teams need to execute these recommendations. For the detailed breakdowns, regional scenarios, and downloadable decision-support tools, please consult the full research brief on our website.
For detailed analysis of this topic, please visit the official page: Ultra Fine Aluminium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


