



PW Consulting: Zinc Borate Market to Reach USD 344.8M by 2032 at 6.98% CAGR

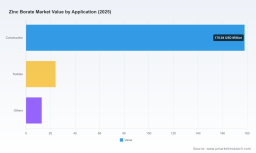
Zinc Borate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Market snapshot
As businesses plan capex, procurement and product strategies for 2026, zinc borate merits renewed strategic attention. Our PW Consulting baseline shows the zinc borate market growing from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025 (base year), accelerating to USD 234.17 Million in 2026 and projecting to USD 344.8 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 6.98% over the forecast window (2026–2032).
Zinc Borate Market
Those headline figures mask important non-linear dynamics: a strong recovery and premiumization of demand into mid-decade, momentary pressure points linked to feedstock and regulatory shocks, and pockets of persistent premium growth where high-purity and specialty grades command value. For decision-makers in 2026, the combination of mid-single-digit CAGR and episodic supply-side disruption spells both risk and strategic optionality.
Zinc Borate Market
Why this matters for 2026 decisions
-
Procurement and supply security — Boric acid, the primary feedstock for zinc borate, has shown price volatility and supply concentration. Buyers who finalize 2026 sourcing strategies without a robust hedging and dual-sourcing framework risk sudden cost spikes and lead-time extension.
Zinc Borate Market -
Regulatory and product positioning — Recent regulatory moves (notably updated restrictions and risk-management scopes for boric acid in certain jurisdictions) change use-cases and market access. Firms that act early to reformulate, certify alternative applications, or secure compliance documentation will preserve market access and pricing power.
-
Premium segmentation is accelerating — Demand for high-purity and REACH/region-compliant grades (for electronics, automotive, and high-end coatings) is growing faster than standard industrial volumes. 2026 is a year where R&D alignment and targeted commercial investments can unlock higher-margin channels.
-
Geopolitical and trade signals — Tariff actions and strategic expansions (including recent capacity projects in Turkey and new facilities online in 2026) are reshaping landed-cost equations and sourcing maps for 2026 purchasing cycles.
Market dynamics driving near-term outcomes
-
Feedstock concentration and price transmission — The boron value chain remains geographically concentrated. Supply interruptions or export policy shifts have historically transmitted quickly into zinc borate pricing and availability. In 2026, buyers should expect episodic price uplifts tied to feedstock tightness unless long-term contracts or tolling arrangements are negotiated.
-
Regulatory tightening in use-cases — Regulatory developments in 2024–2025 expanded scrutiny on boric acid and related substances in consumer and industrial applications. This influences formulation choices (e.g., substitution in cosmetics and sensitive consumer segments) and increases demand for compliant grades in industrial polymers and electrical applications.
-
Product differentiation — Manufacturers are differentiating on hydration state, particle size control, and low-impurity, high-purity grades for electronics and automotive. Technical service (formulation support, regulatory documentation) is becoming as important as price in certain accounts.
-
Supply-side evolution — New capacity coming online and expansions in strategically located facilities (notably new phase starts in 2026) relieve some near-term tightness, but uneven global footprint means local price and lead-time dislocations persist.
Competitive landscape — what to watch
The market retains a fragmented profile: market concentration metrics indicate the top three producers account for roughly a quarter of the market (CR3 ~24.6%), and the top five only slightly more (CR5 ~26.2%). That fragmentation produces distinct strategic postures across the supplier base:
-
Large integrated suppliers — Established players with vertically integrated access to boron feedstocks and legacy product lines are focusing on premium anhydrous and performance grades for polymers, wire & cable, and construction. Their strengths include scale, product breadth and global distribution networks.
-
Regional specialists and high-purity houses — Certain European and Turkish suppliers emphasize REACH-compliant, high-purity grades targeted at automotive and electronics. These firms compete on regulatory dossiers, tight impurity specifications and supply reliability for sensitive end markets.
-
Cost-focused producers — Several producers in price-competitive regions serve domestic and price-sensitive export markets with standard grades and high-volume throughput. Their play is cost leadership and short lead-times to nearby processors.
-
Service-led players — A set of specialized providers offers formulation advisory, regulatory support and certification packages — valuable for compounders facing regulatory headwinds or high-performance requirements.
Notable company dynamics to monitor in 2026 include announced capacity additions that are already influencing regional flows, product-grade positioning (e.g., anhydrous vs. hydrated grades), and the extent to which suppliers can back technical support with robust compliance documentation for regulated markets. These firms exemplify the commercial strategies in play: integrated feedstock security, geographical coverage, premium-grade focus, and regulatory documentation as a differentiator.
What our full report delivers (practical, transaction-ready outputs)
- Validated market sizing and growth scenarios (base year 2025; forecast 2026–2032) with modular sensitivity tables you can plug into financial models.
- Supplier scorecards covering capacity, technical capability, regulatory readiness and commercial terms — formatted for procurement negotiation playbooks.
- Supply-chain risk matrix and mitigation playbook (tactical options: dual-sourcing, inventory optimization, toll manufacturing, and feedstock hedging strategies).
- Regulatory tracker mapping jurisdictional risk to commercial impact across end markets, plus product reformulation decision trees for affected applications.
- Competitive landscaping with strategic profiles (strengths, weakness, likely moves) and an M&A screening tool to identify consolidation targets aligned to four acquisition theses.
- Price and margin bridge scenarios that reconcile feedstock volatility, tariffs, and premiumization strategies so commercial teams can stress-test 2026 price lists.
- Go-to-market playbooks for premiumization: technical validation checklists, certification roadmaps, and channel strategies for electronics, automotive and construction compounders.
Strategic recommendations for 2026 (what to do now)
-
Lock supply optionality early: Negotiate layered contracts that combine short-term spot capacity with medium-term supply agreements. Include clauses for feedstock-driven price pass-throughs and defined escalation caps.
-
Prioritize regulatory-proof product lines: If you sell into consumer-sensitive or regulated geographies, move to certify and document grades today. The cost of late certification in 2026 will be higher than the near-term investment.
-
Defend margins via product segmentation: Invest in R&D to create performance-differentiated grades commanding premium pricing in electronics and automotive. Pair technical support with sales to lock-in strategic accounts.
-
Screen acquisition and alliance targets: Use the report’s M&A screening tool to identify regional mills or tech-enabled specialists that deliver either feedstock security or premium-grade capability.
-
Hedge feedstock and logistics risk: Evaluate multi-sourced boric acid contracts, and consider tolling agreements or nearshoring to manage landed cost volatility amplified by tariffs and freight cycles.
-
Implement a regulatory monitoring cadence: Assign cross-functional ownership (R&D, legal, regulatory affairs) to track changes and pre-authorize reformulation budgets if jurisdictional risk rises.
Conclusion — the strategic view for 2026
Zinc borate is no longer a commodity-only story. The market’s mid-single-digit CAGR masks a bifurcation: standard industrial demand remains volume-driven and price-sensitive, while high-purity and compliance-backed grades are premium engines. Fragmentation in supplier shares creates opportunities for disciplined players to secure supply, capture premium segments, and pursue consolidation where it boosts scale or technical capability.
For any organization executing 2026 commercial, procurement or M&A plans, the critical success factors will be feedstock risk management, regulatory foresight, product differentiation, and an adaptive sourcing footprint. Our full PW Consulting report delivers the granular inputs, supplier assessments and executable playbooks required to turn this strategic view into 2026-ready decisions.
Next step
Access the complete report for the full dataset, segmented demand analysis, supplier scorecards and transaction-ready frameworks that we intentionally exclude from this preview. PW Consulting’s zinc borate study is designed to convert insight into action — and to protect your 2026 strategy from surprise shocks in feedstock, regulation and trade.
For detailed analysis of this topic, please visit the official page: Zinc Borate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


