



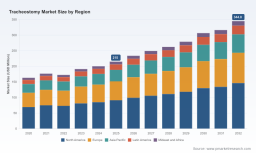
PW Consulting: Tracheostomy Market - From USD 215M (2025) to USD 344.8M by 2032 at 5.67% CAGR

Tracheostomy Market — 2026 Strategic Preview
As PW Consulting’s Lead Industry Analyst, I present this strategic preview of our full Tracheostomy Market study to orient executive decisions entering 2026. The global market for tracheostomy products has moved from a stabilizing post‑pandemic baseline into a predictable growth trajectory driven by ICU care patterns, procedural shifts, device innovation and supply‑chain resilience. Using 2025 as the study’s base year, our market model projects steady expansion at a mid‑single‑digit compound annual growth rate (CAGR of 5.67%) through 2032, with overall market value crossing multiple important inflection points during the forecast window. This preview highlights the report’s operational insights, competitive implications and the concrete strategic levers senior leaders should prioritize in 2026 — while preserving the detailed segment-level analytics that are available in the full report.
Tracheostomy Market
Why this study matters for 2026 corporate strategy
- Decision clarity in an incremental market: With the overall market expanding year‑over‑year, near-term investments (product R&D, manufacturing capacity, M&A) will compound over the 2026–2032 horizon. Understanding the timing and durability of growth is essential to avoid over- or under-investing in capacity and commercialization.
- Regulatory and reimbursement tailwinds and risks: Device approvals, standards compliance and modality‑level reimbursement dynamics will directly shape unit economics and go‑to‑market approaches in 2026.
- Fragmentation creates arbitrage: The market remains comparatively unconsolidated, creating acquisition and roll‑up opportunities for organizations that combine operational scale with clinical differentiation.
- Operational execution matters: Margins will be determined as much by sterilization, materials sourcing, and clinical support services as by device features. Tactical supply‑chain actions taken in 2026 will affect P&L for years to come.
What the full report delivers — practical, actionable content
Our study is designed for executives who need immediately actionable intelligence. Key deliverables include:
Tracheostomy Market
- Robust market sizing and forecasting model (base year 2025; predictive horizon 2026–2032) with scenario and sensitivity capabilities to test demand shocks, regulatory changes and price erosion scenarios.
- Epidemiology and procedure‑level demand drivers mapped to device consumption and consumable lifecycles, enabling SKU‑level revenue forecasting for commercialization teams.
- Regulatory compendium and compliance tracker: ISO norms, material‑spec updates and a timeline of recent clearances and adverse‑event reporting that affect product risk registers.
- Reimbursement playbook and procedural economics maps to help pricing, contracting and hospital sales functions optimize capture.
- Competitive benchmarking including capability maps (product breadth, manufacturing, regulatory footprint, and service offerings) and strategic profiles of leading and fast‑growing players.
- Supplier and raw‑material risk assessment with mitigation options for medical‑grade polymers, sterilization pathways and capacity constraints.
- Commercialization templates and a 90/180/360‑day tactical roadmap for market entry, product refresh or acquisition integration.
- M&A target screens and valuation guidance using earnings and margin improvement levers specific to tracheostomy product lines.
Key market dynamics shaping 2026 strategy
The report synthesizes primary research and proprietary models to isolate the following dynamics that will determine winners and losers in 2026:
Tracheostomy Market
- Stable, predictable growth: Our base scenario anticipates a continuation of mid‑single‑digit annual growth from 2026 onward. The overall market value grows noticeably between the base year and the mid‑2030s, offering a favorable backdrop for measured expansion.
- Procedure mix matters: Shifts between percutaneous and surgical approaches, and the increasing use of percutaneous techniques in many settings, alter accessory and disposables demand patterns. Companies that align product portfolios and training programs to procedural trends will capture outsized share.
- Materials and manufacturing evolution: The market continues to migrate toward medical‑grade polymers (PVC, silicone, polyurethane) and modern plasticizers to meet biocompatibility and regulatory expectations. EO and gamma sterilization pathways remain dominant and are a critical cost and quality axis.
- Regulatory and post‑market vigilance: Recent clearances for enhanced product variants and ongoing adverse‑event reporting underscore the dual importance of proactive regulatory strategy and robust post‑market surveillance to protect market access and brand value.
- Fragmented supplier landscape: Market concentration is low compared with many medtech categories, leaving room for consolidation and for nimble regional manufacturers to compete on cost and service.
- Reimbursement sensitivity: Procedural and device reimbursement structures materially affect hospital purchasing decisions and bundle economics. Aligning value propositions to these reimbursement realities is a precondition for volume penetration in 2026.
Competitive landscape — how incumbent and challenger strategies are shaping up
The competitive environment is heterogeneous, spanning global OEMs with extensive clinical relationships to regionally focused manufacturers and cost‑efficient contract producers. Key strategic archetypes we identify are:
- Global platform leaders: Large medtech companies that pair deep hospital relationships with broad product portfolios, differentiated cuff and inner‑cannula designs, and extensive regulatory dossiers. These players are selectively launching upgraded variants and pursuing indications that lock hospitals into platform buying.
- Specialist innovators: Firms focusing on design features (e.g., flexible cannulas, taper‑cuff technologies, disposable inner cannulas) and procedural kits that increase clinician preference and procedure efficiency.
- Regional cost players: Manufacturers with strong low‑cost production bases and aggressive global distribution strategies, competing on price and basic functionality while investing in regulatory harmonization to access new markets.
- Service‑oriented competitors: Organizations bundling devices with clinician training, tracheostomy care kits and post‑acute support to differentiate on total cost of care.
Recent market events in late 2024–2025 exemplify these dynamics: major suppliers have secured regulatory clearances for upgraded tube variants, while isolated adverse‑event reports underscore the reputational and regulatory risks that can accrue quickly. These signals reiterate the need for comprehensive regulatory and post‑market programs as part of any 2026 strategic plan.
Strategic plays to prioritize in 2026
Based on our analysis, companies should consider the following prioritized plays, tailored by scale and ambition:
- For global incumbents: Double down on differentiated product upgrades that target procedural efficiency and clinician safety, while using M&A to acquire regional manufacturing capacity and shorten time‑to‑reimbursement alignment. Invest in bundled care solutions to capture a larger share of lifetime patient economics.
- For mid‑sized companies: Focus on niche product differentiation (accessories, introducer sets, specialized cannulas) and build clinical evidence that supports premium pricing. Strengthen quality systems and adverse‑event monitoring to defend against regulatory headwinds.
- For new entrants and contract manufacturers: Target underserved geographies and service models that reduce hospital total cost of ownership. Prioritize regulatory readiness and clinical validation to accelerate adoption over price‑only competition.
- For investors and PE sponsors: Consider roll‑up strategies to consolidate manufacturing, rationalize SKUs and extract operational synergies in this fragmented market — high single‑digit CAGR and predictable procedural demand support disciplined buy‑and‑build value creation.
Translating insight into a 90/180/360‑day plan
- 90 days: Run a rapid portfolio fit assessment against our market model, validate top 3 product bets and initiate regulatory gap analysis for priority markets.
- 180 days: Execute clinical evidence generation plans, finalize supplier risk mitigations for polymer supply and sterilization, and pilot bundled service offerings with 1–2 hospital systems.
- 360 days: Launch revised commercialization strategy, integrate any targeted bolt‑on acquisitions, and begin scale‑up of manufacturing or contract production aligned to forecasted demand.
How PW Consulting supports execution
Our full report combines proprietary forecasting, primary interviews with procurement and clinical stakeholders, and supplier due‑diligence templates to convert insight into executable plans. We model multiple adoption and pricing scenarios and provide an M&A target list prioritized by integration ease and margin upside. For teams preparing 2026 budgets, the study delivers the market context and tactical playbook that align investment to expected return timelines.
To preserve the strategic value of the study as a decision‑support tool, this preview omits several granular segmentation tables and SKU‑level forecasts that are available in the complete deliverable. If you are preparing product investments, acquisition screenings, or commercialization plans for 2026, accessing the full report will provide the detailed segmentation, regional modelling, unit economics and scenario outputs you need to execute with confidence.
Contact PW Consulting to request the full Tracheostomy Market report and accompanying models, or to commission a tailored executive workshop that translates the forecast and competitive analysis into a 2026 action plan specific to your organization.
For detailed analysis of this topic, please visit the official page: Tracheostomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


