



PW Consulting: Medical Equipment Maintenance Market to Reach USD 57.0 Billion in 2025

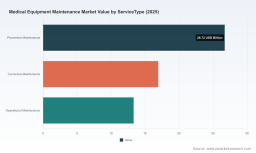
Medical Equipment Maintenance Market — Strategic Imperatives for 2026 (PW Consulting)
PW Consulting’s latest market study on Medical Equipment Maintenance uses a 2025 base year and a 2026–2032 forecast window to translate an accelerating service economy into executable strategy. At the macro level the market has expanded materially over the past five years and is set to nearly double through the forecast horizon, tracking a compound annual growth rate of 9.9%. These topline dynamics reflect reinvestment across installed equipment fleets, rising regulatory scrutiny, and rapid adoption of digital service models — all of which combine to make maintenance strategy a revenue and risk agenda for healthcare enterprises and investors alike.
Medical Equipment Maintenance Market
Why this study matters for 2026 decision-making
-
From a risk perspective, 2026 is a hinge year. New and clarified regulatory requirements (including the FDA’s updated Quality Management System provisions and consolidated accreditation expectations from major certifying bodies) fundamentally change the compliance baseline for both device manufacturers and organizations performing servicing. Decision-makers must reconcile operating models with explicit QMS expectations to avoid latent liabilities and continuity risk.
Medical Equipment Maintenance Market -
From a value-capture perspective, the service layer is shifting from break/fix and preventive routines toward continuous, software-enabled asset performance management. Recent regulatory guidance on AI/ML lifecycle management and the distinction between remanufacturing and servicing create both barriers and opportunities: vendors that embed compliant update pathways and transparent post-market change control will command premium contract terms.
Medical Equipment Maintenance Market -
From a portfolio-management perspective, the services market is concentrated: incumbents and high-capability platform providers account for a large share of enterprise service revenue, creating a two-speed market where global OEMs, specialised national providers, and health-system-owned HTM hubs coexist. Understanding where to compete or partner within that structure is critical for 2026 capital allocation.
What the PW Consulting report gives you — practical, implementable outputs
This study is designed as an executive-to-operational playbook. It moves beyond descriptive market sizing to provide the templates and decision-support tools leaders will use in 2026:
-
Scenario-based market sizing and growth drivers, with sensitivity models to stress-test capex and utilization assumptions against macro healthcare spending scenarios.
-
Service-economics and pricing frameworks: margin drivers for preventive vs corrective vs operational maintenance, and the profit implications of digital service monetisation.
-
Procurement and contracting playbooks for health systems: templated SLA language, performance metrics, and risk allocation matrices suited to AI-enabled and software-driven device fleets.
-
Vendor benchmarking and due-diligence checklists that evaluate technology stacks, regulatory readiness, and field-service capacity — calibrated for both OEMs and third-party providers.
-
M&A and partnership playbook: valuation levers, integration risk assessments, and an acquisition checklist focused on software assets, remote-monitoring capabilities, and spare-parts logistics.
-
Regulatory impact matrix that maps new QMS, PCCP and accreditation changes to operational gaps, staff certification needs, and documentation requirements.
-
Operational templates: predictive-maintenance pilot designs, HTM centre-of-excellence blueprints, talent & certification roadmaps, and sample financial models (TCO, OPEX vs CAPEX scenarios).
Competitive landscape — capabilities, moves and what they mean
The industry’s competitive topology is dominated by a set of global platform players complemented by specialised service firms and health-system-centered engineering organisations. Our analysis profiles the leading providers and recent strategic moves that illustrate the direction of travel:
-
GE HealthCare (Chicago) — has reinforced a platform-plus-services strategy by acquiring software assets and entering long-term care alliances. Recent M&A and multi-year care alliances underscore a playbook of bundling hardware, enterprise software, and predictive-service contracts to lock in recurring revenue.
-
Siemens Healthineers (Erlangen) — continues to emphasize integrated diagnostic and lab maintenance with remote monitoring capabilities, positioning itself to sell end-to-end uptime guarantees to large hospital systems.
-
Koninklijke Philips (Amsterdam) — is leveraging advanced informatics and FDA-cleared predictive features to move service offerings up the value chain toward outcome-linked contracts.
-
Medtronic (Dublin) and B. Braun (Melsungen) — exemplify OEM-led lifecycle management for implantables and therapy-centric devices, where servicing is tightly coupled to clinical pathways and supplier risk management.
-
STERIS, Agiliti, TriMedx and specialist operators — provide infection-prevention, large-scale HTM, and clinical-engineering services that are becoming strategic partners for health systems seeking centralized, high-quality, cost-effective maintenance solutions.
These provider moves are more than headlines; they represent strategic playbooks investors and operators must evaluate: consolidate service portfolios through targeted acquisitions, invest in software and remote monitoring to convert episodic revenue into predictable streams, and secure regulatory compliance as a market-entry barrier.
Recent developments you should factor into 2026 plans
-
Consolidation and strategic partnerships among OEMs and enterprise service providers are accelerating — examples include significant acquisitions and multi-year alliance agreements that combine imaging software with service delivery networks.
-
Regulatory shifts in 2024–2026 clarified servicing vs remanufacturing, formalized AI/ML update pathways and tightened QMS expectations. Organizations that delay alignment expose themselves to increased inspection risk and contractual noncompliance.
-
Providers are scaling centralized HTM infrastructure — new facilities and lab-focused HTM hubs show demand for high-throughput, standardized maintenance workflows that reduce mean-time-to-repair and spare-part inventories.
Strategic playbook — recommended moves by stakeholder
-
OEMs: Accelerate investment in service SaaS platforms and PCCP-aligned architectures. Pursue tuck-ins that bring telemetry, scheduling automation, and spare-parts optimisation. Structure contracts to shift a portion of revenue into recurring service streams while preserving lifecycle compliance evidence.
-
Health systems: Execute a rapid compliance and capability audit this quarter. Use TCO models to compare in-house HTM expansion vs outsourcing to a platform provider; prioritize pilots for predictive maintenance on high-value imaging and life-support fleets to validate savings and safety metrics.
-
Third-party service providers: Differentiate through regulatory certification, rapid-response field networks, and outcomes-based SLAs. Consider vertical specialisation (e.g., imaging, dialysis, infusion) to counterbalance scale advantages of OEMs.
-
Private equity and strategic investors: Target software-enabled service platforms and bolt-on HTM assets with stable recurring cashflows. Look for businesses that have proven ability to scale remote monitoring and to comply with tightened QMS expectations.
From insight to action — a 90-day operational checklist
-
Conduct a regulatory-gap diagnostic against the new QMS and accreditation standards.
-
Run a rapid inventory and risk-prioritization of critical assets; identify three high-impact pilots for predictive maintenance.
-
Renegotiate or reframe service contracts to include transparent performance metrics and audit-ready documentation flows.
-
Initiate vendor diligence on service platform vendors; evaluate software maturity, PCCP readiness and spare-parts logistics.
-
Assess the strategic fit of potential M&A targets: software IP, field-service footprint, and regulatory-compliance posture should be primary filters.
Conclusion — why previewing this analysis matters
As capital deployment decisions are made in 2026, the medical equipment maintenance market will be a decisive battleground for both revenue growth and operational resilience. The macro opportunity is unambiguous — robust growth and accelerating monetization of digital services — but the competitive and regulatory terrain has become more complex. PW Consulting’s full report equips leaders with the scenario-tested models, regulatory mappings, vendor scorecards and operational tools needed to convert market momentum into defensible advantage.
Note: this executive preview highlights study scope, strategic implications and actionable playbooks but omits the granular segmentation tables and device- and region-level models that are essential for transaction-level decisions. For the full data appendices, device- and service-level breakouts, company profiles and downloadable financial models, please visit the report page on PW Consulting.
For detailed analysis of this topic, please visit the official page: Medical Equipment Maintenance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


