



PW Consulting: Air Quality Sensor Market to Reach USD 10.14B by 2032 at 7.9% CAGR

Air Quality Sensor Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, strategy-first introduction to our new Air Quality Sensor Market study. This brief synthesizes the macro trajectory, competitive dynamics, regulatory inflections, and the practical implications that senior executives, product leaders, and investors must internalize heading into 2026. The objective is to demonstrate the analytic depth and actionable orientation of the full report while intentionally withholding detailed sub‑segment tables and regional allocations — those are available in the source report for subscribers.
Air Quality Sensor Market
Executive snapshot: Why this market matters in 2026
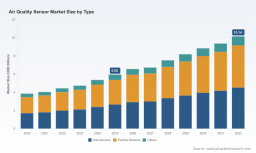
The global air quality sensor market is no longer a niche industrial play; it is a convergence point for smart buildings, environmental regulation, industrial safety, and consumer health. From 2020 through 2025 the market expanded steadily, and by our base year (2025) total industry revenues reached USD 5.95 Billion. Under a central‑case scenario, the market is forecast to continue expanding at a compound annual growth rate (CAGR) of 7.9% over the 2026–2032 horizon, ending the forecast period above USD 10 Billion.
Air Quality Sensor Market
That growth trajectory translates into meaningful strategic choices in 2026: allocate R&D and product roadmaps to emerging sensor modalities, reconfigure supply chains to mitigate raw‑material and component risk, and sharpen commercial models (SaaS + hardware bundling, retrofit programs, and outcome‑based service contracts) to capture recurring revenue.
Air Quality Sensor Market
Market trajectory (concise)
- Historical momentum: consistent year‑on‑year growth through 2025, reflecting accelerating demand from buildings, industrial monitoring, and consumer devices.
- Near‑term outlook (2026–2032): 7.9% CAGR supports both volume growth and pockets of pricing pressure as sensor commoditization coexists with demand for higher‑accuracy platforms.
- Structure: the market exhibits moderate concentration — the top three vendors account for roughly a quarter of market sales, while the top five approach one‑third — leaving ample scope for niche specialists and system integrators to win commercial share.
Key dynamics shaping 2026 decisions
- Technology bifurcation: Two concurrent trends will define supplier strategy. First, cost‑optimized MEMS and low‑cost electrochemical modules enable massive deployments in consumer and retrofit applications. Second, higher‑accuracy optical, laser, and industrial electrochemical sensors are gaining traction in regulated, safety‑critical, and industrial environments. Product portfolios and roadmaps need to reflect both segments rather than betting on a single technology path.
- Lifecycle and total cost of ownership (TCO): Field evidence shows wide variation in service life for low‑cost sensors (typical operating lifetimes range from months to a couple of years). Buyers are increasingly evaluating TCO (replacement cadence, calibration, warranty) rather than upfront BOM cost alone. Procurement teams in 2026 will favor vendors that can demonstrate field durability and predictable maintenance economics.
- Raw‑material and supply‑chain risk: New export controls and trade restrictions introduced in 2025 have altered access to certain magnetics and rare earth inputs fundamental to actuators and some sensor assemblies. Manufacturers should model supplier concentration, qualify alternative sources, and consider longer purchase commitments or local buffer inventories.
- Regulatory validation and public trust: Independent field evaluation programs (e.g., 2026 AQ‑SPEC reports) are shaping buyer perceptions. Vendor claims without third‑party validation are increasingly treated with skepticism. Certification and transparent performance data will be procurement table stakes for municipal and enterprise tenders.
- Commercial model evolution: Expect accelerated adoption of subscription and data‑services models (sensor + analytics + compliance reporting). System integrators and platform providers who can convert raw sensor streams into regulatory‑grade insights will capture a premium.
Competitive landscape — who matters and why
The vendor ecosystem spans global industrial conglomerates, specialized sensor OEMs, and nimble niche players. Our assessment highlights strengths, strategic positioning, and near‑term moves for the companies that matter to buyers and investors in 2026.
- Honeywell International Inc. (Charlotte, NC) — Industrial‑grade product focus with solutions such as MIDAS and Sensepoint that are positioned for commercial and heavy‑industry monitoring. Honeywell’s strengths are system integration, compliance credentials, and installed base services.
- Sensirion AG (Staefa, Switzerland) — Known for compact all‑in‑one environmental modules (e.g., SEN5x family). Sensirion continues to push accessible, validated modules for both indoor and outdoor monitoring; recent integrations with consumer and OEM partners have broadened their addressable market.
- Bosch Sensortec GmbH (Reutlingen, Germany) — MEMS‑centric sensors optimized for space and power constrained devices (e.g., multi‑parameter 4‑in‑1 sensors). Bosch brings economies of scale and strong relationships with device OEMs in consumer and building automation segments.
- Alphasense Ltd (Southampton, UK) — Specialist in high‑accuracy electrochemical and optical sensors for industrial and environmental monitoring; recently launched a lead‑free oxygen sensor — a product development that signals investment in differentiated chemistries and regulatory‑sensitive applications.
- Figaro Engineering Inc. (Osaka, Japan) — Longstanding play in electrochemical gas sensors for toxic gas detection. Figaro remains a key supplier for safety‑driven applications where certification and reliability are prioritized.
- Siemens AG (Munich, Germany) — Integrates improved air quality sensing with building management systems, adding UX upgrades (touchscreens, mobile integration) that lower installation friction and user acceptance barriers.
- Teledyne Technologies, TSI, 3M, Aeroqual — Together these vendors cover niche industrial, laboratory, particulate counting, and portable monitoring segments. Their differentiated value comes from measurement accuracy, data quality, and turnkey systems.
Recent vendor moves underscore two themes: (1) product integration with partner ecosystems (e.g., Sensirion modules appearing inside third‑party consumer monitors), and (2) targeted product innovation for verticals (e.g., Alphasense’s lead‑free oxygen sensor and AKCP’s data‑center targeted all‑in‑one units). Siemens’ product refinement toward better UX shows that non‑technical buying criteria — maintainability, UI, and software integration — matter increasingly.
What the PW Consulting report delivers (practical, operational outputs)
Our full study is structured for immediate operational use by C‑suite and business‑unit leaders. Highlights include:
- Market sizing and scenario modelling (TAM/SAM/SOM) through 2032 with sensitivity cases for price erosion and accelerated regulation.
- Vendor scorecards and product‑capability matrices aligned to buyer use cases (consumer, commercial buildings, industrial safety, ambient monitoring).
- Go‑to‑market playbooks for OEMs and systems integrators: channel strategy, bundling, service pricing, and retrofit sales tactics.
- Supply‑chain stress tests and alternative sourcing strategies for critical components, including cost‑impact simulations under export controls.
- Regulatory impact assessment and certification roadmap for municipal tenders and industrial compliance programs.
- Operational toolkits: procurement RFP templates, field validation protocols, and calibration/maintenance costing models.
- M&A and partnership screening: acquisition targets by capability gap and financial threshold, with integration risk checklists.
Strategic imperatives for 2026 (what leaders must act on now)
- Manufacturers: Prioritize modular product platforms that separate sensing elements from connectivity and analytics. This enables faster upgrades to sensing chemistries without replacing entire devices — a crucial competitive advantage given short lifecycles for low‑cost units.
- OEMs and device makers: Negotiate multi‑year supply agreements and dual‑sourcing strategies for critical sensor components. Consider in‑house calibration services or certified third‑party partners to reduce warranty exposure.
- Systems integrators and software providers: Build validated analytics packages and compliance reporting modules. Market differentiation will come from delivering regulatory‑grade insights, not raw data streams.
- Investors and corporate development: Look for targets that combine high‑accuracy sensing with service‑oriented revenue models, or niche players that can be scaled through distribution partnerships. Given the market’s moderate fragmentation, tuck‑in acquisitions remain an efficient way to broaden capability.
- Public sector and policymakers: Align procurement specifications to field‑validated performance benchmarks and mandate transparent reporting of calibration and maintenance costs to avoid perverse incentives toward lowest‑cost hardware.
Risk register — issues that could reshape the outlook
- Regulatory changes and trade controls affecting key inputs (recent government export controls introduced in 2025 are a material operational factor).
- Rapid commoditization leading to "race to the bottom" pricing in consumer segments, compressing margins unless offset by services.
- Reputational risk from poor field performance — independent validation programs released in 2026 are already influencing procurement decisions.
- Supply shocks and component obsolescence tied to rare‑earth and magnet supply constraints.
What we are not publishing here — and why
This introduction is intentionally a “trailer”: it demonstrates the analytic framing, strategic orientation, and practical outputs of our full study while withholding detailed sub‑segment tables, deployment maps, and granular regional/application revenue breakdowns. Those detailed slices — essential for procurement tendering, M&A valuation, and product portfolio prioritization — are reserved for the full report and accompanying data annex. If your 2026 strategy depends on where to invest at the country, application, or technology‑level, you will need the complete dataset and scenario outputs.
Next steps — how to use the full study
- Subscribe or request the full report to receive the complete dataset, vendor scorecards, and scenario models.
- Engage our advisory team for a tailored 2‑day executive workshop: align board‑level strategy to product roadmaps, procurement policies, and M&A targets for 2026.
- Commission a short supplier due‑diligence scan or a calibration & validation pilot to de‑risk large OEM deployments.
In summary, the air quality sensor market is growing and evolving in ways that will materially affect product roadmaps, procurement strategy, and M&A activity in 2026. With total market revenues surpassing USD 5.9 Billion in 2025 and a projected climb to over USD 10 Billion by 2032 at a 7.9% CAGR, the window for shaping competitive advantage is open — but only for organizations that align technology choices, supply‑chain resilience, and commercial models to the market’s emerging realities.
For the full dataset, scenario workbooks, and the vendor playbooks referenced above, access the complete PW Consulting report or contact our advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


