



Industrial Refrigeration Equipment Market to Reach USD 31.73 Billion by 2032 at 4.9% CAGR

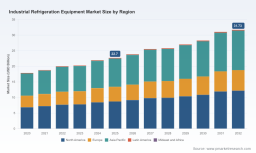
Industrial Refrigeration Equipment Market: Strategic Preview for 2026 Decision-Making
As organizations finalize 2026 capital plans, procurement strategies, and product roadmaps, the industrial refrigeration equipment market presents a clear—but nuanced—growth trajectory and a compressed decision window. PW Consulting’s latest market study, based on a 2025 base year with a historical series from 2020–2025 and a forward-looking forecast through 2032, quantifies the opportunity and, critically, maps the operational and regulatory inflection points that will determine winners and losers over the next business cycle.
Industrial Refrigeration Equipment Market
Market snapshot: direction, scale, and growth dynamics
The global industrial refrigeration equipment market reached an established baseline in 2025 and is set to expand through the 2026–2032 forecast period at an underlying compound annual growth rate of 4.9%. Under current assumptions the market scales materially by the end of the forecast window, driven by a combination of regulatory-driven equipment replacement, rising cold-chain demand in strategic verticals, and incremental modernization of legacy assets.
Industrial Refrigeration Equipment Market
Two broad features define the market environment for 2026: (1) accelerating regulatory pressure that forces technology transitions and retrofits within narrow compliance windows, and (2) persistent supply‑side cost pressure for metallic and electromechanical components. These twin forces compress project timelines and elevate the value of near-term strategic clarity for buyers, OEMs, and investors.
Industrial Refrigeration Equipment Market
Why this research matters for 2026 decisions
- Timing is decisive: New regulatory prohibitions and energy-efficiency mandates create binding upgrade deadlines for many industrial cooling projects. Delays in specification changes or procurement can produce project cost surprises or compliance gaps.
- Technology selection is value-creation: Natural refrigerant systems—particularly CO2 and ammonia architectures—are moving from niche to mainstream. Equipment and system-level choices made in 2026 will lock in operating economics and regulatory compliance for a decade.
- Supplier and supply-chain risk: Tariff regimes and commodity inflation require re-evaluating supplier contracts, inventory strategies, and vertical integration options to protect margins and delivery schedules.
- Competitive positioning: The market remains moderately concentrated: leading equipment and component vendors hold meaningful but not dominant shares, which keeps strategic sourcing and strategic partnerships practical levers for end users and mid-market OEMs.
Core industry dynamics shaping 2026
- Regulatory accelerants: U.S. and international rules enacted or finalized through late 2025 and into 2026 (notably new EPA mandates and related implementation rules) restrict high‑GWP refrigerants in new industrial and commercial systems. These requirements create immediate demand for compliant new-builds and triggered retrofits in selected subsegments.
- Efficiency mandates: National energy authorities have signaled compressors and industrial refrigeration as priority categories for tightened efficiency standards, raising the bar for new equipment designs and requiring manufacturers to validate performance under stricter test and reporting regimes.
- Material cost pressure: Elevated tariffs and import levies on steel and aluminum have pushed up the landed cost basis for condensers, compressors, and structural frameworks; procurement teams must adjust total-cost-of-ownership models accordingly.
- Technology diffusion: Recent trade shows and conferences demonstrate a clear migration toward CO2 transcritical and optimized ammonia solutions; vendors are rapidly fielding compressors, condensing units, valves, and heat-exchanger packages tuned for natural refrigerants.
What the PW Consulting report delivers (practical, action-oriented components)
- Market sizing and validated forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles so commercial leaders can stress-test capex plans against alternative regulatory and commodity-price paths.
- Segment-level demand drivers and adoption curves by technology family and end market—presented in a way that preserves competitive confidentiality while giving buyers a tactical playbook for specification timing.
- Vendor benchmarking and sourcing scorecards that synthesize product portfolios, service footprint, compliance readiness, and price-to-performance tradeoffs (structured for procurement RFx readiness).
- Capital and operating-cost models for retrofit vs. new-build decisions, including sensitivity tables that let finance teams quantify NPV and payback across refrigerant choices and efficiency classes.
- Regulatory compliance checklist and implementation timeline with recommended control points for legal, engineering, and procurement teams to reduce deployment and permitting risk.
- M&A and partnership screening criteria tailored for strategic acquirers and investors seeking entry points in component manufacturing, aftermarket services, and system integration.
- Case studies and implementation templates: procurement schedules, contractor evaluation matrices, and training requirements for safe operation of natural refrigerants.
Competitive landscape: who matters and where to place bets
The vendor set is populated by global OEMs, specialized component makers, and turnkey integrators. Market structure is best described as moderately fragmented: a handful of well-capitalized incumbents lead on product breadth and channel reach, while a tier of focused specialists competes on niche capabilities such as CO2 fittings, transcritical compressors, or turnkey project delivery. For 2026, strategic decision-makers should evaluate partners on four dimensions: regulatory readiness, system efficiency, aftermarket footprint, and supply-chain resilience.
- Heatcraft Refrigeration Products — Renowned for unit coolers, condensers, and evaporators targeted at commercial and industrial refrigeration. Strategic value: deep channel access and modular product lines that accelerate retrofit deployments.
- Magna Industrial Refrigeration — Provides industrial equipment, components, and systems; closely integrated with Heatcraft capabilities in many markets. Strategic value: breadth of solutions for multi-site rollouts and component-level flexibility.
- NDL Industries — Specialist in high‑pressure CO2 fittings, valves, and stainless‑steel components. Strategic value: critical supplier for reliable natural‑refrigerant installations and a sensible partner for reducing RTO risk on CO2 projects.
- Danfoss — Offers packaged CO2 condensing units, CO2 compressors, and transcritical refrigeration systems. Strategic value: product innovation leadership, strong controls integration, and a proven roadmap for regulatory compliance.
- Copeland — Supplies transcritical CO2 scroll compressors with advanced control features (e.g., dynamic vapor injection) and low‑temperature subcritical scrolls. Strategic value: compressor technology that optimizes partial-load efficiency and reduces lifecycle costs.
- Bock GmbH — Maker of semi‑hermetic compressors targeted at industrial and cold‑storage markets. Strategic value: robust designs for heavy‑duty process cooling and proven OEM partnerships.
- Frigo Mekanik — Regional specialist for project design, manufacturing, and turnkey installations. Strategic value: local engineering expertise and turnkey delivery capabilities in fast-growing regional markets.
Recent industry activity—product launches and demonstrations showcased at the AHR Expo 2026 and focused events like the IIAR Natural Refrigeration Conference—corroborates the shift toward CO2 and other natural refrigerants. These events also highlight increasing vendor readiness around system controls, valves, and compressor innovations designed specifically for transcritical operation and region‑specific compliance.
Implications for buyers, OEMs, and investors in 2026
- Buyers: Prioritize procurement of systems that are both compliance-ready and demonstrably efficient at expected duty cycles. Require vendor disclosure on refrigerant lifecycle impacts, service network coverage, and spare‑part availability under current tariff regimes.
- OEMs and integrators: Accelerate validation programs for natural refrigerant platforms, lock down critical components (compressors, valves, heat exchangers) through strategic sourcing or minority equity partnerships, and update training programs to reduce commissioning risk.
- Investors and acquirers: Focus on service platforms, component specialists with IP in CO2 handling, and system integrators with demonstrated project delivery in regulated markets—these assets offer defensive positions against equipment obsolescence and regulatory churn.
Decision playbook for 2026 (high-level)
- Map all existing assets against 2026 regulatory triggers; classify projects into immediate retrofit, short-term replacement, and multi-year modernization buckets.
- Require vendor compliance roadmaps and third‑party verification as a bid prerequisite; make lifecycle cost and compliance risk explicit in procurement scoring.
- Hedge raw‑material exposure via multi‑sourcing and inventory buffers for long‑lead components; explore localized fabrication to mitigate tariff impacts.
- Invest in operator training and digital service agreements to reduce operational risk and to monetize efficiency gains post‑installation.
Next step — deeper intelligence available in the full study
This preview frames the strategic stakes and immediate levers for 2026. The complete PW Consulting Industrial Refrigeration Equipment Market study provides the granular datasets, scenario-adjustable forecast models, vendor scorecards, and executable templates that commercial leaders need to move from strategy to procurement execution. For market-level drilldowns, detailed product and application forecasts, and downloadable spreadsheets that support board-level investment decisions, consult the full report page and accompanying data pack.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


