



PW Consulting: Strain Gage Market to hit USD 316.6M by 2032 at 4.55% CAGR

Strain Gage Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive introduction to our latest Strain Gage Market study — a tactical briefing designed to shape capital allocation, product roadmaps, procurement strategy, and M&A decisions in 2026. The report synthesizes rigorous historical tracking (2020–2025), detailed supplier and application analysis, and a scenario‑based forecast through 2032. It is purpose-built to convert sensor‑level data into boardroom actions while preserving the merchantable intelligence that drives competitive advantage.
Strain Gage Market
Why this study matters in 2026
-
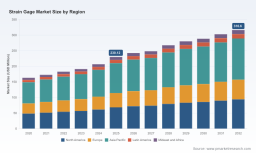
The global strain gage market has progressed from approximately USD 163.2 Million in 2020 to USD 230.1 Million in our base year (2025), reflecting steady expansion across instrumentation, structural monitoring, and industrial sensing applications.
Strain Gage Market -
Our forecast projects the market to reach roughly USD 316.6 Million by 2032, representing a compounded annual growth rate of 4.55% over the forecast period (2026–2032). That pace signals reliable, investible growth rather than speculative boom — ideal for firms preferring predictable, margin‑sensitive opportunities.
Strain Gage Market -
Market concentration metrics underscore the sector’s structure: the top three and top five players account for modest shares, indicating a fragmented supply landscape where differentiation, standards compliance, and service ecosystems matter as much as component cost.
What the PW Consulting report delivers (practical content)
-
Proprietary market model: annualized market sizing (2020–2025 historical), a 2026 base, and detailed forecasts to 2032 with sensitivity scenarios (low, base, high) tied to macro and sectoral variables.
-
Buy‑side playbook: procurement frameworks for volume buyers, total cost of ownership templates that include installation labor and certification overheads, and supplier evaluation scorecards.
-
Product and technology decision tools: a pragmatic matrix comparing foil, wire, and semiconductor strain gage technologies across criteria such as temperature range, long‑term drift, installation complexity, and digital integration readiness.
-
Regulatory and standards dossier: implications and compliance checklists for recent standards impacting geotechnical and infrastructure monitoring — essential for public‑sector tenders and large EPC contracts.
-
Go‑to‑market and service blueprints: recommendations for channel strategy, calibration and field service offerings, and bundled hardware + analytics licensing models for system integrators.
-
Risk register and mitigation playbooks: raw material exposure analysis, supplier continuity scenarios, logistics stress tests, and recommendations for hedging and second‑sourcing.
-
Vendor benchmarking and acquisition target profiles: strategic fit frameworks and value creation roadmaps for vertical or horizontal M&A.
Key trends shaping demand and competitive advantage
-
Standards and certification are becoming a growth lever. The adoption of updated strain measurement standards for geotechnical monitoring in late 2025 and their implementation by national bodies through 2026 are accelerating procurement of certified gauge solutions for infrastructure projects. Companies that can demonstrate compliance and provide audit‑ready documentation capture premium procurement windows.
-
Digital integration moves beyond DAQ: strain gages are increasingly sold as nodes in holistic structural health monitoring systems. The winners will be those who combine robust transducers with firmware standards, edge processing, and subscription analytics that turn raw strain into actionable alerts.
-
Installation labor and specialized skills are an underappreciated constraint. Installing gauges on advanced composites or in hostile environments requires certified technicians and specialized training. This dynamic creates recurring revenue opportunities for providers that offer training, installation services, and field verification packages.
-
Raw material dynamics are immaterial to most buyers today but critical for suppliers. The metallic foils at the heart of many conventional gauges — copper‑nickel and nickel‑chromium alloys — remain the cost anchors for traditional foil gage lines. Stable sourcing and materials substitution strategies will be central to margin preservation.
-
Fragmentation fuels both competitive pressure and niche specialization. With a relatively low share captured by the largest vendors, there is room for technology specialists, regional integrators, and value‑added service providers to thrive alongside global brands.
Competitive landscape — how to read it
Our vendor analysis profiles established manufacturers, specialist producers, and channel partners. Rather than enumerate share by product line, PW Consulting maps firms against four actionable dimensions: technology depth, product range, systems integration capability, and aftermarket/service sophistication.
-
Technology specialists with deep foil and semiconductor portfolios have the engineering credibility to serve experimental and high‑temperature use cases. These firms command premium pricing in R&D and aerospace segments where measurement precision and traceability are non‑negotiable.
-
Large diversified connectors and sensor conglomerates convert scale and channel reach into OEM wins, particularly in automotive and industrial transducer markets. Their advantage is speed to market and integration into established electro‑mechanical platforms.
-
Regional manufacturers and niche suppliers focus on installation‑intensive applications — weldable, waterproof, and high‑temperature bondable gauges — which are indispensable in civil engineering and geotechnical projects where field conditions demand specialty designs.
-
Distributors and systems integrators create commercial breadth by bundling sensors with data acquisition, calibration, and analytics. Their leverage is in customer relationships and aftermarket revenue, especially in long‑term monitoring contracts.
Examples of strategic postures we analyze in the full report include: a precision‑gauge specialist expanding services into calibration and training to improve margins; a global connector firm embedding strain gages into modular transducer platforms to capture OEM supply; and a regional instrumentation house positioning for public infrastructure contracts by investing in standards compliance and installation certification.
Recent developments you cannot ignore
-
Standards published in late 2025 and subsequent national adoption in 2026 have materially shifted specification language for geotechnical monitoring — this affects product acceptance and tender evaluation criteria.
-
Product launches and technical publications during 2026 highlight a market focus on packaged strain solutions and practitioner education — companies that move beyond discrete components toward systemized offerings will gain share.
-
Hands‑on training workshops held by specialist providers underline the market’s skills gap in installation and long‑term data quality management — a gap that service‑oriented vendors can monetize.
Strategic recommendations for 2026 decision‑makers
-
Prioritize compliance‑led product upgrades. Update product datasheets, test protocols, and traceability chains to align with the latest standards where you target infrastructure or public sector tenders.
-
Convert technical capability into service revenue. Invest in certified training programs, field calibration teams, and digital verification workflows to capture recurring revenue and increase switching costs.
-
Design product lines around systems, not parts. Bundle strain gages with interoperable electronics, firmware, and cloud analytics to move up the value chain and protect margins from commoditization.
-
De‑risk materials and capacity. Establish dual sourcing for key foil alloys and secure long‑lead inventory for specialty variants to avoid production disruptions during demand spikes.
-
Use targeted M&A to fill capability gaps. Look for bolt‑on acquisitions that add field service capability, regional distribution, or specialized gauge technologies that complement your existing portfolio.
-
Refine procurement with a TCO lens. For high‑volume buyers, weigh labor, calibration, and lifecycle replacement costs as heavily as unit price; contracts that embed training and installation support lower total cost and risk.
-
Segment go‑to‑market by buyer economics. Differentiate approaches for OEMs (volume, integration) versus infrastructure owners (standards, lifecycle monitoring) to tailor value propositions.
What you will find in the full report (and why you should read it)
-
Granular but actionable forecasting and scenario analysis that translates a 4.55% CAGR and the projected expansion to USD 316.6 Million by 2032 into addressable opportunity maps for specific buyer archetypes.
-
Operational playbooks for procurement, quality assurance, and field deployment that reduce installation failures and improve measurement fidelity — content developed from workshops and vendor practices across the industry.
-
Vendor scorecards and partnership maps that identify strategic partners and acquisition targets by capability rather than headline size — essential for fast followers and incumbent leaders alike.
-
Practical appendices covering materials, certification pathways, typical failure modes, and sample contractual language for service‑level agreements in structural monitoring projects.
PW Consulting’s Strain Gage Market study is intentionally designed as a decision‑quality toolkit for 2026. We provide the evidence base, the scenarios, and the operational templates — but we leave the precise segmentation tables and proprietary supplier valuations behind a gated layer to protect the commercial value of that intelligence. For procurement teams, R&D leaders, and corporate strategists who require the complete data set and downloadable models, please visit our report page to access the full dataset, supplier heatmaps, and our interactive scenario model.
For detailed analysis of this topic, please visit the official page: Strain Gage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


