



PW Consulting: X-Ray Security Scanner Market — 6.5% CAGR to USD 11.5B by 2032

X-Ray Security Scanner Market: Strategic Imperatives for 2026 Decision-Makers
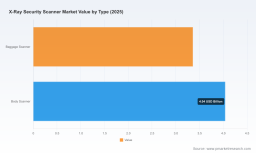
As organizations re-evaluate security postures and capital expenditure plans in 2026, the X-Ray security scanner sector is emerging from steady maturation into a phase of selective, high-value replacement and capability expansion. PW Consulting’s X-Ray Security Scanner Market study (base year 2025; forecast to 2032) quantifies that transition and translates it into concrete decision levers for procurement, operations, and technology strategy. The market is forecast to grow at a compound annual growth rate (CAGR) of about 6.5% from the 2025 base, expanding from a mid‑single‑digit billion USD market in 2025 toward roughly an eleven-plus billion USD market by 2032. This briefing highlights the strategic value of the research for 2026 plans while deliberately withholding the granular tables and segment-level figures reserved for the full report.
X-Ray Security Scanner Market
Why this research matters for 2026
-
Timing and scale: Organizations contemplating checkpoint and cargo screening investments in 2026 must reconcile near-term regulatory pressures with multi-year modernization timelines. Our market sizing shows a steady upward trajectory, signaling both continued replacement cycles and pockets of greenfield demand that can justify immediate procurement.
X-Ray Security Scanner Market -
Procurement lens: The study converts macro growth into procurement playbooks—when to accelerate purchases driven by regulation, when to delay for newer CT models, and when to consider retrofit or service-augmentation options that preserve capital.
X-Ray Security Scanner Market -
Risk-to-reward frame: With modest market concentration (CR3 and CR5 metrics indicating a broadly competitive supplier field), buyers gain negotiating leverage but must manage supplier reliability, certification timelines, and after-sales service risk—each addressed in the report’s supplier risk matrix.
Market snapshot (concise, decision-focused)
-
Base year context: The research uses 2025 as the analytical baseline. The market in 2025 sits comfortably in the single-digit billion USD range and is projected to expand to the low double-digit billion range by 2032 under the central scenario.
-
Growth tempo: A 6.5% CAGR through the forecast period reflects steady replacement cycles, technology refresh (notably CT and 3D imaging adoption), and growth in cargo and border screening use cases.
-
Concentration: Market concentration is modest; the top three and top five vendors together account for only a quarter or so of the market, indicating fragmented demand and opportunities for niche innovation and regional players.
Key dynamics shaping 2026 strategy
-
Regulation as a primary accelerant: New rules requiring volumetric imaging for heavier freight and related mandates are reshaping the upgrade road map of logistics hubs and airports. The report models the timing and regional velocity of regulatory-driven replacements so you can prioritize deployments.
-
Public funding cycles and procurement windows: Government allocations and programmatic buys (notably in aviation security) create multi‑year procurement windows. Our scenario work clarifies how to align supplier discussions and delivery schedules to avoid capacity bottlenecks.
-
Cost differentials by technology: Computed Tomography (CT) checkpoint machines command materially higher per‑unit pricing and total cost of ownership than legacy dual‑view tunnels—an economic reality that drives hybrid strategies (CT for high‑risk streams, tunnels for throughput-intensive lanes). The report provides TCO models that capture acquisition, maintenance, and throughput trade-offs.
-
Privacy and public acceptance: Privacy objections have curtailed some detection modalities, accelerating adoption of millimeter-wave alternatives in public venues. Our analysis maps social acceptance risks against technology choices for commercial and stadium operators.
-
Supply-chain and trade policy effects: Recent tariff shifts have prompted re-evaluation of sourcing strategies for pallet and container scanners. The research includes scenario-based supplier sourcing plans and mitigation steps for procurement leaders.
Competitive landscape — what to watch
The vendor map is diverse, with established defense and industrial players, specialized imaging firms, and growing niche innovators. The full report contains vendor scorecards, capability matrices, and procurement‑suitable shortlists. Below are high‑level profiles of vendors that consistently influence competitive dynamics and procurement outcomes.
-
Rapiscan Systems (United States) — Known for integrated baggage and vehicle inspection platforms and mobile threat detection capabilities. Recent order activity and product certifications signal continued demand for their mixed portfolio.
-
Smiths Detection (United Kingdom) — A long‑standing checkpoint and cargo X‑ray provider whose HI-SCAN and SDX families remain relevant to airport and freight screening modernization programs.
-
L3Harris Technologies (United States) — Brings defense-grade screening systems to aviation and security markets; strong systems integration capabilities make them a go‑to for complex deployments.
-
Nuctech Company Limited (China) — Competes across airports and cargo with high‑throughput systems; competitive pricing and broad product lines influence purchasing dynamics in multiple regions.
-
Gilardoni S.p.A. (Italy) — European supplier specializing in baggage and parcel x‑ray scanners with a focus on tailoring to commercial and postal screening needs.
-
3DX‑Ray (United Kingdom) — Niche player focused on portable and cabinet scanners, useful for specialized frontline and secondary inspection applications.
-
Analogic Corporation (United States) — Provides advanced imaging technology; their solutions are relevant where imaging fidelity and algorithmic processing matter most.
-
Leidos (United States) — Systems integrator with a broad security portfolio; useful in multi‑vendor, programmatic procurements requiring integration and managed services.
-
Astrophysics Inc. (United States) — U.S.-made scanners for mission‑critical infrastructure with an emphasis on robustness and serviceability.
-
VOTI Detection (Canada) — Offers 3D perspective imaging focused on borders and cargo screening where dimensional analysis and automated detection are mission‑critical.
Recent vendor developments in 2026 (orders and certifications) underline two important points: there is active procurement momentum across governments and logistics operators, and certification pathways remain a differentiator for market access. Procurement teams should verify certification roadmaps when evaluating suppliers.
What PW Consulting’s report delivers (operational and strategic tools)
-
Market sizing and validated forecast to 2032 with transparent methodology—useful for capital planning and board-level forecasting.
-
Procurement playbooks—when to buy, when to lease, and when to phase-in CT versus tunnel upgrades based on throughput, risk profile, and budget cadence.
-
Vendor scorecards and negotiation levers—technical and commercial criteria prioritized by deployment archetype (airport, cargo hub, border crossing, commercial venue).
-
TCO and ROI models—configurable worksheets that let you stress-test scenarios (e.g., increased freight volumes, accelerated regulatory compliance timelines, tariff shocks).
-
Regulatory and certification tracker—mapping of regional mandates and the certifications that unlock procurement funding and airport deployment windows.
-
Supply‑chain resilience playbook—practical steps to de‑risk sourcing and installation schedules, and to manage lead‑time volatility for critical sub‑assemblies.
-
Technology deep dives—comparative analysis of CT, dual‑view tunnels, millimeter‑wave, and 3D perspective systems, including algorithmic detection trends and integration pathways for AI‑based threat detection.
-
Case studies and buyer checklists—real deployments that show cost elements, timelines, stakeholder alignment, and operational outcomes.
How to use this research in 2026 decision cycles
-
Prioritize regulatory-driven upgrades: Use the report’s regulatory timing overlays to sequence purchases and avoid premium rush pricing during concentrated program buys.
-
Adopt hybrid technology strategies: Where throughput is paramount, balance CT investment with optimized tunnel deployments; the report’s TCO tools make these trade-offs explicit.
-
Design procurement windows around supplier capacity: Our vendor capacity mapping helps avoid delivery slippage and identify alternative suppliers that meet certification needs.
-
Manage lifecycle costs actively: Include maintenance, software upgrades, and training in multi‑year budgets—our scenario analysis quantifies the impact of different post‑warranty support models.
-
Build privacy and public engagement into rollouts: Anticipate social objections and include mitigation (privacy-enhanced modes, opt‑out options, communication plans) as part of deployment approval packages.
Next steps and how the full report helps
This briefing is intended as an executive preview that surfaces the strategic insights procurement and security leaders need to act in 2026. The full PW Consulting X-Ray Security Scanner Market report contains the granular segmentation tables, interactive dashboards, procurement-ready vendor shortlists, and downloadable financial models that operational teams will use to execute. To move from insight to action, stakeholders should pair the report’s scenario outputs with internal workload forecasts and certification requirements—and sequence procurements to align with both regulatory deadlines and supplier lead times.
For teams preparing 2026 procurement cycles, the report is specifically designed to: reduce decision uncertainty, shorten procurement evaluation time, and demonstrate the ROI of alternative deployment paths. Request access to the full dataset and the procurement playbooks to convert this market momentum into durable security capability upgrades.
For detailed analysis of this topic, please visit the official page: X-Ray Security Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


