



Full Body Scanner Market to Reach USD 745M by 2032, Growing at 9.8% CAGR - PW Consulting

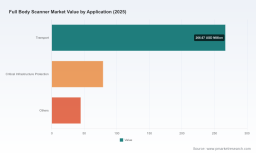
Full Body Scanner Market 2026: Strategic Preview for Decision-Makers
As organizations plan capital allocations and operational strategies for 2026, the Full Body Scanner market is moving from niche security investment to a scalable, programmatic procurement category. PW Consulting’s upcoming Full Body Scanner Market study — anchored on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon — synthesizes market forces, regulatory inflection points, vendor dynamics and deployment playbooks to inform board-level and procurement-level choices. At a macro level, the market has expanded from roughly USD 200 million in 2020 to about USD 390 million in 2025 and is forecast to grow to approximately USD 745 million by 2032, representing a compound annual growth rate of 9.8%. That trajectory creates a different strategic calculus for 2026 investments: this is planning for scale, not one-off pilots.
Full Body Scanner Market
Why this matters for 2026 decision cycles
-
Budgeting and multi-year procurement: The market’s near-term growth profile forces organizations to move from episodic buys to multi-year procurement frameworks that lock in price, support and upgrade paths.
Full Body Scanner Market -
Programization of security screening: Airports, mass-transit hubs and correctional systems increasingly treat full body scanners as program-level assets. That shifts procurement criteria toward lifecycle cost, throughput optimization and integration with existing security stacks.
Full Body Scanner Market -
Regulatory and certification risk: Certification timelines and government procurement windows will define winners in 2026—approved systems get accelerated deployment where standards or event-driven demand emerges.
Market dynamics and regulatory inflection points
Three dynamics are shaping near-term demand and vendor positioning: regulatory standardization, event-driven procurement, and technology convergence.
-
Regulatory standardization: Over the past two years regulatory bodies and authorities have clarified certification pathways and baseline performance expectations. Notable examples include updated checkpoint guidance from major aviation authorities in 2025 and multiple vendor certifications against pan-European standards in 2024–2025. For procurement teams, this reduces technical uncertainty but raises the bar for interoperability and compliance documentation.
-
Event-driven and sovereign demand: Major international events and geopolitical drivers create concentrated procurement windows. In 2026, several high-visibility contracts and deployments illustrate how event timetables and national security priorities accelerate adoption.
-
Technology and data integration: Advances in millimeter-wave imaging, AI-based object detection, and non-ionizing screening techniques are converging. Vendors that can fuse software-led detection with a defined hardware upgrade path will capture larger program contracts.
Technology posture: what matters to operators
For operators and security architects, technology choice is no longer purely a “type” decision. Procurement decisions hinge on a set of operational attributes:
-
Throughput and false alarm rates — affecting staffing and checkpoint design.
-
Safety and privacy profile — non-ionizing alternatives and anonymized detection outputs are increasingly mandatory in public deployments.
-
Integration and upgradeability — APIs, software update cadence and on-site service footprints determine lifecycle TCO.
-
Certification and interoperability — cleared systems attract accelerated deployment in certified environments such as aviation checkpoints.
These attributes explain why several suppliers have differentiated along both hardware and software axes, offering certified systems with AI-assisted detection, walk-through form factors and non-ionizing modalities that address throughput and privacy simultaneously.
Competitive landscape: fragmented but feature-led
The Full Body Scanner market is characterized by a relatively fragmented vendor base (industry concentration metrics indicate low top-three and top-five shares), which creates room for both incumbent defense/aviation suppliers and fast-follow specialized vendors. Competition is feature-led rather than purely price-led, with differentiation around certification status, throughput guarantees, fleet support and integration capabilities.
-
Smiths Detection (Hemel Hempstead, UK) positions itself around non-invasive transmission X-ray screening series designed to detect concealed objects. Their product set answers demands where penetration and material discrimination remain critical to threat detection strategies.
-
Rohde & Schwarz (Munich, Germany) has anchored a strong position in millimeter-wave walk-through systems with AI-assisted detection and full body coverage. Recent contract awards and certification milestones have reinforced their airport and high-capacity venue credentials.
-
Leidos (Reston, VA, USA) brings a high-throughput, non-ionizing people-screening solution with a software-first detection layer, appealing to large-scale checkpoint operators seeking throughput and low health-risk profiles.
Recent vendor developments that have immediate strategic implications for 2026 include multi-site contract awards and certification achievements that reduce deployment friction. These wins shift the procurement conversation from “prototyping” to “rollout,” and they create second-order effects on support ecosystems and aftermarket services.
Recent developments to watch (implications for procurement)
-
Certification progression for walk-through systems removed a barrier for continuous passenger flow screening in airports, opening high-throughput architectures for major terminals.
-
Updated checkpoint guidance from major aviation authorities has clarified hardware and data-handling expectations; procurement teams must align RFP language with these updated standards to avoid rework.
-
Legislative activity at state levels has broadened the addressable market for custodial and correctional security deployments, with pilot authorizations creating initial demand pockets.
-
Recent vendor contract awards tied to major events demonstrate that certified suppliers with demonstrated logistics and global support can capture accelerated, high-value deployments.
Strategic choices for 2026 — an operator playbook
For 2026, we recommend five concurrent actions for organizations that intend to operationalize full body scanning capability at scale:
-
Move from pilot to program procurement: shift contract structures to include multi-year service-level agreements, defined upgrade paths and performance-based incentives.
-
Prioritize certification-aligned products: require proof of certification in initial RFPs and contract clauses for maintaining compliance as standards evolve.
-
Design for integration: require vendor commitments for open APIs, cybersecurity attestations and third-party integration tests to lower long-term integration risk.
-
Model total cost of ownership, not unit price: include spares provisioning, software licensing, data storage, and field service in TCO models to avoid budget surprises.
-
Define staged rollouts linked to measurable KPIs: incremental performance and user-acceptance gates de-risk full rollouts and provide negotiation levers.
What PW Consulting’s full study delivers (actionable content)
The full PW Consulting report translates market dynamics into procurement-grade intelligence. Highlights of the deliverables include:
-
Market sizing and validated forecast models (2020–2032) with scenario sensitivity for event-driven surges and accelerated certification adoption.
-
Technology roadmaps and vendor capability matrices that compare detection modalities, throughput, privacy profiles and upgrade paths.
-
Regulatory compliance mapping and an acquisition checklist aligned to recent international standards and national guidance.
-
Vendor scorecards and procurement templates — RFP language, SLA clauses, maintenance schedules and service credits — to shorten procurement cycles.
-
Operational deployment playbooks — checkpoint redesign, staffing models, and KPI frameworks for first 24 months post-installation.
-
Commercial models — detailed TCO, financing options, and leasing vs. capital purchase comparisons tailored for operators and governments.
-
M&A and partnership radar — candidate profiles, capability gaps and investment theses for investors seeking consolidation plays in a fragmented market.
To honor the “trailer” principle: this preview demonstrates the depth and practical focus of our work while reserving the full tranche of sub-segmentation tables, region/application breakdowns, vendor scorecard weightings and model assumptions for the full report. Those deliverables contain the granular procurement levers and numeric appendices clients use directly in negotiations and CAPEX approvals.
Conclusion — strategic posture for 2026
Entering 2026, the Full Body Scanner market is at a pivot: certification clarity, feature convergence and strategic procurement windows are converging to make large-scale deployments a rational option for governments and commercial operators. The market’s sustained near-double-digit CAGR and forecasted expansion through 2032 mean that decisions made in 2026 — about vendors, contract structures, and integration blueprints — will lock in cost and capability implications for years.
PW Consulting’s full study equips procurement leaders, security program executives and investors with the forward-looking models, vendor benchmarking and playbooks needed to convert market opportunity into repeatable, secure deployments. For readers preparing procurement strategies, contract specifications, or investment memos for 2026, the full report is the operational manual you’ll reference in bid committees and boardrooms.
Access the complete report page for the full data appendices, segmentation tables and executable templates that power 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Full Body Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


