



PW Consulting: Health Products Market to Reach USD 7,153M by 2032, Growing at 6.8% CAGR

Health Products Market 2026: Strategic Outlook and Why This Report Is Mission-Critical for Executive Decision-Making
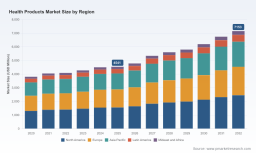
As PW Consulting’s Chief Industry Analyst, I present a focused briefing on the Health Products Market that synthesizes our quantitative modeling, primary research, and executable strategic guidance. The market we track — spanning consumer health formulations, personal care devices, wound care innovations and complementary medical products — has demonstrated steady expansion through 2020–2025 and is positioned for sustained growth across 2026–2032. Specifically, our base-year assessment pegs the global market at approximately USD 4,541 million in 2025, and our forecast model projects growth to about USD 7,153 million by 2032 at a compound annual growth rate (CAGR) of 6.8%.
Health Products Market
Why this report matters for 2026 strategic planning
-
Timing for investment and clinical development: 2026 is a transition year for regulatory strategy and capital allocation. With regulators signaling streamlined evidence pathways and an evolving reimbursement environment, companies must re-sequence clinical and commercial investments to capture accelerated routes to market while preserving payer access.
Health Products Market -
Portfolio prioritization under constrained budgets: The market’s mid-single-digit CAGR means incumbents and new entrants will compete for share growth through product differentiation, supply resilience, and channel optimization rather than pure market expansion. Our study translates market momentum into explicit investment levers — where to double down and where to de-risk.
Health Products Market -
M&A and partnership prioritization: Moderate market concentration (our concentration analysis shows that the top-three and top-five players together command a meaningful but not monopolistic share) creates opportunities for bolt-on acquisitions, specialty carve-outs, and strategic alliances. The report maps realistic acquisition corridors by capability, geography, and regulatory maturity.
What the report delivers — practical, transaction-ready intelligence
This is not a high-level brochure. The deliverable is built for corporate strategists, business development teams, and investment committees that need to execute in 2026. Highlights include:
-
Top-down market sizing and bottom-up forecast models spanning 2020–2032, with sensitivity cases reflecting alternative adoption curves and regulatory scenarios.
-
A validated competitive framework that benchmarks product portfolios, clinical status, manufacturing footprint, and go-to-market channels for the leading and emergent players.
-
Go-to-market playbooks for three archetypal entrants — incumbent CPG-extension, clinical-device innovator, and digitally enabled direct-to-consumer brand — including revenue ramp profiles and channel economics.
-
Transaction support materials: valuation multiples, precedent transactions, and an M&A scorecard that aligns target selection with integration risk and near-term revenue synergies.
-
Regulatory and reimbursement roadmaps that translate evolving policy drivers into milestone-based decision trees for clinical development, approvals, and coverage negotiations.
-
Supply chain stress-test scenarios that quantify cost, time-to-market, and margin impact from tariffs, supplier disruption, and reshoring initiatives.
-
A prioritized 18-month action plan for commercial teams and R&D leadership that converts market opportunity into KPI-linked initiatives and budget allocations.
How to use these findings in 2026 corporate decisions
-
Align clinical development to regulatory inflection points. The FDA’s movement toward allowing a single, rigorous pivotal study for many innovative health products shortens timelines but increases the importance of study design. Our report provides trial design guardrails that optimize statistical power while minimizing time and cash burn.
-
Reconfigure go-to-market cadence to capture early-adopter channels. With the market growing steadily, differentiated products win by converting premium early adopters and specialist channels before broader commercialization; the report identifies which channels offer the fastest payback for each product archetype.
-
Incorporate payer-impact scenarios into launch economics. Recent national-level agreements and Medicaid pricing dynamics are changing formulary and reimbursement negotiations. We translate these macro moves into concrete pricing and contracting strategies for 2026.
-
Hedge supply-chain and cost exposure proactively. Tariff escalations on certain imports have tangible effects on device components and packaging; our scenario modeling quantifies margin exposure and suggests low-cost, high-impact mitigation tactics, including dual-sourcing and near-shoring prioritization.
-
Prioritize M&A targets with integration playbooks. Given the market’s structure and concentration dynamics, targeted acquisitions can accelerate capability buildouts — our M&A templates rank targets by dilution risk, revenue accretion timing, and logistical complexity.
Competitive landscape — what to watch and what it implies
The competitive map is nuanced: established healthcare players, specialized device makers, and nimble personal health brands co-exist and compete on adjacent vectors — clinical evidence, supply chain reliability, regulatory agility, and channel relationships.
-
United Health Products, Inc. (United States): Focused on a novel hemostatic gauze product currently navigating a complex regulatory pathway. Recent regulatory developments — including a warning letter and an IDE decline in 2025 — highlighted compliance risk and study-design gaps, but a subsequent collaborative approval for a clinical program in 2026 signals a path forward. For competitors and investors, United Health’s trajectory is a reminder that clinical and regulatory execution materially changes commercial timing and valuation.
-
Solventum Corporation (United States): Positioned with personal health care and wound-care device offerings, Solventum exemplifies firms that bridge consumer and clinical markets. Their product set and channel approach illustrate how clinical credibility and consumer branding can be combined to capture higher-margin segments.
-
Bausch Health Companies Inc. (Canada): A diversified incumbent with pharmaceuticals, devices, and consumer health products. Its scale and portfolio breadth provide resilience but impose different strategic trade-offs compared with focused innovators. For smaller firms, Bausch is an archetypal strategic acquirer and distribution partner.
Our competitive benchmarking in the full report provides deeper profiles (capabilities heatmaps, regulatory maturity scores, IP posture) and a near-term horizon scan of likely strategic moves by these and other players.
Regulatory, supply chain and reimbursement forces shaping outcomes
-
Regulatory evolution: Agencies are experimenting with shorter evidence pathways that emphasize robust single pivotal studies for many devices and innovative health products. This reduces time-to-market but raises the stakes for trial design and post-market surveillance. Companies that align development plans to these expectations will shorten time to revenue and reduce capital risk.
-
Supply chain friction: Tariff actions and component bottlenecks are increasing variable costs and elongating lead times for certain device components. Our modeling quantifies the profit sensitivity to these inputs and provides a prioritized set of mitigation options that can be implemented within 6–12 months.
-
Reimbursement pressure and opportunity: High-level national payer negotiations and policy shifts are compressing prices in some channels while opening new contracting opportunities in others. The practical implication: launch plans must include early payer engagement and flexible contracting prototypes to protect ASPs and market access.
What we intentionally withhold — and why
In line with the “trailer” principle of this briefing, we demonstrate analytical rigor and strategic insight while deliberately withholding tabulated subsegment numbers, granular regional share tables, and proprietary unit economics that are included only in the full report. Those datasets — which combine primary interviews, invoice-level trade data, and PW’s proprietary market model — are required to run bespoke scenario analyses and to validate transaction assumptions. Access to the full dataset and downloadable models is available through our report portal.
Next steps and recommended executive actions for 2026
-
Initiate a 90-day clinical-regulatory sprint to stress-test trial designs against the single-study pathway and define go/no-go milestones tied to investor and board approvals.
-
Run a tariff and supplier concentration audit to identify components representing >X% (confidential benchmarking available in the report) of BOM risk, and implement dual-sourcing or near-shore pilots for the top two risk nodes.
-
Engage PW Consulting for a tailored M&A target short-list and integration roadmaps if inorganic growth is under consideration; our live models will convert valuation assumptions into accretion/dilution scenarios.
-
Adopt an early-payer engagement protocol for any product with clinical claims beyond general wellness; we provide contracting templates and KPI-driven pilots in the full report.
Final thought
The Health Products Market in 2026 is neither a wide-open frontier nor a mature, slow-growth sector. It is a selectively expanding ecosystem where regulatory inflection, supply-chain reconfiguration, and payer dynamics will determine winners. Our study equips leadership teams with the forecasts, scenario tools, and tactical playbooks needed to make high-conviction decisions this year. For the granular segmentation data, downloadable financial models, and company-level benchmarking that underpin these conclusions, please consult the full PW Consulting Health Products Market report.
For detailed analysis of this topic, please visit the official page: Health Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


