



PW Consulting: Cybersecurity Market Set for 13.8% CAGR, Strategic Insights Ahead

Cyber Security Market 2026: Strategic Imperatives for Enterprise Leadership
As organizations finalize their 2026 technology and security budgets, the Cyber Security market is no longer a defensive line-item — it is a strategic lever. PW Consulting’s latest market research, with a 2025 base year and a forecast horizon to 2032, documents a sustained, high-growth market driven by cloud transformation, AI adoption, regulatory pressure and a rising investment tide from public and private sectors. From an estimated market size of roughly USD 115 million in 2020, the sector expanded to approximately USD 219 million by 2025 and is forecast to surpass USD 540 million by 2032, growing at a compound annual growth rate of 13.8% over the forecast period. These headline dynamics frame a 2026 planning environment where choices about platform bets, talent investments, and procurement models will determine competitive position for the next decade.
Cyber Security Market
Why 2026 Is a Watershed Year
-
Policy acceleration: In early 2026, significant public sector moves — including the largest-ever Intelligence Community cybersecurity investment, a White House executive order establishing an AI cybersecurity clearinghouse, and multiple federal and state grant programs for schools, libraries and local governments — are reshaping funding flows and procurement priorities. These initiatives are unlocking near-term demand and creating new compliance baselines that enterprises must accommodate.
Cyber Security Market -
Technology inflection: AI-based detection and response, cloud-native access and Zero Trust architectures have shifted from experimental to mainstream. Vendors are rapidly integrating AI into detection, deception and automation layers, while buyers grapple with how to operationalize those capabilities safely and effectively.
Cyber Security Market -
Operational constraints: Chronic skill shortages, fragmented regulation, and limited visibility across IT/OT/IoT estates remain primary barriers to achieving cyber resilience. These constraints mean that capital alone will not buy security — the architecture and operational choices made in 2026 will be decisive.
Market Trajectory and Strategic Implications
The market’s historical trajectory and forward forecast illustrate two actionable realities for corporate leaders. First, growth is broad-based and accelerating: what was a mid-hundreds million marketplace in the early 2020s is entering an era of sustained expansion, driven by aggregated demand across enterprise IT modernization, cloud migration, supply-chain security and critical-infrastructure protection. Second, market concentration metrics indicate a balance between scale and specialization: a modest portion of demand is captured by leading global platforms, but nearly half the market remains accessible to focused specialists and regional players. Practically, this means enterprises will continue to see a dual landscape of large, integrated platform providers and best-of-breed specialists — and their procurement choices should reflect that mix.
Key Strategic Themes for 2026
-
AI-enabled defense, with human-in-the-loop governance: AI accelerates detection and automation but introduces new attack surfaces and governance complexity. For 2026, organizations should prioritize controlled pilots of AI-driven security functions, paired with clear model governance and incident-validation workflows.
-
Zero Trust as an operational program, not a project: Zero Trust investments must be sequenced against business-critical data flows and user populations. Adopt incremental, risk-prioritized implementations that produce measurable reduction in lateral-movement risk within 12–18 months.
-
Data resilience and ransomware preparedness: Backup and recovery — and the ability to validate data integrity quickly — have moved from insurance to strategic advantage. Investments in immutable storage, air-gapped verification, and tested recovery playbooks should be mandatory line items in 2026 CapEx planning.
-
Identity and privileged access as the new perimeter: Privileged Access Management and identity-centric controls are central to reducing attack surface. Prioritize identity risk quantification and integration of PAM into broader access governance.
-
Cloud-native security and developer-first tooling: As software supply chain attacks intensify, security needs to shift left — developer-integrated SCA, IaC scanning and runtime protections must be part of the CI/CD discipline.
-
Managed services and automation to overcome talent gaps: The industry-wide shortage of skilled cyber practitioners makes managed detection, response and co-managed models attractive. Combine managed services with automation to extend scarce senior analyst capacity.
Competitive Dynamics: How Leaders and Challengers Are Positioning
The competitive landscape is characterized by a mix of platform consolidation, targeted specialization, and rapid product evolution. Leading vendors have followed complementary strategies: some are integrating broad stacks to offer unified SASE, cloud and endpoint coverage; others double down on identity, data resilience or developer-first security.
-
Palo Alto Networks and Fortinet continue to emphasize platform integration, bundling network security, cloud controls and enforcement planes into cohesive stacks intended for enterprises seeking consolidation.
-
CrowdStrike and similar endpoint-native players position AI-driven prevention and detection as core differentiators for stopping modern attacks at initial entry points.
-
Zscaler and Cloudflare are illustrating the cloud-native path to secure access, endorsing a Zero Trust exchange model that minimizes on-premise appliances.
-
CyberArk emphasizes privileged access and identity controls, a category that remains essential for protecting critical systems and meeting stringent compliance mandates.
-
Specialists like Snyk and Rubrik target developer and data resilience vectors respectively — illustrating the continued role of best-of-breed tools within enterprise stacks.
-
Defense and systems integrators are also active; companies with national-security pedigrees are focusing on critical-infrastructure and government workflows where regulatory and assurance requirements drive vendor selection.
Market concentration indicators show that while the largest three firms capture a meaningful share of demand, the top five do not dominate the market to the exclusion of specialists. This distribution creates opportunities for targeted consolidation, alliance strategies, and differentiated product plays.
What the PW Consulting Report Delivers (Practical, Not Theoretical)
Our research translates market observation into operational decision tools for 2026 planning. The full report includes:
- An executive playbook that maps risks to prioritized investment levers over 12–36 months.
- Vendor scorecards and positioning matrices that evaluate platform fit by enterprise archetype.
- A procurement and integration checklist for composable security stacks, with recommended SLA and telemetry minimums.
- CapEx vs Opex modelling templates tailored to cloud-first, hybrid and regulated-industry scenarios.
- M&A and partnership heat maps identifying attractive targets by capability and commercial fit.
- Scenario analyses that quantify exposure under common adversary playbooks and regulatory shock events.
- Regulatory alignment guidance that synthesizes multiple federal and state requirements into practical control priorities for compliance teams.
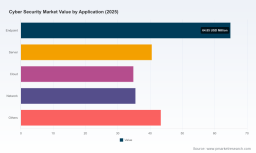
Note: This article intentionally summarizes themes and outcomes. Core segment-level tables, regional and application splits, and vendor revenue shares are omitted here to encourage direct access to the primary research package where those granular data and model files can be downloaded.
How to Use This Research for 2026 Decision-Making
-
Translate growth expectations into capability roadmaps: Use the market growth trajectory to justify investments in automation, testing and recovery capabilities that will scale with your organization’s footprint over the next three budget cycles.
-
Prioritize outcomes over products: Define measurable resilience outcomes (e.g., mean time to detect/respond, recovery time objectives for critical datasets) and use them to score procurement options rather than feature checklists.
-
Leverage public funding windows: Align grant and procurement teams with program timelines emerging from federal and state announcements in 2026; these windows can subsidize modernization for education, local government and critical infrastructure operators.
-
Adopt hybrid delivery models: Combine managed services with internal rotations and automation to address the workforce shortage while retaining strategic oversight of key controls.
-
Build secure-by-design developer practices: Integrate SCA, IaC scanning and runtime protection into CI/CD pipelines as non-negotiable gates to production deployment.
Closing: What Leaders Must Decide Now
2026 presents both opportunity and obligation: public investment and regulatory attention will create demand and compliance complexity in equal measure. The market’s robust growth, underpinned by a mid-teens CAGR and rising public-sector spend, rewards decisive architecture and operating-model choices. Leaders who treat cybersecurity as an enterprise-level strategic program — aligning investment, talent and procurement to measurable resilience outcomes — will convert today’s defensive spend into tomorrow’s business enabler.
PW Consulting’s full Cyber Security Market report provides the granular data, vendor benchmarking, and executable templates necessary to operationalize these insights. This briefing outlines the strategic contours; the report contains the calibrated inputs and segment intelligence you will need to finalize your 2026 security roadmap.
For detailed analysis of this topic, please visit the official page: Cyber Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


