



Isobornyl Acrylate Market to Reach USD 664.26M by 2032 at 7.52% CAGR | PW Consulting

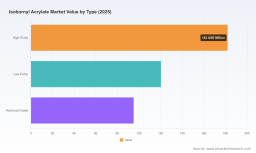
Isobornyl Acrylate Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused preview of our new Isobornyl Acrylate market study — designed specifically to inform commercial, procurement, R&D, and M&A decisions in 2026. This briefing outlines the strategic value of the research, summarizes the operative insights contained in the full report, and highlights the competitive and structural dynamics that will determine winners and losers across the value chain. Per our “trailer” principle, the narrative below demonstrates analytical depth while intentionally omitting granular segment tables and proprietary figures — those are reserved for the full report.
Isobornyl Acrylate Market
Market trajectory at a glance
Isobornyl Acrylate (IBOA) has moved beyond niche specialty status to become a mid-sized, commercially significant monomer class. Between 2020 and 2025 the market expanded materially — from roughly USD 287 million to about USD 397 million — driven by accelerating adoption in UV/EB curing formulations, electronics encapsulants, and high-performance coatings. As of our base year (2025) the market momentum points into a multiyear growth phase: our modeled forecast projects the market to reach approximately USD 664 million by 2032, corresponding to a compound annual growth rate (CAGR) of 7.52% over the 2026–2032 horizon. The first actionable decision year — 2026 — therefore sits at an important inflection where short-term operational choices will determine strategic optionality for the remainder of the forecast.
Isobornyl Acrylate Market
Why this research matters for 2026 decisions
- Prioritize capital allocation with clarity: With mid-single-digit to high-single-digit CAGR and a clear pathway to near-doubling by 2032, investments in capacity, quality upgrades (high-purity grades), and downstream formulation support can generate differentiated returns. The report quantifies payback windows across alternative capex scenarios and provides sensitivity to raw-material price volatility.
- De-risk supply chains: The IBOA value chain sits downstream of acrylic acid and camphene feedstocks. Our analysis maps supplier concentration, feedstock exposure, and build versus buy trade-offs — enabling procurement teams to craft hedging, inventory, and dual-sourcing strategies for 2026 that preserve margin and continuity.
- Shape product strategy for sustainability demand: Regulatory and customer pressure is accelerating demand for lower-carbon and bio-derived monomers. We show how early adoption of bio-based variants and validated replacement pathways (including trade-offs in chemistry and cost) can open routes to premium pricing and preferred supplier status.
- Inform M&A and partnership bets: With a market that is moderately concentrated at the top, there is meaningful opportunity for scale-driven consolidation and bolt-on acquisitions. The report includes an M&A decision framework tailored to 2026 valuations and integration risks.
What the full report contains — practical, decision-ready assets
- Executive decision memo: concise action recommendations for CEOs, Heads of Supply Chain, and Head of R&D, clearly mapped to 6-, 12-, and 24-month time horizons.
- Market forecast model: interactive scenario outputs covering 2026–2032 with base, high-growth, and downside scenarios; sensitivities to feedstock cost, regulatory shifts, and substitution risks.
- Go-to-market playbooks: tailored templates for incumbent producers, new entrants, and downstream formulators — including pricing levers, quality positioning (high-purity vs. technical grades), and channel strategies.
- Supply-side diagnostics: supplier scorecards, capacity maps, and stress-test matrices for potential disruptions (feedstock shortages, regulatory changes, site outages).
- Competitive intelligence annex: comparative profiles and strategic positioning analysis of the leading suppliers, recent product launches, capacity investments, and likely next moves.
- Commercial tools: TCO calculators for sourcing decisions, sample contract clauses to protect against feedstock swings, and an integration checklist for acquisitions.
Competitive landscape — who matters and why
The market exhibits a moderate degree of top-end concentration, with the largest three suppliers accounting for nearly half of industry shipments and the top five capturing a substantial majority. That structure has three strategic implications: pricing power attached to specialty capabilities, room for regional players to defend niches, and transaction-driven consolidation possibilities.
Isobornyl Acrylate Market
- Evonik Industries (Essen, Germany) — Evonik’s VISIOMER® IBOA has been positioned as a high-performance monomer for emulsion and solution polymerization. Their recent capacity expansion in Europe (~18% increase in specialty acrylates in 2023) signals a readiness to serve higher-volume downstream partners and to defend premium segments where consistency and logistics matter.
- Sartomer (Arkema Group, USA) — A market leader in reactive diluents and UV-curable systems, Sartomer’s 2024 launch of a bio-based IBOA variant is a strategic hedge against regulatory and customer-driven sustainability demands. This move demonstrates how product-innovation can be both a risk mitigation and differentiation lever.
- IGM Resins (Belgium) — As a systems supplier integrating IBOA into UV-curing formulations, IGM’s advantage is verticalized know-how: selling a system rather than a monomer, which increases switching costs for customers and reduces price sensitivity.
- Japanese and Chinese producers (e.g., Osaka Organic, Mitsui Chemicals, Anhui Royal, Hubei Ipure) — These firms operate across a spectrum from high-purity specialty to industrial-scale supply. Their strategic playbooks differ: some compete on cost and scale for industrial downstreams, others on stringent quality certification for electronics and optics.
- Specialty distributors (e.g., Kowa American, Silver Fern Chemical, TCI) — Distribution and formulation support remain critical for market reach, especially in regions where manufacturers lack direct sales coverage. Distributors also provide valuable market feedback and speed-to-market for new variants.
Collectively, these players make for a market where technical differentiation (purity, regulatory compliance, low-odour, compatibility with photoinitiators) is as important as scale. Our competitive annex grades firms on technology, route-to-market, capacity flexibility, and sustainability roadmaps — allowing buyers and investors to prioritize shortlists for partnerships or M&A.
Key dynamics and risk vectors
- Feedstock exposure and cost volatility: IBOA synthesis relies on upstream petrochemical inputs (notably acrylic acid and camphene intermediates). Volatility in crude oil and refining intermediates therefore transmits directly into raw-material cost and margin pressure. Our stress scenarios model the impact of persistent high feedstock prices on supplier economics and downstream pass-through feasibility.
- Regulatory and sustainability drivers: Regulations limiting VOCs, or incentivizing bio-derived monomers, are reshaping formulation choices in coatings and adhesives. Sartomer’s bio-based IBOA launch exemplifies how regulatory pressure accelerates product innovation. The report maps potential regulatory timelines and compliance costs across major markets.
- Technology substitution and application evolution: Advances in photoinitiators, reactive diluents, and alternative acrylates could change demand composition among purity grades and application types. We model substitution elasticity and identify product features most resistant to displacement.
- Concentration and bargaining dynamics: With near half of the market in the hands of three firms and the top five controlling an even larger share, buyers that are overly dependent on a small set of suppliers face negotiation asymmetries. The report recommends contractual and operational tactics to restore balance.
How to use this research in 2026 — recommended next steps
- Procurement — Implement the supplier stress-test toolkit and renegotiate supply agreements with clearer pass-through clauses and defined escalation mechanisms for feedstock shocks.
- R&D and product teams — Prioritize piloting bio-based and hybrid formulations; use our compatibility matrices to shorten validation cycles for UV/EB curing customers.
- Corporate development — Use our M&A scorecards to evaluate targets that add either capacity, high-purity specialty chemistry, or route-to-market synergies; focus on targets that offer immediate cost synergies and near-term revenue uplift.
- Strategy and finance — Re-run the provided forecast model under your internal cost-of-capital assumptions to validate or adjust planned investment horizons and to stress-test ROI under alternative regulatory outcomes.
Final note — what you will find in the full report
The complete PW Consulting Isobornyl Acrylate market study provides the granular diagnostics and proprietary data tables that are essential for transaction diligence, procurement contracts, and technical product roadmaps. That includes the full regional and application split analyses, supplier-by-supplier market share details, detailed pricing curves, and all model inputs and sensitivities. We have deliberately kept those granular figures out of this preview to ensure your team engages with the full toolkit when making binding decisions.
For executives preparing 2026 budgets and strategic plans, this research converts market growth and structural dynamics into executable actions — from capex prioritization and supplier strategy to product innovation and deal-making. To access the full dataset, scenario model, and supplier dossiers, contact the PW Consulting Market Intelligence team or visit the report landing page for immediate download.
For detailed analysis of this topic, please visit the official page: Isobornyl Acrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


