



Timing Controllers Market to Expand at 6.98% CAGR — PW Consulting Insight

Timing Controllers Market: Strategic Briefing for 2026 Decision‑Makers
Executive overview
As companies finalize product roadmaps and supply‑chain commitments for 2026, timing controllers (TCONs) occupy a quietly pivotal position in display value chains. PW Consulting’s latest Timing Controllers Market study synthesizes five years of historical performance (2020–2025) with an actionable seven‑year forecast (2026–2032). The headline picture is straightforward: after rising from USD 163.15 Million in 2020 to USD 215.0 Million in 2025, the market is projected to expand to USD 344.8 Million by 2032, driven by a compound annual growth rate (CAGR) of roughly 6.98% across the forecast horizon.
Timing Controllers Market
Why this study matters for 2026 strategy
- Timing controllers are small components in absolute dollar terms but exert outsized influence on display performance, system power budgets, and feature enablement (HDR, adaptive sync, integrated touch, and advanced color mapping). Decisions about TCON selection cascade into panel vendor choice, SoC interface design, and BOM cost/weight.
- 2026 is a junction year. Technology inflections (ePaper signage scaling, TTED integrations for notebooks, and automotive grade displays) intersect with macro pressures—commodity inflation, extended semiconductor lead times, and tougher export compliance—forcing firms to trade off cost, time‑to‑market, and regulatory risk in new ways.
- Our report is designed for C‑suite and product leadership who must translate component‑level dynamics into portfolio priorities, supplier strategies, and M&A or partnership roadmaps for the next 12–36 months.
Market dynamics shaping 2026 decisions
Several structural forces are simultaneously sharpening demand and tightening execution risks:
Timing Controllers Market
- Technology convergence. Integration trends—Touch with TCON Embedded Driver (TTED), on‑chip HDR/tone mapping, and low‑voltage logic—mean TCONs now carry feature burdens that used to sit in separate ICs or in panel firmware. This raises the technical bar for suppliers and increases switching costs for OEMs.
- End‑market diversification. Consumer electronics continues to represent the bulk of demand, but adjacent pockets—automotive HMI, signage (including large‑format ePaper), and industrial displays—are maturing into reliable growth contributors. For system architects, this means stricter AEC‑Q validation paths and extended life‑cycle requirements for certain SKUs.
- Supply volatility. Raw material cycles (notably copper and other key inputs for electronic assemblies) and a surge in component lead times—single‑month increases of the kind seen early in 2026—are elevating inventory carrying costs and procurement complexity. Firms that lock flexible supply arrangements or dual‑sourcing plans will preserve launch windows.
- Regulatory headwinds. Newer export controls and regional licensing regimes are increasing the compliance burden for semiconductor procurement and cross‑border R&D collaboration. These constraints are concentrated along dual‑use flows, affecting both sourcing and potential design partnerships.
Competitive landscape — what to watch
The TCON sector remains fragmented; no single supplier dominates, and market shares cluster in the mid‑double digits for the largest groups. Our vendor intelligence highlights a mix of fabless specialists, legacy SoC vendors, and integrated panel suppliers—each with distinct strengths and risks:
Timing Controllers Market
- Himax Technologies, Inc. (Tainan, Taiwan) — Known for targeted TCON ASICs and recent product adoption into large‑format color ePaper platforms. Himax is playing to the signage/ePaper niche where display control and color management are differentiating factors.
- Texas Instruments Incorporated (Dallas, USA) — A broad analog and mixed‑signal portfolio gives TI advantages in cross‑domain systems (TVs, automotive HUDs, industrial panels) where interoperability and long product life cycles matter.
- Novatek Microelectronics Corp. (Hsinchu, Taiwan) — Strong in embedded TCON products that support high‑resolution panels with advanced features such as HDR and adaptive sync, an attractive profile for OEMs targeting premium displays.
- Parade Technologies, Ltd. (San Jose, USA) — A leading proponent of TTED (Touch with TCON Embedded Driver) single‑chip solutions for notebooks and embedded displays; recent production ramps for mainstream notebook resolutions signal improved availability for OEMs.
- Samsung Electronics Co., Ltd. (Suwon, South Korea) — As a panel and system supplier, Samsung’s DDI and TCON work emphasizes energy efficiency and tight panel integration—useful where power budgets or thermal constraints are critical.
- Analogix Semiconductor, Silicon Works, Raydium, Focal Tech, THine, MegaChips — These mid‑tier and regional specialists supply differentiation either through performance (high refresh/gaming), automotive readiness, or cost‑optimized solutions for high‑volume consumer segments.
Recent product and adoption milestones reinforce where momentum lies: in June 2026 a T2000 Color ePaper timing controller was adopted into a large‑format color ePaper signage platform, and earlier in February 2026, Parade announced production availability for two single‑chip TTED devices aimed at mainstream notebooks. Such developments create immediate sourcing opportunities but also competitive pressure to move from pilot to production quickly.
Strategic implications and recommended actions for 2026
Translate market trajectory and vendor dynamics into three practical action tiers:
- Immediate (0–6 months)
- Freeze critical‑path supplier engagements for launches planned in 2026. Prioritize suppliers with demonstrated production availability and clear compliance postures for export controls.
- Run scenario stress tests on BOMs to quantify cost exposure from raw material price spikes and elongated lead times; identify components where redesign (e.g., pin‑compatible alternative drivers) yields material schedule relief.
- Establish conditional volume commitments with at least two qualified TCON vendors for flagship programs to mitigate single‑source disruptions.
- Near term (6–18 months)
- Refine product roadmaps to exploit integrated TCON features—TTED for notebooks, built‑in tone mapping for gaming/4K displays, and low‑voltage TCONs for battery‑sensitive devices. Prioritize firmware architectures that decouple panel logic from application SoCs to preserve platform flexibility.
- Negotiate supply contracts with clauses for lead‑time relief, price‑adjustment bands tied to raw material indices, and compliance‑assurance warranties to manage regulatory risk.
- Start strategic partnerships or minority investments in specialists (ePaper, automotive TCON specialists) where the in‑house roadmap requires fast feature adoption without internal R&D latency.
- Strategic (18–36 months)
- Lock long‑term co‑development agreements for next‑generation display subsystems where differentiation depends on tight integration between panel, TCON and driver ASIC (e.g., automotive HUD with low latency and high reliability).
- Evaluate M&A targets among mid‑tier TCON vendors to acquire IP (tone mapping, low‑voltage logic) and to secure alternative fabrication paths for critical displays.
- Design multi‑region supply networks aligned to likely regulatory paths, segregating development, production, and qualification flows to reduce compliance friction.
What the PW Consulting report delivers
This study is built to move teams from high‑level awareness to executable plans. Key practical contents include:
- Validated historical market sizing (2020–2025) and a transparent forecast model (2026–2032) with scenario toggles to simulate commodity shocks, lead‑time variances, and regulatory impacts.
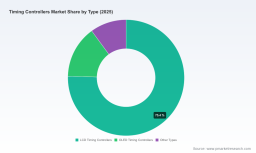
- Segmented demand analysis (by region, by type, by application) and a downloadable model that lets you test portfolio exposures—note: the executive brief intentionally omits detailed segment tables; full segmented datasets and vendor scorecards are available in the full report package.
- Comprehensive vendor dossiers including technical differentiators, qualification maturity, commercial posture, and forward‑looking product pipelines—useful for sourcing, R&D alliances, and procurement negotiations.
- Supply‑chain playbook and procurement templates: sample contract language, dual‑sourcing plans, and inventory hedging approaches aligned to timing controller specifics.
- Investment and M&A screening matrices tailored to corporate strategy—criteria-weighted shortlists for bolt‑on targets and strategic JV partners in display subsystems.
Final thoughts — positioning for 2026
TCONs are emblematic of a broader market truth: small components with specialized functions can quickly become system‑level choke points when technology evolution and macro pressures collide. The market’s steady growth—backed by a near‑7% CAGR across the forecast period—creates attractive opportunities for firms that can move decisively on supplier selection, product integration, and regulatory planning.
PW Consulting’s Timing Controllers Market study is built to be a practical strategic tool: it gives you the numbers to justify investments, the vendor intelligence to de‑risk sourcing, and the playbook to convert component‑level insight into program wins. For teams making 2026 commitments, the decisive advantage will be the ability to translate component forecasts into contractual certainty and technical roadmaps. The full report contains the granular segmentation data, downloadable models, and vendor scorecards that will enable that translation.
Call to action
Access the full report and the interactive forecast model on our website to review the complete segmentation tables, vendor scorecards, and downloadable procurement templates. Use these resources to stress‑test your 2026 display programs and to prepare an executable supplier strategy that balances cost, compliance, and feature velocity.
For detailed analysis of this topic, please visit the official page: Timing Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


