



PW Consulting: Die Cut Lids Market to Reach USD 308.1M by 2032 at 6.5% CAGR

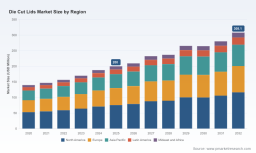
Die Cut Lids Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting presents an executive introduction to our latest Die Cut Lids Market study, designed to equip CEOs, commercial leaders, product engineers, and M&A teams with the context and judgment needed to make high‑stakes decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the full report while preserving proprietary segmentation and scenario outputs that are available in the complete deliverable.
Die Cut Lids Market
Market snapshot — what the headline numbers tell you
Across the 2020–2025 historical window the die cut lids market expanded steadily, and in our base year (2025) the market is assessed on an industry standard USD Million revenue basis. Looking forward through our forecast horizon (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 6.5%, reflecting a mix of volume gains and value migration toward premium and sustainable lidding solutions. By the end of the forecast horizon the market is expected to be materially larger than in 2025 — a trajectory that underpins investment cases for product innovation, capacity expansion, and targeted consolidation.
Die Cut Lids Market
Market concentration is meaningful but not absolute: the top three firms account for roughly half of global revenue, and the top five capture close to two‑thirds of the market. This structure creates a distinctive competitive landscape where global players set standards and regional or specialist firms can still capture niche leadership through technical differentiation or customer intimacy.
Die Cut Lids Market
Why this outlook matters for 2026 strategic decisions
- Resource allocation: the steady mid‑single‑digit CAGR supports disciplined CAPEX for capacity modernization, but requires a strong ROI case focused on material efficiency, waste reduction, or higher‑margin specialty products.
- Portfolio prioritization: product lines and R&D roadmaps should be stress‑tested for regulatory resilience and recycled‑content pathways; packaging teams must align to evolving recycled content accounting frameworks.
- M&A and partnerships: the moderating concentration means acquisitions can deliver meaningful market share and capability uplift, particularly when they add regulatory know‑how or sustainable material technology rather than only volume.
Key dynamics shaping 2026 playbooks
- Regulatory and extended producer responsibility (EPR) pressure.
U.S. state‑level rules and new laws are expanding obligations on recycled content, mass balance accounting, and end‑of‑life management. Notably, California’s recent expansion of recycled content and mass balance requirements imposes new compliance and supply‑chain reporting burdens for packaging makers and brand owners. Parallel initiatives and EPR programs elsewhere raise potential fee exposure and create incentives to accelerate recycled or compostable lid solutions.
- Raw material cost volatility.
Pulp, paper and specialty packaging paper prices demonstrated upward pressure through 2025 and into 2026; macro price indices for processed papers and PPI measures point to tighter input cost dynamics. For players with paper‑based lidding exposure, EBITDA sensitivity to pulp and paper swings is nontrivial and should inform hedging, supplier diversification, and product substitution choices.
- Material and manufacturing innovation.
Product launches and printing advances have pushed the performance envelope for aluminum, multi‑layer laminates and thin‑gauge offerings. Recent examples from major converters illustrate how design and print capabilities can convert commodity lidding into brand‑impacting touchpoints while reducing material intensity.
- Customer expectations and foodservice dynamics.
Demand for convenience, peelability, extended shelf life, and on‑pack communication (QR codes, tamper evidence) is shifting specifications. Private label growth and out‑of‑home channel dynamics also influence run lengths and customization requirements.
- Supply chain resilience and nearshoring.
Logistics costs, lead‑time concerns and regulatory divergence are motivating some buyers to shorten supply chains or dual‑source, which creates openings for regional converters with strong service models.
Competitive landscape — how leading companies are positioning
The market is populated by global converters and specialized regional players. The following themes summarize competitive positioning among the core companies profiled in our study:
- Full‑spectrum converters with global reach (e.g., Amcor, Berry Global, Sonoco, Huhtamaki):
These firms leverage broad material portfolios, integrated supply chains and deep customer relationships to offer multi‑material lidding solutions. Their playbook emphasizes cross‑sell into existing container platforms, global quality systems, and scale‑led pricing power.
- Technology and sustainability specialists (e.g., Constantia Flexibles):
Product innovation — thin‑gauge aluminum, high‑definition prints, and eco‑optimised peel lids — is used to capture premium segments and secure preferred supplier status with sustainability‑focused brands. Recent launches set a market standard for thin aluminum die cut lids and advanced printability.
- Custom and barrier specialists (e.g., ProAmpac, Momar Industries, Oliver Healthcare Packaging):
These players differentiate through tailored lamination, barrier technologies, and healthcare‑grade peels. They command higher margins in regulated or technically demanding subsegments where specifications and traceability matter.
- Regional converters and service innovators (e.g., Barger Packaging, Winpak, Uflex, Watershed Packaging, Barger Packaging):
These firms exploit proximity to customers, agility in short runs and the ability to co‑develop SKUs for local private label or regional food manufacturers.
Recent competitive developments — including new ultra‑thin aluminum lid launches and advances in aluminium printing — reflect a market where design innovation and material substitution are visible routes to market share and margin expansion. Simultaneously, evolving regulation in 2025–2026 increases the value of compliance capability as a competitive moat.
What the full report delivers — practical components for execution
Our full Die Cut Lids Market report is organized to move leaders from insight to action. Highlights include:
- Transparent methodology and base‑case market sizing (historical 2020–2025; base year 2025; forecast 2026–2032).
- Segmented scenario models with sensitivity to raw material price shocks, recycled content mandates, and adoption of thin‑gauge metal solutions.
- Competitive benchmarking that maps capability clusters (printing, barrier, sustainability, healthcare) and an acquisition target shortlist by capability gap.
- Regulatory impact matrix summarizing obligations, reporting timelines and expected compliance costs across major jurisdictions.
- Commercial playbooks: go‑to‑market templates for converters, brand owner negotiation levers, and SKU rationalization frameworks to improve factory efficiency.
- Procurement and supplier‑risk toolkit, including margin simulations, contract term recommendations and a supplier scorecard for recycled content traceability.
To support rapid decision cycles, the report includes downloadable financial models and a one‑page CEO brief with prioritized strategic moves for 2026.
Recommended strategic moves for 2026 (prioritized)
- Immediate (0–6 months):
Audit recycled content claims and readiness for mass balance accounting; implement short‑term supplier diversification to mitigate pulp/paper cost spikes; pilot printed aluminum panels for premium SKUs.
- Near term (6–18 months):
Invest in lightweighting pilots and barrier lamination trials that lower per‑unit material use; negotiate EPR pass‑through mechanisms with brand customers; pursue bolt‑on acquisitions that add sustainability or healthcare lidding capabilities.
- Medium term (18–36 months):
Scale proven thin‑gauge technologies, build mass‑balance accounting systems end‑to‑end, and redesign supply contracts to reward circular‑material adoption.
Final perspective — how PW Consulting helps
For 2026, companies that align product strategy to regulatory pathways, secure flexible raw‑material sourcing, and convert innovation into verifiable sustainability credentials will outcompete peers. Our Die Cut Lids Market study provides the quantitative foundations, competitive intelligence and executable playbooks to make those choices with confidence. The introduction above surfaces our analytical approach and strategic implications; the full report contains the segment breakouts, scenario tables and proprietary benchmarking data needed to operationalize these recommendations.
Access the complete study to retrieve the detailed segmentation, interactive models and supplier scorecards that are intentionally withheld from this preview. PW Consulting stands ready to translate those insights into a bespoke strategic plan, scenario testing, or M&A advisory tailored to your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Die Cut Lids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


