



PW Consulting: Carbon Block Market at USD 215M in 2025; 6.98% CAGR to 2032

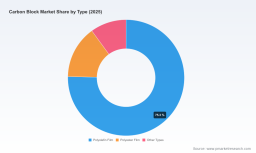
Carbon Block Market 2026 Preview: Strategic Imperatives for Commercial Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive Carbon Block Market research (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). This briefing is designed as a strategic “teaser”: it surfaces the evidence-based trends and decision frameworks corporate leaders must consider in 2026, while reserving the proprietary, high-resolution datasets and granular segment breakouts for the full report.
Carbon Block Market
Why this market matters in 2026
The carbon block market has moved from a niche filtration input to a core enabler of water quality, regulatory compliance, and differentiated end-user experiences across residential, commercial and industrial water-treatment systems. Our modeled topline shows steady expansion — the market scaled materially through the early 2020s and, following a compound annual growth trajectory of approximately 6.98% across the forecast window, is projected to reach a materially larger run rate by 2032. That pace reflects a convergence of regulatory tightening, end-user sensitivity to water safety post-pandemic, and accelerating demand for point-of-entry and point-of-use filtration.
Carbon Block Market
For executives planning capital allocation, product roadmaps, or M&A in 2026, this is not a discretionary supply-chain item; it is a strategically meaningful category with predictable growth drivers and identifiable chokepoints in raw materials and certification pathways.
Carbon Block Market
What the research delivers (practical, action-oriented)
- High-confidence market sizing and forecast model (base 2025), with scenario variants that stress raw material shocks, accelerated certification timelines, and faster-than-expected adoption in commercial/institutional channels.
- Supply-chain diagnostics: upstream feedstock dynamics, machine and tooling capacity, key OEMs and production models, and realistic lead-time sensitivities for capacity build-out.
- Regulatory and reimbursement playbook: where NSF/ANSI certifications unlock market access and which incentive programs materially affect payback periods for point-of-entry systems.
- Competitive scorecards and capability maps: strategic positioning, go-to-market archetypes, and likely avenues for consolidation or vertical integration.
- Commercial levers: pricing elasticity, bundling strategies for POU/POE systems, aftermarket subscription models, and commercial channel optimization.
- Execution templates for 90–180 day pilots and 12–24 month strategic initiatives—designed to shorten time-to-impact for product and commercial teams.
Market structure and concentration — what it means
The carbon block market is characterized by a low-to-moderate concentration profile: a small group of established vendors hold meaningful engineering and certification advantages, but a large number of regional and contract manufacturers compete on cost and customization. This fragmentation creates tactical opportunities for nimble entrants to win share through superior certification, targeted channel partnerships, and differentiated raw material claims (e.g., coconut-shell activated carbon). For incumbent industrial players, the implication is clear: scale alone will not guarantee margin resilience without either premium differentiation or operational integration into upstream feedstock and extrusion technology.
Supply-side dynamics: raw materials, machine builders, and certification
Three supply-side themes are shaping strategic choices in 2026.
- Feedstock selection is a structural determinant of product performance and cost. Coconut-shell activated carbon continues to command preference for filter cartridges due to its hardness, low ash and microporosity profile. Firms that secure long-term, traceable supply agreements for coconut-shell carbon will have a defensible quality advantage for NSF/ANSI-focused product lines.
- Equipment and process capability matter. Access to reliable extruder technology and turnkey production lines — including CTO carbon block extruders and downstream finishing — shortens time-to-market. Suppliers of production machinery are effective leverage points for OEMs aiming to scale rapidly without incurring excessive capex risk.
- Certification is a gatekeeper. NSF/ANSI 42 and 53 remain mandatory checkpoints for residential and commercial products; obtaining and maintaining these certifications both reduces commercial friction and supports participation in rebate programs and institutional procurement.
Demand-side dynamics: drivers and commercialization opportunities
Demand is being pulled by multiple, reinforcing forces:
- Regulatory tightening and procurement standards in public and commercial buildings increase the baseline technical requirements for filters.
- End-user sensitivity to water contaminants—amplified by pandemic-era health consciousness—has driven above-trend adoption of point-of-entry (POE) and enhanced point-of-use (POU) filtration solutions.
- Rebate and incentive programs can materially shift payback timelines for smart filtration systems when coupled with energy-efficiency and public-health initiatives.
Commercially, this translates to clear plays: develop NSF/ANSI-certified premium product lines for institutional buyers; pair hardware with subscription-based cartridge replacement services; and design channel-specific SKUs for OEM partners that require high-volume, certified supply.
Competitive landscape — capabilities that matter in 2026
The competitive field includes vertically integrated OEMs, specialized producers, and equipment manufacturers. Leading players show patterns of specialization that inform tactical responses:
- OEM specialists with extensive extrusion capability and high-volume custom programs have advantages in scale manufacturing and bespoke product development for large OEM customers.
- Established producers with broad NSF-certified portfolios command trust in regulated commercial and residential channels; these firms can leverage brand recognition in whole-house and POU categories.
- Machine builders and process suppliers enable fast capacity expansion for aspiring producers; partnerships with these vendors de-risk new-line launches.
Executives should assess potential partners and acquisition targets not just on revenue or unit volumes but on certification pedigree, raw-material sourcing contracts, and tolerance for recurring aftermarket service models.
Recent signals and adjacent-market noise — how to read them
Industry events and adjacent-market developments in late 2025 and early 2026 provide leading indicators:
- Conferences focused on carbon technologies and circularity highlight investment appetite in advanced carbon materials and reclamation approaches—useful context for firms exploring recycled carbon inputs or circular cartridge programs.
- Capacity expansions and new material launches in the broader carbon value chain signal potential competition for feedstock and shifting input costs; not all developments are directly substitutable for activated carbon used in filtration, but they influence upstream pricing and availability.
- Regional trade shows and product showcases continue to be fertile ground for new product intelligence and distribution partnerships, especially in high-growth APAC markets.
2026 strategic playbook — five high-impact actions
For decision-makers executing in 2026, prioritize the following:
- Secure certification early. Allocate budget and timeline for NSF/ANSI 42/53 testing as a non-negotiable gate to premium channels; certification opens rebate eligibility and institutional procurement. Consider partnering with labs that specialize in filtration testing to shorten iteration cycles.
- Lock feedstock via forward contracts or integrated sourcing. Target coconut-shell activated carbon suppliers or invest in upstream relationships to stabilize product quality and margins.
- Evaluate manufacturing options through a total-cost lens. Compare CAPEX for in-house extrusion capacity against strategic partnerships with machine builders and contract manufacturers; include flexibility for SKU customization and rapid scale-up in your decision matrix.
- Monetize recurring revenue. Design replacement-cartridge subscription offers with clear lifecycle economics; demonstrate value through measured contaminant-removal metrics and rebate integration to improve customer payback.
- Use M&A and strategic alliances selectively. Prioritize targets with certification credentials, distribution reach in priority channels, or proprietary extrusion/process know-how rather than purely volume-based targets.
What the full report contains that you won’t find here
This preview intentionally omits the granular regional and application splits, full vendor scorecards, SKU-level pricing trajectories, and our detailed scenario-model spreadsheets. The complete Carbon Block Market report includes:
- High-resolution datasets by region, type, and application (historical and forecast) with downloadable models.
- Vendor benchmarking across product portfolio, certification status, manufacturing footprint, and aftermarket capabilities.
- Detailed supply-chain maps, machine-supplier directories, and contactable feeds for rapid sourcing.
- Execution guides with sample project plans, capex templates, and commercial pilot checklists.
If your 2026 strategy requires executable intelligence—capex prioritization, M&A screening, or commercial go-to-market design—this granular material is the difference between a plausible plan and a high-probability winner.
Closing: what to do next
In 2026, carbon block filtration is both a growth market and a risk-managed domain where certification, raw-material security, and manufacturing flexibility determine winners. Firms that act on the five high-impact moves above will materially shorten time-to-value and improve return profiles on product and distribution investments.
PW Consulting is ready to walk your leadership team through a focused strategic workshop that maps your capabilities to the market scenarios captured in our forecast. For access to the full datasets, vendor scorecards, and tailored strategic roadmaps, consult the source report and our advisory services.
For detailed analysis of this topic, please visit the official page: Carbon Block Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


