



PW Consulting: Sodium Silicate Market from USD 8,080M (2025) to USD 10,323M by 2032 at 3.7% CAGR

Sodium Silicate Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive teaser
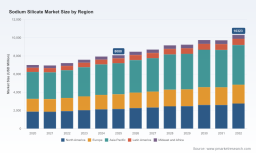
As companies rewire portfolios for resilience and margin recovery, sodium silicate is re-emerging as a quietly strategic commodity. Our PW Consulting market study, anchored on a 2025 base year, shows the global sodium silicate market at approximately USD 8,080 Million in 2025 and projecting forward at a steady compound annual growth rate (CAGR) of 3.7% through the 2026–2032 forecast window. By 2026 the market is modeled to expand to roughly USD 8,466 Million, progressing toward just over USD 10,300 Million by 2032. For executives making capital, sourcing or M&A decisions in 2026, that trajectory—modest but consistent—creates a set of practical choices about where to deploy resources and where to preserve optionality.
Sodium Silicate Market
Why this report matters for 2026 strategy
- Translate mid-single-digit CAGR into actionable capacity and pricing decisions—knowing not only the headline growth but the sensitivity to feedstock and logistics will change investment timing.
- Prioritize product segments and geographies: the right mix of liquid vs. solid grades, and targeted specialty chemistries, materially affects margin and risk exposure.
- Calibrate M&A appetites: consolidation metrics in this market create both platform targets and bolt-on opportunities for specialty or regional market entry.
- Align sustainability roadmaps with regulatory exposure: compliance costs and decarbonization pathways will drive operating cost differentials across producers, especially in high‑regulation regions.
Signals and near‑term dynamics that will shape 2026 outcomes
Three interlinked dynamics will determine near‑term winners and losers:
Sodium Silicate Market
- Feedstock and input volatility. Sodium silicate production depends on silica sand and soda ash; volatility in these inputs flows directly to cash costs and pricing power. Market monitoring shows regional price moves that are already compressing or expanding margins. For example, observed price points in Northeast Asia rose from about USD 0.53/kg in January 2025 to USD 0.55/kg in January 2026, while North American benchmark pricing moved from roughly USD 0.43/kg to USD 0.48/kg over the same interval—an early indicator of regional margin pressure tied to shipping, operating expenses and sector demand composition.
- Regulatory and compliance pressure. Tighter environmental regulations and emissions standards in Europe are raising operational expense baselines for producers. Companies unable to translate compliance into price or efficiency advantages will face margin erosion.
- Demand mix and end‑market health. Water treatment, detergents, construction, and pulp & paper remain core demand drivers, but growth differs by end‑use and region. Shifts in detergent formulation trends, municipal water capex cycles, and construction activity are the proximate demand levers to watch in 2026.
Market structure and competitive context
The sodium silicate market combines global integrators and strong regional specialists. Market concentration is material but not dominating—the top three players account for a majority share, and the top five widen that majority further. This structure produces predictable strategic behaviors: global producers compete on scale and feedstock integration; specialty chemical players compete on product differentiation and technical service; regional manufacturers compete on cost, logistics and tailored service models.
Sodium Silicate Market
Profiling the competitive set: strategic takeaways
- PQ Corporation (Malvern, Pennsylvania). A leading global producer with active capacity expansions in the US, Indonesia and Europe. PQ’s footprint and scale give it the flexibility to optimize feedstock sourcing and to pursue export or localized service strategies depending on regional margin profiles. For PQ, the strategic imperative in 2026 is to convert capacity additions into higher‑value specialty grades while locking in feedstock and logistics agreements to defend margins.
- Nippon Chemical Industrial Co., Ltd. (Japan). A strong manufacturer and exporter with deep channels into detergents and construction. The company’s export orientation and solution selling into detergents position it to capitalize on Asia‑Pacific demand resilience, but exposure to raw material swings will necessitate more aggressive hedging or supplier partnerships.
- Tokuyama Corporation (Japan). Focused on high‑purity and specialty silicates, Tokuyama’s value proposition is technical differentiation. In 2026 the premium plays—specialty grades, controlled particle distributions, and tailored chemistries—will see better margin expansion than commodity blends.
- Ankit Silicate (Morbi, Gujarat, India). An ISO‑certified regional manufacturer of liquid, powder and metasilicates for detergents, ceramics and construction. Local cost advantages and certification credentials make Ankit well positioned to serve domestic and neighboring markets; its strategic moves should prioritize capacity flexibility and product customization.
- Evonik Industries AG (Essen, Germany). Evonik’s integration of sodium silicate offerings with specialty silica and broader chemical portfolios creates cross‑sell and margin‑capture opportunities. For Evonik, the key strategic choices in 2026 are around bundling specialty chemistries, advancing sustainability claims and capturing value higher up the application ladder.
- Qemetica (CIECH Group subsidiary, Poland). As one of Europe’s largest silicate suppliers, Qemetica must manage regulatory cost pressure while exploiting scale into continental supply chains. Strategic options include differentiated technical service, localized decarbonization investments and selective export strategies.
Strategic playbook: what to do in 2026
For corporate leaders, the playbook centers on three parallel tracks: protect margin, grow selectively, and derisk the supply base.
- Protect margin: renegotiate long‑term feedstock contracts with escalation clauses tied to transparent indices; increase efficiency in energy use and emissions control to blunt regulatory cost increases; selectively shift product mix toward higher‑margin specialty grades.
- Grow selectively: prioritize investments where forecasted end‑market growth outpaces the headline CAGR—these are often specialty or application niches rather than broad commodity capacity. Use flexible capacity and tolling agreements to capture upside without committing to large fixed costs.
- Diversify risks: pursue multi‑sourcing for silica sand and soda ash, build inventory and logistics hedges for cost spikes, and consider JVs for market entry where localized service confers advantages.
What the PW Consulting report delivers (practical contents)
Designed as a pragmatic decision toolkit for 2026, the full study includes:
- Comprehensive market sizing and demand models: historical 2020–2025 and probabilistic forecasts for 2026–2032, with scenario variants tied to feedstock and macro assumptions.
- Price and cost sensitivity models: forward price scenarios for sodium silicate and the primary feedstocks, plus margin simulations under different pass‑through and regulatory regimes.
- Competitive dashboards: capability maps, capacity expansion trackers, and strategic positioning for global and regional producers.
- End‑use and application intelligence: qualitative and quantitative demand drivers for detergents, water treatment, pulp & paper, construction and other segments—presented in an actionable format that supports product and go‑to‑market prioritization.
- Supply chain and operational playbooks: sourcing strategies, logistics optimization, and operating models to lower cost and improve resilience in the face of input volatility.
- Regulatory impact and decarbonization pathways: region‑specific compliance cost estimates and practical investment options to reduce emissions intensity.
- M&A and partnership screening: target scouting criteria, valuation ranges, and integration playbooks for buyers and sellers.
- Risk heatmaps and mitigation templates: tailored to executive decision timelines (0–12 months, 12–36 months, 36+ months).
How to use this intelligence in 2026—practical decision triggers
- If your top‑line exposure to detergents or water treatment exceeds internal thresholds, accelerate product development and technical service investments now—these segments reward differentiation.
- If feedstock cost escalation reaches regional breakpoints (as already observed in North America and Northeast Asia), implement contractual pass‑through mechanisms and explore vertical integrations or tolling arrangements.
- For companies with limited sustainability credentials entering Europe, treat emissions compliance as a near‑term capital expense and model worst‑case regulatory scenarios in investment approvals.
- Use M&A as a scale/portfolio play: acquire complementary specialty capabilities or regional platform positions rather than chasing raw capacity alone.
Final provocation—why this is a “must‑have” for 2026 decisions
Sodium silicate will not be a headline growth miracle over the next seven years, but it will be a quietly consequential chemical: small percentage shifts in price, regulation or application mix translate into meaningful P&L swings for producers and users alike. The 3.7% CAGR through 2032 frames a market that is predictable at an aggregate level but richly variegated at the segment level—exactly the type of environment where superior intelligence and execution deliver outsized returns.
The full PW Consulting study contains the granular maps, sensitivity models and regional/application splits that corporate development, procurement and plant operations teams need to convert strategic intent into fiscal outcomes. This article is a trailer: it shows the contours and the strategic implications, while the downloadable report supplies the numbers, dashboards and scenario tools that power boardroom decisions in 2026.
Contact PW Consulting to access the full market model, supplier scorecards and investment playbooks that enable confident action in the sodium silicate value chain.
For detailed analysis of this topic, please visit the official page: Sodium Silicate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


