



PW Consulting: HFPO Market to Hit USD 4.19B by 2032 at 7.3% CAGR

Strategic Outlook: Hexafluoropropylene Oxide (HFPO) Market to 2032 — What 2026 Decision‑Makers Need to Know
Executive preview
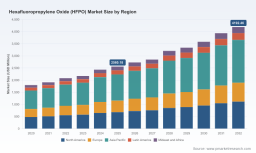
As PW Consulting’s lead industry analyst, I present a concise, decision‑centric view of the Hexafluoropropylene Oxide (HFPO) market intended to inform strategic planning for 2026. HFPO remains a linchpin intermediate for high‑value fluoropolymers, specialty coatings, and selected pharmaceutical and agrochemical syntheses. After a measured recovery and re‑rating between 2020 and 2025, the global HFPO market enters a multi‑year growth phase: our base‑year modeling (2025) finds the market at roughly USD 2.56 billion, and under our central case the market expands at a compound annual growth rate of 7.3% through 2032, reaching just over USD 4.19 billion by the end of the forecast horizon.
Hexafluoropropylene Oxide (HFPO) Market
Why this analysis matters for 2026
Two planning cycles intersect in 2026: near‑term operational choices (sourcing contracts, contamination controls, price hedges) and medium‑term strategic moves (capacity investments, product diversification, M&A). Action taken in 2026 will lock organizations into pathways that either capture the upside of the forecasted expansion or leave them exposed to regulatory and input‑price shocks. This briefing synthesizes the signals that should drive boardroom deliberations in 2026 while deliberately reserving the granular segmentation outputs for the full report.
Hexafluoropropylene Oxide (HFPO) Market
Market dynamics shaping 2026 choices
-
Demand composition and growth vector — HFPO demand is anchored to fluoropolymers (durable, high‑performance resins), with secondary but fast‑growing demand from specialty pharmaceutical and agrochemical intermediates. These end‑markets are sensitive to downstream capital cycles (semiconductor and electronics capex) and regulatory speed on PFAS‑related compounds. The combined effect supports sustained double‑digit pockets of growth even as the broader HFPO market grows at a mid‑single‑digit to high‑single‑digit rate overall (7.3% CAGR in our central scenario).
Hexafluoropropylene Oxide (HFPO) Market -
Upstream cost pressure — Fluorspar and hydrofluoric acid remain critical feedstocks. Industry price monitoring recorded material upward pressure in late 2025 amid constrained Chinese export volumes and firm HF acid demand. Procurement teams must treat feedstock volatility as a first‑order risk when modeling unit economics and negotiating multi‑year contracts.
-
Regulatory and reputational risk — Regulatory frameworks on PFAS derivatives have crystallized in some jurisdictions and remain fluid in others. Notably, U.S. federal drinking‑water rules have established enforceable maximum contaminant levels for HFPO‑derived species, while subsequent administrative actions indicate potential re‑evaluation of enforcement pathways. At the corporate level, operators have already invested in emissions and process‑control technology (for example, demonstrated high‑efficiency thermal oxidation installations at leading facilities). Expect incremental compliance costs and capital projects to increase operating breakevens across the supply chain.
-
Supply structure and concentration — The HFPO market is oligopolistic by design: the top suppliers capture a substantial share of global capacity. This concentration creates signaling power on pricing and technology adoption, while also creating opportunities for new entrants that can differentiate on regulatory compliance, specialty grades, or proximity to growing demand clusters.
Competitive landscape — positioning and strategic implications
Our corporate review highlights several archetypes among active HFPO producers:
-
Scale and integrated producer (e.g., Chemours) — Large, vertically integrated producers retain the advantage of feedstock integration, scale economics, and established global offtake relationships across fluoropolymers and specialty chemicals. These players also lead on environmental controls and transparency, having invested in demonstrated emissions abatement at major facilities. For customers and investors, tier‑one producers offer supply security but will likely price in the cost of compliance and decarbonization.
-
Regional specialists (European and Japanese incumbents) — Firms with deep technical expertise and proximity to high‑value industrial end‑markets emphasize product quality, specialty grades, and technical service. Their strategic playbook is to capture premium margins through tailored offerings for electronics and pharmaceutical customers.
-
Chinese producers and capacity scalers — A cluster of active Chinese manufacturers are expanding capacity and pursuing export channels. These producers compete on cost and increasingly on product purity and environmental performance. Their growth compresses regional margins and accelerates supply‑chain shifts for price‑sensitive buyers.
-
Technology‑differentiated players — A minority of suppliers focus on differentiated HFPO derivatives, higher‑purity streams, or greener process variants. These players are attractive partners for specialty formulators and advanced materials OEMs that value technical collaboration and supply security over lowest cost.
For 2026, buyers and sellers should evaluate counterparties not only on price and capacity, but on documented emissions abatement performance, feedstock security, and the ability to comply with evolving PFAS and drinking‑water standards. The presence of capacity leaders capable of producing tens of thousands of metric tons annually creates both stability and systemic risk, depending on operational reliability and regulatory exposure.
What the full report delivers (practical contents)
PW Consulting’s HFPO market study is structured to support actionable decisions. Key deliverables include:
- Proprietary demand model (2020–2032) with scenarios that isolate semiconductor/electronics capex cycles, pharmaceutical volume ramp, and alternative formulation uptake.
- Supply‑side capacity map and near‑term operational risk register identifying where disruption or compliance investments could re‑allocate volumes.
- Cost and price modeling including feedstock pass‑through sensitivity, delivered price ladders by trade lane, and margin break‑even tables for common contract tenors.
- Regulatory impact matrix that quantifies likely compliance capex, litigation exposure bands, and reputational risk multipliers under alternative policy outcomes.
- Supplier benchmarking with capability heatmaps (purity grades, scale, environmental controls, geographic reach) and a tactical procurement playbook for 12–36 month sourcing negotiations.
- Strategic M&A & JV heatmap identifying the most accretive combinations, and a valuation primer under conservative and aggressive growth cases.
- Operational checklists for site emissions control, stakeholder engagement guidance, and a phased implementation roadmap to align capital projects with regulatory timelines.
Note: to preserve the integrity of our commercial research model and to follow the “trailer” principle of this preview, granular regional and application‑level splits, as well as our downloadable Excel forecast by grade and region, are accessible in the full report and the interactive dashboards on our platform.
Actionable recommendations for 2026 planning
-
Procurement & contracting: Secure blended contracts that include indexation to feedstock and step‑in rights for alternate supply. Prioritize counterparty audits on emissions control and monitoring; insist on contractual covenants around disclosure and remediation funding in case of regulatory escalation.
-
Capex timing and volume commitments: Defer irreversible greenfield investments until clear regulatory pathways stabilize, unless your project includes demonstrable best‑in‑class emissions controls. Consider modular or brownfield expansions with lower capital intensity and faster payback as transitional plays.
-
Portfolio & product strategy: Accelerate development of higher‑purity and specialty HFPO derivatives where margin expansion is justified and compliance risks are lower. For commodity HFPO, prioritize scale and secure feedstock supply.
-
M&A and partnerships: Target bolt‑on assets that enhance technical capability (purity grades, derivative chemistry), environmental compliance credentials, or proximity to critical end markets. Use earn‑outs to mitigate regulatory tail‑risk.
-
Regulatory preparedness: Invest in monitoring, community engagement, and third‑party verification programs now. Demonstrable performance will materially affect permitting timelines, offtake negotiations, and insurance pricing.
-
Scenario planning: Run downside stress tests that combine a supply‑side shock (e.g., a major plant offline) with a regulatory tightening scenario. Determine liquidity buffers and contingency sourcing strategies for each stress level.
Data points you should anchor to (high‑level)
Anchoring the planning process to robust macro numbers removes speculation. Use the 2025 market base and the 7.3% CAGR in your investment hurdle analyses and scenario models. These anchors illustrate the difference between operational decisions that target market share (volume) versus those that optimize margin (specialty or regulated‑compliant offerings).
Closing: the strategic choice for 2026
2026 is less about predicting a single outcome and more about choosing a resilient pathway. Firms that align procurement, compliance, and innovation investments to the structural growth implied by the market trajectory — while preserving optionality against regulatory uncertainty — will convert the HFPO expansion into durable competitive advantage. PW Consulting’s full HFPO research package provides the detailed segmentation, supplier scorecards, and downloadable models necessary to operationalize these recommendations; the preview above is intended to clarify the strategic questions you must answer in 2026 and to demonstrate the practical, data‑driven tools we provide to answer them.
For the full segmentation, interactive dashboards, and the practitioner‑grade Excel forecast, please consult our complete report and data portal (access details available through PW Consulting’s market research page).
For detailed analysis of this topic, please visit the official page: Hexafluoropropylene Oxide (HFPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


