



PW Consulting: SBS Market to Reach USD 10.93B by 2032

Styrene Butadiene Styrene (SBS) Market — Strategic Outlook for 2026 Decision Makers
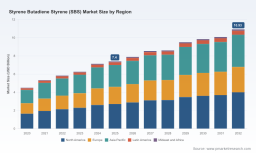
As companies prepare strategy for 2026, understanding the mid-cycle dynamics of the Styrene Butadiene Styrene (SBS) market is no longer optional. PW Consulting’s latest market brief — grounded on a 2025 base year and a seven-year forecast horizon — frames the SBS market as a resilient, growth-oriented industry. Our topline market model projects a recovery and sustained expansion from a 2025 market size of USD 7.4 Billion to a projected market above USD 10.9 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.8% during the forecast window. This trajectory underscores both the structural demand for SBS-based solutions and the strategic inflection points that buyers, producers and investors must navigate in 2026.
Styrene Butadiene Styrene (SBS) Market
Why this research matters for 2026 strategic choices
-
Timing investment and capacity: With the industry moving from post-pandemic volatility toward normalized demand growth, 2026 will be a pivotal year for capacity optimization — determining whether to expand, retrofit, or pursue offtake agreements. Our report quantifies the macro growth runway and models near-term supply-demand balances under multiple scenarios.
Styrene Butadiene Styrene (SBS) Market -
Pricing and margin resilience: Feedstock and logistics cost swings have introduced fresh pressure on margins. Our analysis provides a shortlist of actionable levers — from raw material pass‑through strategies to contract design and hedging practices — that materially affect EBITDA sensitivity in the coming 12–18 months.
Styrene Butadiene Styrene (SBS) Market -
M&A and vertical integration playbook: The market’s competitive topology and pockets of concentration create windows for bolt-on and vertical integration deals. The report maps buyer archetypes, valuation drivers, and integration pitfalls calibrated to 2026 market multiples.
-
Regulatory and trade risk management: Recent trade actions and evolving sustainability expectations mean commercial teams must embed regulatory scenarios into pricing and sourcing decisions. We translate these dynamics into probability-adjusted P&L impacts for 2026 strategy sessions.
Current dynamics shaping the SBS market
-
Feedstock volatility and cost pass-through: Styrene and butadiene feedstocks have shown elevated price volatility. Producers who secure backward integration, stable long-term sourcing, or flexible pass-through clauses will preserve margin flexibility. The report includes sensitivity analysis showing how raw material swings flow through to producer margins under alternative contractual frameworks.
-
Upstream capacity shifts: The industry has seen sizeable new entrants and expansions in recent periods, altering regional flows of material and competitive intensity. For procurement and commercial teams this necessitates revisiting sourcing zones and lead-time assumptions; our supply-mapping tool highlights likely bottlenecks and surplus corridors.
-
Logistics and energy-driven surcharges: Rising energy and freight cost profiles are increasing landed cost variability, particularly for long-haul shipments. The research models realistic landed-cost bands for different commercial strategies (e.g., spot purchases vs. long-term contracts with freight clauses).
-
Trade measures and compliance risk: Anti-dumping rulings and import duties in key markets have re-routed trade flows and raised transaction costs. Our regulatory risk module provides scenario-driven outcomes and mitigation playbooks for sellers and buyers exposed to international sourcing.
-
Sustainability credentials as a commercial differentiator: Certification achievements and low-carbon feedstock programs are moving from “nice-to-have” to table stakes for large buyers. Producers who can credibly demonstrate sustainable sourcing and certified supply chains command a pricing premium in strategic segments; our benchmarking shows which certifications meaningfully move commercial conversations.
Competitive landscape — what leading players are doing
The market’s top-tier manufacturers combine legacy assets, product breadth and technical service capabilities. While competition is material, the landscape remains open to strategic repositioning by ambitious mid-sized players and new integrated entrants.
-
Kraton Corporation (The Woodlands, Texas): A global leader in specialty polymers, Kraton’s portfolio spans SBS block copolymers tailored for thermoplastic elastomers, adhesives, sealants and modified bitumen. In late‑stage cycles Kraton has demonstrated commercial agility — from pricing actions to sustainability certification progress — which has direct implications for competitors’ pricing strategies and contract terms.
-
LCY Chemical Corp. (Taipei): LCY competes with a focus on styrenic block copolymers and engineered TPEs. Its portfolio orientation towards adhesives and performance materials positions it as a nimble supplier for regional formulators prioritizing product performance and technical support.
-
Kumho Petrochemical (Seoul): Known for its linear and radial SBS grades designed for high tensile performance, Kumho’s strengths lie in differentiated product quality for demanding applications such as modified bitumen and specialty adhesives.
-
LG Chem (Seoul): As an integrated chemical and materials firm, LG Chem leverages scale and downstream applications (e.g., waterproofing membranes and thermoplastic elastomers) to pursue strategic partnerships with OEMs and construction-materials groups.
-
TSRC Corporation (Kaohsiung): A longstanding SBS and SIS supplier, TSRC’s technical depth in block copolymers supports its position among formulators seeking product consistency and localized supply in Asia.
-
Asahi Kasei (Tokyo): With a broad performance-materials portfolio, Asahi Kasei competes on innovation and service-led engagements for elastomers and modified bitumen markets.
-
Dynasol Group (Madrid): Dynasol’s solution copolymers and SBS offerings aim at adhesives, sealants and TPE markets, and its strategic playbook centers on niche application engineering and flexible supply arrangements.
Together, established players control a meaningful share of global volumes — roughly two-fifths for the top three and approaching half when the top five are combined — which shapes pricing dynamics, contract structures and the pace of capacity additions. For challenger firms, the path to scale rests on specialization, partnership-driven downstream integration, or geographic arbitrage.
Recent commercial signals
-
Producers have announced industry-wide price adjustments reflecting raw material cost pressures — a signal that cost pass-through remains an active negotiation point between suppliers and buyers.
-
Large-scale capacity projects have come online in multiple regions, intensifying supply-side competition in targeted product grades and exerting short‑term pressure on margins in commoditized segments.
-
Sustainability certifications are becoming operational realities at major manufacturing sites, shifting the supplier selection criteria for downstream customers with decarbonization targets.
What the PW Consulting report contains — practical deliverables
PW Consulting’s SBS Market report is designed as a working toolkit for executive teams, commercial leaders and investors. Key deliverables include:
-
Topline market sizing and CAGR modeling (base year 2025; historical 2020–2025 and forecasts 2026–2032) with scenario variants for slower and faster demand recovery.
-
Supply-side atlas mapping current and announced capacity by technology and vintage, with implications for regional trade flows and logistics chokepoints.
-
Pricing sensitivity models linking styrene/butadiene feedstock scenarios, freight energy profiles and contractual pass-through terms to producer margins.
-
Competitive scorecards for the leading manufacturers, assessing asset quality, product breadth, technical service capability and strategic intent.
-
Regulatory and trade risk matrix — including anti‑dumping exposure, duty scenarios and compliance checklists — with mitigation pathways for buyers and sellers.
-
Commercial playbooks for buyers (sourcing strategies, hedging frameworks, supplier segmentation) and producers (go‑to‑market, product differentiation, sustainable premium capture).
-
Deal flow and M&A playbook: valuation heuristics, integration roadmaps and prioritized targets for bolt-on expansion.
Importantly, while this introduction outlines the report’s strategic architecture and high-level conclusions, it deliberately omits granular subsegment tables and region/application splits. Those detailed datasets and the underlying model are available exclusively in the full report and interactive dashboards.
How to apply the intelligence in 2026
-
For producers: prioritize feedstock risk reduction and accelerate certifications that unlock high-value contracts. Consider selective capacity adjustments where modeling shows short-term oversupply risk versus long-term demand positions.
-
For buyers and formulators: renegotiate contract terms to include dynamic cost pass‑through mechanisms and diversify sourcing to reduce landed-cost volatility. Use the supplier scorecards in the report to re-weight preferred-supplier lists ahead of 2026 procurement cycles.
-
For investors and strategic buyers: target assets that provide either product differentiation (technical grades) or logistical arbitrage (regional hubs). The report’s M&A playbook identifies the most accretive target archetypes under current market conditions.
Next steps
PW Consulting’s SBS Market report is built to inform the crucial strategic decisions companies will make in 2026 — from contract strategy and capacity investment to M&A and sustainability positioning. The topline forecasting shows clear growth potential through 2032, but the operational and regulatory variables outlined above will determine who captures value along the chain.
To access the full dataset, detailed segmentation, and the interactive scenario model, visit our report page. The complete package includes downloadable spreadsheets, supplier scorecards, and a customizable dashboard that translates the research into board-ready decision materials.
For detailed analysis of this topic, please visit the official page: Styrene Butadiene Styrene (SBS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


