



PW Consulting: Rubber Additives market at USD 6.12B in 2025, 4.32% CAGR to 2032

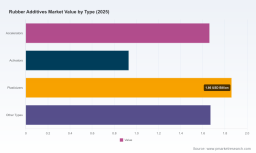
Rubber Additives Market — Strategic Outlook for 2026 Decisions
As companies frame tactical and capital choices for 2026, understanding the short‑ to medium‑term trajectory of the rubber additives market is essential. PW Consulting’s latest study (base year 2025) shows a market that reached USD 6.12 Billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.32% through the 2026–2032 forecast window, reaching roughly USD 8.23 Billion by 2032. This introduction highlights the study’s strategic value for executive decision‑making while deliberately withholding granular segment tables and regional/application splits to encourage consulting engagements or report access for the full dataset.
Rubber Additives Market
Why this study matters for 2026
-
Timing: 2026 will be a pivot year where regulatory shifts, raw material volatility, and accelerating sustainability requirements converge with ongoing product and process innovation in tire and non‑tire rubber applications.
Rubber Additives Market -
Precision vs. noise: The macro growth trajectory is steady but not runaway — companies can no longer rely purely on demand tailwinds. Competitive advantage will come from supply‑chain design, targeted product innovation, and disciplined commercial execution.
Rubber Additives Market -
Options value: The market concentration profile (CR3 and CR5 metrics) indicates room for both incumbent scale plays and regional specialty entrants to capture value — making deliberate M&A, JV, or licensing decisions high‑leverage moves in 2026.
Core market dynamics shaping 2026 strategy
-
Regulatory acceleration on chemical safety: 6PPD and related chemistries have moved to center stage in several U.S. jurisdictions. Anticipate near‑term mandatory phase‑outs, constrained use profiles, and higher compliance costs for certain legacy additives. Companies must embed regulatory scenario planning into product roadmaps now.
-
Feedstock price volatility: Upstream inputs such as aniline, carbon disulfide, and benzene continue to exhibit price swings. Producers with flexible feedstock sourcing, hedging strategies, or localized upstream integration will outcompete peers on margin stability.
-
Sustainability and performance convergence: Tire and industrial rubber makers are demanding additives that deliver both improved compound performance and a reduced environmental footprint — from lower VOCs to novel silane‑based chemistries and bio‑based process aids.
-
Operational agility and format innovation: Demand for predispersed and easier‑to‑handle formats is rising because they reduce processing variability at compounders and OEMs. This creates differentiated commercial propositions beyond pure chemistry.
Competitive landscape — what to watch
The competitive set blends global diversified chemical majors, specialized additives specialists, and fast‑growing regional players. The market exhibits moderate concentration — the largest three firms hold material share but well‑positioned regional players and niche specialists maintain meaningful footholds. Below are curated strategic takeaways about representative players (profiles summarized):
-
BASF SE (Ludwigshafen, Germany) — A leading global supplier with a broad rubber additives portfolio including amines and tackifiers. Strengths: R&D depth, formulation systems, and global supply readiness. Strategic implication: attractive partner for co‑development with OEMs and compounders that need integrated systems solutions.
-
LANXESS AG (Cologne, Germany) — Identified as the global leader in several rubber additive families. Recent moves: 2025 capacity expansion in Goose Creek (Bushy Park) and the 2025 launch of a sustainable antioxidant adopted by a major tire manufacturer; continued presence at industry shows in 2026. Strategic implication: incumbent scale and customer intimacy make LANXESS a pace‑setter — rivals must match localized service and sustainability credentials to defend share.
-
Evonik Industries AG (Essen, Germany) — Focused process additives for tire manufacturing that improve mixing and compound performance. Strategic implication: differentiated process aids can command premium positions when tied to cost‑of‑ownership improvements.
-
Momentive Performance Materials (Waterford, NY, USA) — Silane and specialty additive supplier with explicit positioning on compound optimization and environmental impact mitigation. Strategic implication: silane‑based strategies will play a growing role in low‑rolling‑resistance and EV tire development.
-
Other global majors and regional specialists — Arkema, Solvay, AkzoNobel, Wacker, Kraton, and a range of North American, European, Indian and Asian suppliers offer product‑level differentiation (predispersed chemicals, zinc oxide, accelerators, antioxidants). Strategic implication: a bifurcated market where scale plus application engineering wins large OEM contracts, and fast, nimble suppliers win specialty segments and regional compounder relationships.
Recent competitive actions that signal 2026 priorities
-
Capacity and localization: LANXESS’s expansion in South Carolina reflects an industry tilt toward near‑market production to reduce lead times and import exposure.
-
Product sustainability and co‑innovation: New antioxidant launches explicitly marketed as sustainable and quickly adopted by major tire makers show that product credibility plus OEM validation accelerates commercial uptake.
-
Trade show presence and technical outreach: Continued investments in industry events and technical collaborations indicate that knowledge‑transfer and formulation support are key commercial levers.
Scenario framing for 2026 decision‑makers
PW Consulting models three actionable scenarios to guide choices across capex, R&D allocation, and commercial strategy. Each scenario maps to decision triggers and suggested responses.
-
Baseline (reference) : Market follows the study’s CAGR (4.32%), with steady demand from tires and industrial applications. Decision triggers: stable feedstock costs, gradual regulatory tightening. Recommended actions: prioritize sustainability R&D, optimize supply chains, and accelerate predispersed product rollouts.
-
Downside (regulatory + resource shock) : Accelerated bans/restrictions on certain legacy chemistries and a spike in key feedstock prices compress volumes and margins. Decision triggers: ban announcements, significant price shocks. Recommended actions: accelerate reformulation programs, shore up liquidity, and establish strategic supply agreements for alternative chemistries.
-
Upside (rapid technology adoption) : Faster replacement of legacy additives with sustainable, high‑performance alternatives, coupled with OEM design shifts (e.g., EV tire optimization) that increase additive intensity per tire. Decision triggers: OEM design wins, large commercial validations. Recommended actions: scale manufacturing capacity selectively, lock long‑term supply deals with OEMs, and consider M&A to accelerate time‑to‑market.
Practical playbook for 0–18 months (priority actions)
-
Regulatory & product triage: Classify current product portfolio by regulatory risk and reformulation cost. Run accelerated compatibility tests with known 6PPD alternatives where exposure exists.
-
Secure feedstock optionality: Execute targeted supplier diversification and hedging for aniline, benzene derivatives, and other volatile inputs. Explore tolling or backward integration where economic.
-
Commercial fast‑wins: Offer predispersed and lower‑handling risk formats to compounders to reduce at‑plant conversion friction and earn customer lock‑in.
-
Co‑development partnerships: Proactively partner with tier‑1 tire OEMs and large compounders on validated replacements and joint sustainability roadmaps; secure early adopters to shorten commercialization cycles.
-
M&A and alliance scouting: Use the market’s moderate concentration and robust regional suppliers as a runway for targeted tuck‑ins or technology licensing to accelerate capability gaps.
-
Scenario financial planning: Stress‑test P&L against raw material shocks and regulatory scenarios; keep capital allocation flexible to favor modular capacity investments.
What the full PW Consulting report delivers (operational highlights)
-
Proprietary market model (2020–2032) with interactive scenario toggles, sensitivity to feedstock pricing, and demand elasticities for major application families.
-
Segment‑level volume and value forecasts, with validated assumptions and methodology notes (note: segment tables intentionally withheld from this preview).
-
Deep competitive benchmarking: product portfolios, technical differentiators, regional footprints, capacity maps, and recent strategic moves.
-
Regulatory impact maps and reformulation playbooks tied to likely jurisdictional changes in 2026–2027.
-
Supplier risk matrix and sourcing optimization levers (including suggested hedging strategies and candidate tolling partners).
-
M&A target shortlists and valuation lenses for specialty chemistries and predispersed manufacturers.
-
Commercial playbooks for lubricants, predispersed formats, silane chemistries, and antioxidant replacements — each with go‑to‑market priorities and expected payback windows.
How to use this preview in board and portfolio discussions
Present this strategic preview as a framework for scenario‑based capital allocation in 2026. Use the recommended playbook to prioritize near‑term operational moves that reduce regulatory and raw‑material exposure while positioning for upside if sustainable chemistries accelerate. If your organization is considering M&A, partnership, or localization, our full dataset and supplier scorecards will materially shorten diligence timelines and reduce deal execution risk.
Next steps
PW Consulting’s full Rubber Additives Market report contains the underlying segment tables, regional and application splits, and company‑level scorecards that support the recommendations above. That granular intelligence is intentionally gated in this preview to protect actionable commercial insights. Contact PW Consulting or visit our report page to access the complete model, custom scenario builds, and a tailored briefing for your executive team — essential inputs for high‑confidence decisions in 2026.
For detailed analysis of this topic, please visit the official page: Rubber Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


