



PW Consulting: Silicon Wafer Market Poised for 6.8% CAGR through 2032

Semiconductor Silicon Wafer Market — Strategic Briefing for 2026 Decision‑Makers
Executive trailer
This introduction outlines the strategic value of PW Consulting’s full Semiconductor Silicon Wafer Market study for companies making capital, sourcing, and product‑roadmap decisions in 2026. The briefing demonstrates our analytical depth—macro demand trajectories, concentration dynamics, supplier actions, and geopolitical headwinds—while reserving the granular segment and regional tables for the full report available on our site. Think of this as the trailer: rigorous, directional, and designed to catalyze executive decisions today while motivating stakeholders to access the complete intelligence set for implementation details.
Semiconductor Silicon Wafer Market
Market snapshot: the headline numbers that matter
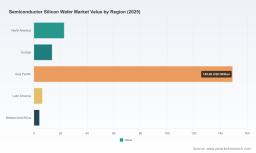
At the market level, the silicon wafer industry is on a multi‑year recovery and expansion path. Our model (base year 2025) projects the market to grow from roughly USD 195.6 million in 2025 to approximately USD 312.2 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. Historical trend analysis for 2020–2025 shows durable growth punctuated by cyclical stresses—useful when calibrating timing for capex or inventory moves in 2026.
Semiconductor Silicon Wafer Market
Operational metrics from industry bodies corroborate rising area shipments and revenue recovery: industry shipment volumes expanded into 2025 and accelerated further in early 2026, driven predominantly by AI and high‑bandwidth memory (HBM) demand for advanced epitaxial wafer types. These dynamics are creating both near‑term tightness in selected wafer formats and a longer runway of investment-led capacity additions.
Semiconductor Silicon Wafer Market
Why 2026 is an inflection year for strategic decisions
- AI and advanced packaging are accelerating demand patterns. Customer roadmaps for logic accelerators and HBM stacks are increasing demand for epitaxial and large‑diameter wafers—changing buying rules for OEMs and fabs.
- Supply‑side rebalancing is underway. Leading suppliers are shifting investments from brownfield expansion to targeted equipment upgrades and large‑diameter capacity buildouts—decisions that materially impact lead times and pricing through 2027–2029.
- Policy and financing are reshaping location decisions. Public funding mechanisms (e.g., CHIPS‑style programs) and evolving tariff/export controls are altering where new capacity is financially viable and politically tenable.
- Concentration compresses strategic choice. The wafer supply chain is highly concentrated (top‑3 suppliers account for a large majority of supply, top‑5 even more), which raises first‑mover value for buyers who secure preferred allocations or co‑investment terms.
Immediate strategic implications — what leadership teams must decide in 2026
- Capex timing and scale: Use scenario models that link wafer format demand curves to weighted lead‑time assumptions. Delaying or accelerating greenfield versus brownfield investments will change your cost of supply and market access over a multi‑year horizon.
- Supplier segmentation and contracting: Redefine tiering criteria beyond price—include technology roadmap alignment, allocation governance, and upgrade path commitments. Negotiate volume‑flex contracts with escape clauses tied to wafer format lifecycles.
- Risk mitigation and inventory strategy: Short pockets of format‑specific tightness suggest a hybrid approach: strategic buffer inventories for mission‑critical nodes combined with dynamic hedging for price volatility.
- M&A, JVs, and co‑investment: With high market concentration, selective equity stakes or long‑term supply agreements with leading wafer producers can secure privileged capacity. Evaluate opportunities to vertically integrate selectively where margins and strategic control justify capital deployment.
- Technology and product roadmap alignment: Accelerate co‑development with suppliers for epitaxial, SOI or advanced power substrates as required by your IC roadmaps—timing matters because supplier process windows are finite.
- Regulatory and trade playbook: Integrate tariff scenarios and export‑control contingencies into procurement decisions. Regulatory moves can re‑price geographic sourcing options rapidly; include them in supplier scorecards.
Competitive landscape — who matters and why
The wafer sector is dominated by a small number of high‑capacity, high‑technology suppliers. Market concentration amplifies the strategic value of supplier relationships and the consequences of supplier moves. Key industry players we profile in the full study include:
- Shin‑Etsu Chemical Co., Ltd. — globally leading producer across polished, epitaxial and SOI wafers; deep process expertise and scale (Tokyo‑headquartered).
- SUMCO Corporation — focused supplier across multiple diameters; recent strategic pivot toward equipment upgrades and consolidation of older assets underscores a shift to higher diameters.
- GlobalWafers Co., Ltd. — broad portfolio with accelerating US investment tied to public funding incentives; notable for power device and epitaxial capabilities.
- Siltronic AG — specialist in high‑purity wafers with strong presence in power and advanced logic segments; integration dynamics are noteworthy for European supply strategies.
- SK Siltron Co., Ltd. — supplier with polished and epitaxial strengths; relevant for East Asian and global sourcing decisions.
Recent corporate actions—facility closures, equipment upgrade prioritization, and multi‑billion dollar greenfield expansions—are reshaping allocation risk and the forward cost curve. The full report provides a supplier scorecard, investment maps and scenario‑specific allocation forecasts to help procurement and corporate development teams act with precision.
What the PW Consulting report delivers (practical, executable content)
Our market study is built for execution. Highlights include:
- Proprietary demand model (2020–2032) with scenario toggles for AI uptake rates, memory cycle timing, and advanced packaging adoption—convertible into stratified procurement forecasts for 12–36 month horizons.
- Capex and IRR playbook for wafer producers you may partner with or evaluate for M&A—sensitivity tests on time‑to‑market, yield ramps, and incremental margin curves.
- Supplier scorecards that synthesize technology fit, allocation risk, geopolitical exposure, and financial health into actionable procurement tiers.
- Tariff and export‑control matrix that quantifies downside exposure under plausible policy pathways and recommended mitigations.
- Operational tools: cost‑to‑serve maps, lead‑time heatmaps, and a negotiation checklist to convert strategic intent into binding supplier commitments.
- Playbooks for co‑investment structures and JV term sheets tailored to mitigate dilution and align long‑term capacity commitments with customer demand profiles.
Case‑level guidance (how to use the report in the next 90–180 days)
- Procurement directors: run the supplier scorecard and invite top‑tier suppliers to an allocation RFP tied to staged investment commitments.
- Corporate development: prioritize targets where valuation misalignment exists between local incentives and global demand forecasts; use our capex model to stress test synergies.
- Product & fab planners: re‑baseline BOMs and wafer mix assumptions in your 2027 roadmaps; plan qualification windows that align with supplier upgrade timelines.
- Risk & compliance teams: adopt the tariff sensitivity scenarios and policy triggers in our matrix as part of your quarterly risk register updates.
Why PW Consulting — an outcome focus
Our research combines macro demand forecasting, granular supplier analysis, and executable commercial playbooks. The market’s concentrated supplier base and the overlay of AI‑driven product demand mean that timing, supplier choice, and contractual structure will determine competitiveness for years. The study is designed not merely to inform but to enable buy‑side and strategic decisions in 2026 that lock in lower total cost of ownership, secured allocation, and better strategic optionality.
Next step — access to full intelligence
This briefing intentionally omits the detailed regional and application splits and the proprietary sensitivity tables that underpin our recommendations—the core data that execution teams need. Accessing the full report provides those granular breakdowns, interactive models, and supplier dashboards required to operationalize the strategies summarized here. To obtain the complete dataset, forecasts by wafer type and application, supplier scorecards, and the negotiation playbook, please visit the PW Consulting report page or contact our analyst team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Semiconductor Silicon Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


