



PW Consulting: Electronic Ear Tags Market to Hit USD 344.8M by 2032 (6.98% CAGR)

Electronic Ear Tags for Livestock: Strategic Imperative for 2026 — A PW Consulting Preview
Introduction — why this market matters now
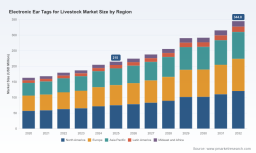
The electronic ear tag market for livestock has graduated from niche precision-agriculture tool to core infrastructure for animal health, biosecurity and supply-chain transparency. Our analysis, based on a 2025 base year and a seven-year forecast through 2032, shows a clear and sustained growth trajectory — the global market size expands meaningfully from the 2020–2025 historical window into the forecast period, tracking at a compound annual growth rate (CAGR) of approximately 6.98%. By 2032 the market is projected to be materially larger than it was in 2025, reflecting the combined effects of regulation, procurement programs, technological maturation and commercialization of services layered on physical devices.
Electronic Ear Tags for Livestock Market
For corporate leaders evaluating product roadmaps, channel investments, M&A targets or go-to-market pivots in 2026, this is the inflection year: regulatory mandates and public programs are reshaping demand, new software integrations are compressing implementation friction, and supplier ecosystems remain sufficiently fragmented to reward disciplined consolidation or partnership strategies.
Electronic Ear Tags for Livestock Market
Why 2026 is a strategic decision point
-
Regulatory inflection: The post-2024 regulatory environment—most notably the rulemaking that requires ear tags applied after late-2024 for interstate cattle movement to be both visually and electronically readable—has accelerated procurement cycles among livestock producers and widened the definition of “compliant” device functionality. Parallel actions, including program-level distribution of no-cost RFID tags to eligible producers and region-specific traceability mandates, are creating pockets of immediate demand and new compliance requirements that manufacturers and integrators must internalize when sizing channels and forecasting revenue.
Electronic Ear Tags for Livestock Market -
Legal and policy uncertainty: Litigation challenging mandatory EID requirements is active and may alter adoption timing or cost responsibilities for producers. Executives must therefore build strategies that are robust across contestable regulatory outcomes—balancing near-term execution with contingency plans for shifts in cost pass-through and adoption subsidies.
-
Technology convergence: Bluetooth-enabled readers, improved EID reader integration, and barcode/RFID matching capabilities are reducing labor costs and read-failure rates. Software updates and platform integrations are converting tags from single-purpose identifiers into gateways for digital herd management, enabling monetizable analytics and services.
What the PW Consulting report delivers (practical, actionable content)
Our full market study is designed for decision-makers who need executable guidance rather than academic description. The report combines quantitative forecasting, qualitative competitive analysis and operational playbooks structured to support procurement, product and corporate strategy teams. Highlights include:
- Top-line market forecasts (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario-modeled demand curves tied to specific regulatory and subsidy outcomes.
- Modular go-to-market playbooks: channel segmentation, distributor economics, and pricing levers for hardware, consumables and recurring services.
- Total cost of ownership (TCO) and unit-economics templates to evaluate capex vs. service models (hardware sales, tag-as-a-service, subscription analytics).
- Regulatory and compliance matrix aligned to major jurisdictions and program rules, plus a litigation-risk dashboard to stress-test adoption scenarios.
- Supplier due-diligence pack and M&A screening criteria tailored to the market’s observed concentration and technology clusters.
- Field-proven implementation checklists covering reader infrastructure, integration with herd-management software, and traceability assurance testing.
Note: detailed segmentation tables (by region, species, and tag type), raw model files and vendor scorecards are intentionally reserved for the full report to preserve the competitive value of the underlying data and modeling assumptions.
Market dynamics and investment implications
The forces shaping the market are familiar — regulation, animal-health economics, and digitalization — but their interplay is producing new strategic vectors:
- Demand acceleration from compliance and subsidy programs: Regulatory rules and government-supported tag distribution have created an immediate procurement window for suppliers and integrators. Companies that can demonstrate verified compliance and streamlined distribution will disproportionately capture 2026 demand.
- Fragmented supplier landscape: The industry remains moderately fragmented, with the largest competitors accounting for a relatively modest share of total market value. That fragmentation creates opportunities for roll-up strategies, exclusive distribution partnerships, and platform plays that stitch device-level data into enterprise farm-management systems.
- Services as differentiation: Device specification is becoming table-stakes; differentiation will increasingly come from software integration, analytics, financing and after-sales service. Firms that move up the value chain can turn one-time device sales into annuity revenue and deeper customer relationships.
- Cost pressure and adoption economics: Per-head cost remains a concern for many producers. Successful commercial strategies will either reduce total installed cost through integrated solutions or create compelling ROI narratives (disease risk reduction, market access, logistics efficiencies).
Competitive landscape — who matters and why
The current supplier set includes established device specialists and regional players that have secured program approvals and distribution channels. A concise assessment of key participants reveals where competitive advantage lies:
- Datamars SA (Switzerland) — Strength: broad FDX/HDX product family with USDA 840 AIN and ICAR certifications, and clear product-line extensions (e.g., weighing tags). Strategic posture: premium product quality and certification leadership position Datamars well for program-driven procurement and export markets.
- Allflex USA, Inc. (United States) — Strength: expansive product portfolio and recognized brand across multiple species; compatibility with visual tag systems. Strategic posture: scale player with deep channel relationships and the ability to bundle solutions into enterprise offerings.
- Caisley International GmbH (Germany) — Strength: niche innovations such as tissue-collection integrated tags. Strategic posture: product differentiation through integrated sampling capabilities attractive to vertically integrated operations and genetics-focused buyers.
- Shearwell Data Limited (UK) — Strength: metal tag manufacturing and certified 840-series offerings. Strategic posture: focused on durability and regional compliance—appeals to producers prioritizing longevity and strict regulatory alignment.
- Y-Tex Corporation (United States) — Strength: established tagger systems and USDA-approved 840 series tags. Strategic posture: strong North American channel capabilities and field-support infrastructure.
- All Data Tags LLC, Leader Products, AniTrace, Inc. — Strengths: targeted product designs (button, panel, UHF/HDX/FDX variants) and program approvals. Strategic posture: nimble innovators who can win on specialized specs, speed-to-market and price.
Recent industry developments underscore these competitive themes: software vendors are accelerating reader integration (example: Bluetooth-enabled reader updates roll out in late 2025), device manufacturers continue to publish enriched product catalogs emphasizing compliance and integrated features, and litigation over mandatory tag requirements introduces timing risk for adoption-driven players.
Actionable strategic recommendations for 2026
Based on our scenario work and supplier due-diligence, we recommend executives prioritize the following actions this calendar year:
- Run three adoption scenarios in Q1–Q2: base, accelerated (policy-driven), and delayed (legal challenge) — stress-test supply, working capital and channel incentives under each.
- Secure compliance endorsements early: ensure products are validated against official device lists and maintain documentation for program eligibility; this reduces procurement friction in government-supported deployments.
- Pilot integrated service bundles: pair tags with data ingestion, analytics and financing to demonstrate clear ROI to producers; focus pilots on high-value disease-control or market-access use cases.
- Prioritize interoperability: support standard protocols and reader compatibility to minimize customer switching costs and enable partnerships with farm-management platforms.
- Evaluate M&A and partnership targets: look for targets that fill capability gaps (software telemetry, distribution reach, tissue-sampling tech) and can accelerate entry into prioritized geographies.
- Design contingency procurement: diversify suppliers and build inventory buffers to protect against sudden demand spikes tied to regulatory deadlines.
- Engage with policymakers and producer groups: shape implementation guidance, secure funding programs, and mitigate litigation-driven uncertainty through proactive stakeholder engagement.
Conclusion — how this research informs your 2026 playbook
For leaders deciding where to allocate capital and attention in 2026, electronic ear tags are a strategic lever that combines regulatory compliance, animal-health economics and digital transformation. The market’s steady CAGR and growing addressable use cases make it attractive, but success requires operational rigor: validated compliance, interoperable technology, service-enabled commercial models and contingency planning for regulatory shifts.
PW Consulting’s full report provides the granular segmentation, vendor scorecards, Excel-modelled forecasts and implementation playbooks required to translate the high-level moves above into executable 90–180 day plans. For commercial teams and boards preparing strategic decisions this year, the full dataset and supplier assessments are essential reading.
Next step
Access the full Electronic Ear Tags for Livestock Market report on the PW Consulting portal to obtain the detailed segmentation tables, downloadable financial models and vendor dossiers that underpin the recommendations summarized here. If you would like a tailored briefing or a workshop to translate this analysis into a bespoke action plan for your organization, contact PW Consulting’s Agriculture & Animal Health practice team to schedule a session.
For detailed analysis of this topic, please visit the official page: Electronic Ear Tags for Livestock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


