



PW Consulting: Surgical Sponge Market to Reach USD 1,358.86M by 2032

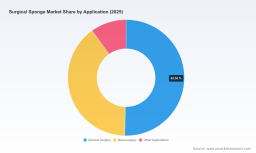
Surgical Sponge Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our latest Surgical Sponge Market study — a pragmatic, decision-ready briefing designed specifically for executives planning actions in 2026. This overview highlights the research’s strategic value, synthesizes the macro dynamics you must internalize, and outlines the actionable frameworks included in the full report. In keeping with the “trailer” principle, I demonstrate analytic depth while intentionally withholding the full granular segmentation so that procurement, commercial and M&A teams are motivated to access the complete dataset and playbooks.
Surgical Sponge Market
Why this research matters for 2026 decision cycles
-
Market momentum: The surgical sponge market has evolved from a stabilizing recovery phase into a sustained expansion driven by procedural volume recovery, perioperative safety initiatives, and product innovation. Our base-year sizing (2025) establishes a clear growth trajectory that the forecast period amplifies — a multi-year compound annual growth rate (CAGR) in the high single digits that materially changes portfolio planning and capacity decisions.
Surgical Sponge Market -
Investment inflection: With predictable top-line expansion and rising regulatory scrutiny around sterilization and retained items, 2026 is a pivotal year for capital allocation — particularly for manufacturing upgrades, sterilization capacity, and automation in inventory controls.
Surgical Sponge Market -
Competitive consolidation pressure: The market shows moderate concentration among leading players. This concentration creates both defensive risks for smaller suppliers and acquisition opportunities for mid-sized manufacturers seeking scale or specialty portfolio additions.
High-level market snapshot (macro figures)
Our model, calibrated on verified historicals and clinician-validated demand signals, positions the market at a meaningful scale by the 2025 base year and projects steady, above-market healthcare growth through 2032. The forecast period (2026–2032) reflects a CAGR of approximately 7.76% under our base scenario, driven by a combination of volume expansion, premiumization in specialty sponges, and additive pricing linked to compliance and convenience features. These macro figures are embedded across our scenario analyses and financial models to support realistic planning for CAPEX, supply agreements, and R&D prioritization.
Dynamics shaping supplier economics and demand
-
Regulatory and sterilization convergence — Standards such as EN ISO 14630:2024 and recognized sterilization processes (e.g., the FDA-recognized low-temperature vaporized hydrogen peroxide standard) are elevating baseline requirements for new product introductions and contract tendering. Suppliers unable to demonstrate validated sterilization pathways or to comply with biocompatibility expectations face longer qualification timelines and contracting friction.
-
Clinical safety focus — Retained surgical items remain a top operational and reputational risk for hospitals. Manual counting protocols are still standard, but there is growing willingness to invest in adjunct technologies and enhanced product features (radiopaque markers, antimicrobial coatings) to reduce liability and operational burden.
-
Reimbursement nuances — Policies that link eligibility for coverages to documented wound conditions and dressing criteria are tightening. Suppliers and hospital procurement teams must align product labeling and clinical evidence to reimbursement pathways to sustain downstream adoption in wound-care use cases.
-
Materials and process constraints — Autoclave durability and biocompatibility requirements are real design constraints for manufacturers. Achieving repeated steam-cycle resilience while maintaining absorbency and handling characteristics requires focused materials science investment or outsourced specialty manufacturing partnerships.
Competitive landscape — what to watch
The market is populated by global healthcare conglomerates, specialized consumables manufacturers, and large distributors that integrate sponges into broader surgical kits. The competitive field includes North American distribution powerhouses, European specialty manufacturers, and high-volume Asian producers. A combination of manufacturing footprint, distribution breadth, and clinical brand credibility determines supplier value in hospital systems.
-
Large healthcare conglomerates bring integrated offerings and strong clinical relationships; they can bundle sponges into clinician-preference kits and leverage established sterile product portfolios to win tenders quickly.
-
Specialty European and Scandinavian manufacturers emphasize premium features and clinical evidence to command higher ASPs in advanced surgical segments.
-
High-volume Asian producers compete on cost and scale, often serving tier-two hospital networks, contract manufacturers, and private-label programs.
Importantly, our market concentration analysis indicates a moderate level of aggregation among the top competitors — a market where three to five firms control a meaningful portion of sales. That structure creates tactical openings for focused challengers (niche product features, regional logistics excellence) and strategic playbooks for incumbents (value-based contracting, loyalty incentives, and supply-chain resilience commitments).
Recent industry moves and implications
-
Product launches of antimicrobial and expanded-range surgical sponges signal ongoing product-level innovation. Expect procurement committees to increasingly evaluate clinical differentiation rather than selecting purely on unit price.
-
Distribution contracts with defense and government buyers illustrate the role of large-scale tenders in absorbing manufacturing capacity and setting long-term revenue visibility for suppliers that can meet strict qualification standards.
-
New entrants, particularly from China and Southeast Asia, are expanding portfolios and adding manufacturing breadth. For Western buyers, this increases supplier options but also requires tighter quality assurance programs and regulatory vigilance.
What the full PW Consulting report contains — practical deliverables
The full study is structured as an operator’s toolkit for 2026 decision-making. It blends quantitative analytics with step-by-step playbooks and templated tools:
-
Market sizing and scenario models — Transparent assumptions, sensitivity testing, and downloadable financial templates to stress-test revenue and margin outcomes under alternate growth and pricing assumptions.
-
Demand segmentation framework — Clinically validated usage profiles by surgical specialty and care setting, with purchaser personas and adoption drivers (note: we withhold the granular numerical splits in this executive preview).
-
Supplier benchmarking — Comparative scorecards across manufacturing quality, sterilization capabilities, channel reach and contract performance for the market’s leading firms.
-
Regulatory & compliance checklist — Actionable steps to demonstrate sterilization process validation, biocompatibility compliance, and documentation practices keyed to recent ISO and FDA-recognized standards.
-
Procurement playbook — Tender language templates, evaluation scorecards, total cost of ownership (TCO) calculators, and logistics risk mitigation checklists to use in 2026 RFPs.
-
Commercial go-to-market playbook — Channel strategies, clinician engagement plans, clinical evidence roadmaps, and pricing architectures for premium and value segments.
-
M&A and partnership screening — A prioritized shortlist methodology for bolt-on targets, contract-manufacturing synergies, and JV frameworks to scale geographically or product-wise.
-
Risk heatmaps — Supplier concentration scenarios, single-source dependency analyses, and scenario playbooks for sterilization disruptions or regulatory changes.
Recommendations for 2026 corporate actions
-
Procurement: Shift from unit-price negotiation to TCO and clinical-outcome-linked contracting. Integrate sterilization validation and retained-item mitigation metrics into supplier scorecards.
-
Manufacturing & Operations: Prioritize investments in validated low-temperature sterilization capability and materials R&D to improve durability under autoclave cycles and to support premium product claims.
-
Product & Clinical Affairs: Accelerate clinical evidence programs for antimicrobial and radiopaque features. These attributes are increasingly decisive in hospital formulary decisions and in limiting retained-item incidents.
-
Commercial & Channel Strategy: For distributors and manufacturers, strengthen value-add services (inventory management, automated counting systems integration, clinician training) to differentiate in a moderately concentrated market.
-
M&A & Portfolio Strategy: Use the market’s mid-level concentration to pursue targeted acquisitions that add specialty product lines or regional distribution footprints rather than broad-scale roll-ups.
-
Risk & Compliance: Embed ISO and FDA-recognized sterilization pathways, and align labeling with payor eligibility criteria to guard reimbursement and procurement access.
How to use this preview
This briefing is a strategic trailer: it signals the directions, risks and opportunities we see shaping procurement, manufacturing and commercial decisions in 2026. PW Consulting’s full Surgical Sponge Market report provides the withheld granular segmentation, regional and application-level trackers, supplier market shares, and downloadable models that your strategy, procurement, and M&A teams will need to act decisively. If your 2026 plan includes manufacturing investment, private-label expansion, or acquisition activity in surgical consumables, the full dataset and playbooks are a prerequisite to mitigating execution risk and capturing upside.
Next steps
-
Contact PW Consulting to request access to the full report, including segmented demand matrices, supplier market-share tables, and the downloadable scenario models.
-
Schedule a strategy workshop where our advisors will run a tailored 90-minute session using your current supplier list and procurement contracts against our market scenarios for 2026.
PW Consulting’s deep-dive combines market rigor, clinical validation, and transaction-level practicality — intentionally balancing public insight with proprietary analysis to ensure your 2026 decisions rest on defensible, action-ready intelligence.
For detailed analysis of this topic, please visit the official page: Surgical Sponge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


