



PW Consulting: Residential Ventilation Systems Market to Grow at 5.85% CAGR to 2032

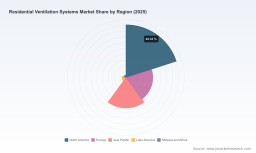
Strategic Preview: Residential Ventilation Systems Market — A 2026 Decision-Maker’s Guide
As PW Consulting’s senior strategic advisor and chief industry analyst, this briefing offers a focused, decision-grade preview of our full Residential Ventilation Systems Market study. It is written to help executive teams prioritize actions in 2026: where to invest, which risks to hedge, and how to shape product and M&A agendas. This note demonstrates the analytical depth of our work while intentionally withholding granular segmentation tables and proprietary scorecards — the full intelligence package is available through our report portal.
Residential Ventilation Systems Market
Why this study matters for 2026 planning
-
Market momentum: The residential ventilation market has expanded steadily across the 2020–2025 historical window (base year 2025), and our forecast (2026–2032) projects continuation of that growth at a compound annual growth rate (CAGR) of approximately 5.85%.
Residential Ventilation Systems Market -
Scale and trajectory: Measured in Million USD, the market crosses notable thresholds between the mid-2020s and early 2030s. This creates distinct inflection points for product investment, channel development, and regulatory-aligned innovation.
Residential Ventilation Systems Market -
Competitive context: Market concentration is modest — our CR3 and CR5 metrics show that no small group of firms dominates the market, signaling opportunity for rapid share gains through targeted execution and differentiated offerings.
Macro dynamics shaping decision levers in 2026
-
Regulatory acceleration. Updated regional standards — most notably ANSI/ASHRAE Standard 62.2-2025 — raise mechanical ventilation requirements and add operational guidance for kitchen ventilation in homes with gas stoves. Compliance is moving from “nice to have” to procurement prerequisite for major builders, lenders, and renovation programs.
-
Energy & efficiency pressure. Energy recovery and balanced ventilation architectures are ascending the priority list for both new builds and high-value retrofits, driven by homeowner energy-cost sensitivity and decarbonization policies.
-
Technology convergence. Expect increasing integration of air quality sensors, IoT-enabled control, and demand-controlled ventilation as buyers trade up for demonstrable health and efficiency outcomes.
-
Supply-side volatility. Raw material price swings — especially in steel and aluminum — are compressing margins and introducing timing risk to product launches and competitive pricing strategies.
Competitive landscape — how leading players are positioning
With a relatively low CR3/CR5 (indicative of a fragmented market), competitive advantage is being created through channel strength, product differentiation, regulatory positioning, and partnerships. Below we summarize strategic postures of notable incumbents and recent industry movements that shape 2026 tactics.
-
Broan-NuTone LLC (Wisconsin, USA) — A dominant brand in residential ventilation hardware and indoor air quality solutions. Its recent participation on the RESNET Suppliers Advisory Board signals an explicit push into standards-influencing forums and downstream builder relationships. Strategic implication: Broan is prioritizing standards alignment and specification channels; competitors should evaluate specification capture strategies and builder partnerships to neutralize this influence.
-
RenewAire LLC (Wisconsin, USA) — Specialized in ERVs/HRVs and energy recovery technologies for homes. Its niche focus positions it as a preferred supplier where energy recovery is mandated or financeable under efficiency programs. Strategic implication: Larger diversified vendors may target RenewAire through OEM partnerships or bolt-on acquisitions to accelerate entry into energy recovery categories.
-
Systemair AB (Sweden) — European player emphasizing integrated air treatment and balanced ventilation. Systemair’s ISH 2025 exhibit underscored its product-platform orientation for project-specification channels. Strategic implication: Global players should expect Systemair to defend technical leadership in balanced systems and to pursue project-level collaborations in markets where balanced solutions become code-driven.
-
Duco Ventilation (Belgium) — Focuses on premium residential systems and has showcased low-noise connectivity and trim innovations at InstallerSHOW 2025. Strategic implication: Product design and installer ergonomics are differentiators — successful players invest in quiet, easy-to-install configurations and installer training programs.
-
Aldes Group (France) and Zehnder Group (Switzerland) — Both emphasize energy-efficient home air quality management and heat-recovery technologies. Their European footprints and product sophistication make them natural partners for builders pursuing net-zero or near-zero energy targets. Strategic implication: North American players should watch for cross-border technology transfer and consider alliances to bring advanced heat recovery systems to retrofit markets.
Recent market signals to act on in 2026
-
Trade-show innovation is accelerating product cycles. Exhibitions in 2025–2026 (ISH, InstallerSHOW, ARBS) highlighted product integration and installer-focused designs — a clear signal to accelerate product readiness cycles and field pilots.
-
Standards-influence is a competitive moat. Firms participating in advisory boards and standards bodies are shaping practicable compliance pathways, which can create specification advantages in public and private sector procurement.
-
Installer & distribution networks will decide adoption. Several vendors are investing in installer experience and channel incentives; firms that deprioritize installer economics risk slower adoption despite strong product specs.
Risk map and mitigation priorities
-
Raw material volatility: Price exposure for steel and aluminum can erode margins. Mitigation: adopt flexible purchasing contracts, verticalize key components where feasible, and redesign for material efficiency.
-
Regulatory compliance risk: ASHRAE 62.2-2025 and similar codes raise the bar for product certification and installation guidance. Mitigation: fast-track testing, secure third-party certifications, and publish installer guidance aligned to new operational clauses (e.g., kitchen ventilation for gas stoves).
-
Channel execution risk: Fragmented installer bases and heterogeneous regional codes make scale deployment uneven. Mitigation: segment go-to-market by channel readiness and fund targeted installer training pilots in high-opportunity corridors.
What our full report delivers (practical, operational tools)
The complete PW Consulting study is built as a toolkit for commercial execution. Highlights include:
-
Forward-looking revenue model and sensitivity scenarios for 2026–2032 (base year 2025), including upside/downside paths tied to regulatory adoption rates and retrofit stimulus.
-
Company benchmarking and capability heatmaps for product portfolios, channel strength, regulatory positioning, and R&D focus — designed for quick target-screening in M&A or partnership pursuits.
-
Installer economics and go-to-market playbooks tailored to new-build vs. retrofit channels, plus sample incentive structures for dealer and contractor networks.
-
Supplier risk matrix and raw-material exposure analysis with recommended hedging and sourcing strategies.
-
Technology adoption roadmaps for energy recovery, balanced systems, and IoT-enabled controls — with suggested product roadmaps and near-term MVP features.
Note: This preview intentionally omits our granular regional, type, and application revenue splits and the complete candidate list of acquisition targets. Those datasets, and accompanying Excel models, are accessible only in the full report.
Strategic actions we recommend for 2026
-
Immediate (0–6 months): Conduct a standards-compliance audit against ASHRAE 62.2-2025; prioritize product updates that avoid rework at scale. Lock in multi-quarter supply agreements for metals to stabilize cost inputs.
-
Near term (6–18 months): Pilot energy-recovery product kits and installer-friendly balanced system modules in targeted retrofit corridors. Launch an installer certification program to accelerate specification capture.
-
Medium term (18–36 months): Pursue acquisition or OEM partnerships to close capability gaps in ERV/HRV technologies or digital controls. Scale up marketing for health & energy value propositions tied to new code requirements and utility incentive programs.
How to use this preview: recommended next steps
This strategic preview is intended to catalyze executive alignment heading into 2026. If you are responsible for product strategy, channel development, procurement, or corporate development, the next logical steps are:
-
Commission a one-day executive briefing with our analysts to review the models most relevant to your P&L and scenario assumptions.
-
Purchase the full report to obtain the granular regional and application splits, the Excel-based forecast model, and the prioritized M&A shortlist.
-
Engage PW Consulting for a targeted implementation sprint — we can convert the report’s strategic recommendations into an operational 12–24 month roadmap tailored to your organization.
In a market where regulation, energy priorities, and installer economics intersect, being first to operationalize compliance-driven product features and installer enablement programs will deliver outsized gains. Use this preview to align your 2026 budget cycles and to prioritize initiatives that are both defensible and scalable. For access to the full dataset, models, and tactical playbooks, please refer to the PW Consulting report delivery page.
For detailed analysis of this topic, please visit the official page: Residential Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


