



PW Consulting: Medical-Grade Hydrogel Market to Reach USD 2,650M by 2032 at 6.5% CAGR

Medical Grade Hydrogel Market: Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor, I present a concise yet substantive preview of our new Market Research on Medical Grade Hydrogels. This briefing is designed to help executives, corporate development teams, and product leaders orient 2026 strategies around a market that is maturing steadily but still offers distinct windows for differentiation. The report blends quantitative trend-anchoring with qualitative playbooks — enough to inform your strategic thesis, but intentionally withholding granular segmentation tables to drive a direct engagement with the full study for transaction- or program-level moves.
Medical Grade Hydrogel Market
High-level market trajectory you must factor into 2026 planning
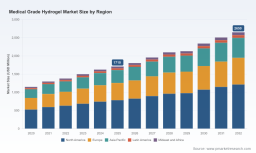
- Market momentum: The global medical grade hydrogel market expanded from approximately USD 1,150 Million in 2020 to about USD 1,710 Million in 2025 (base year). Our sector model projects a compound annual growth rate (CAGR) of 6.5% through the 2026–2032 forecast window, reaching roughly USD 2,650 Million by 2032.
- Concentration signal: Market concentration metrics indicate a moderately fragmented marketplace; the top three players account for just under half of market revenues, with the top five approaching a slight majority. This structure creates both price pressure and room for specialist entrants to capture niche value.
- Structural inflection points: Growth drivers in 2026 are expected to be multi-faceted — clinical adoption of advanced dressings and device interfaces, OEM partnerships for biosensing and electrophysiology consumables, and regulatory clarity on device classifications that lower barriers for non-drug hydrogel products.
Why this report is strategically valuable for 2026 choices
- Decision-ready sizing: We provide a validated historical series (2020–2025) and scenario-linked forecasts (2026–2032) to support budgeting, capacity planning, and valuation modeling.
- Go/no-go thresholds: The study translates market growth and concentration into practical revenue and margin thresholds for new product launches, contract manufacturing investments, and M&A target screens — not merely high-level advice but operational gating criteria executives can use immediately.
- Regulatory roadmaps: With device classification nuances increasingly material to time-to-market, our regulatory modules map the clinical and compliance pathways (including ISO 10993 implications and FDA establishment/registration considerations) into a timeline that links to product development milestones.
- Execution playbooks: We convert strategic choices into tactical plans — from short-term commercialization sprints for OEM co-development to 18–24 month scale-up plans for manufacturing and supply continuity.
What’s inside the full PW Consulting study (practical, operational deliverables)
- Market sizing and validated growth scenarios with sensitivity testing for pricing, raw-material stress, and accelerated clinical uptake.
- Segment-level demand drivers and buyer personas to align product design with procurement behavior across hospitals, OEMs, and device assemblers.
- Supply-chain and raw-material mapping, including critical single-source risks and contract-manufacturing levers.
- Regulatory playbook: device classification guidance, recommended test matrices, and estimated compliance timelines for different product designs.
- Competitive benchmark: capability matrices, go-to-market footprints, IP and regulatory moats, and an M&A target scoring framework tuned to strategic fit and integration risk.
- Commercial playbooks: channel strategies (direct OEM vs. distributor-led), pricing benchmarks, and tactical launch plans with 12–36 month KPIs.
- Risk heatmaps and mitigation options covering materials, regulatory change, reimbursement shifts, and supplier concentration.
Market dynamics and regulatory context — what will alter market economics in 2026
- Regulatory nuance: Hydrogel wound dressings and non-drug hydrogel products frequently fall into lower-risk regulatory classifications (e.g., FDA Class I exemptions for certain wound dressings), but they still require establishment registration and adherence to biocompatibility standards. ISO 10993 test regimes (cytotoxicity, primary skin irritation, sensitization) remain a gating factor for skin-contact devices.
- Certification as a competitive moat: Leading producers operate under FDA registration and ISO 13485-compliant quality systems. Certification reduces time-to-contract for OEM partnerships and opens procurement paths into large medtech buyers that require audited suppliers.
- Manufacturing paradigms: Differentiation increasingly depends on manufacturing capabilities — electron-beam crosslinking, polymer chemistry expertise (e.g., PVP-chitosan blends), and clean-room assembly for device-integrated hydrogels. Contract manufacturing and small-run flexibility are decisive for OEM trials and early-stage clinical programs.
- Raw-material and customer concentration risks: Several high-value relationships — where small production runs serve strategic OEM partners — highlight the need for contingency planning in 2026. Securing diversified supply or strategic supply agreements can be the difference between winning a contract and missing a clinical milestone.
Competitive landscape — what the leading suppliers are signaling
Our competitive audit focuses on both large OEM suppliers and specialized contract manufacturers. Key players in the current landscape exemplify two archetypes: scale OEMs with certified product lines and boutique, compliance-focused specialists that serve OEMs and device assemblers.
Medical Grade Hydrogel Market
- NEXGEL, Inc. — An FDA-registered, ISO 13485-certified manufacturer focused on custom electron-beam cross-linked hydrogels. Strengths: tailored small-run production for OEMs and early clinical programs, regulatory discipline. Strategic signal: initiation of IRB-led clinical work in 2024 indicates a push toward clinical validation and broader OEM acceptance.
- Hydromer, Inc. — Known for PVP-chitosan-based formulations and hydrophilic coatings, recently documented ISO 13485 certification. Strengths: material science capability and regulatory certification that support device-level partnerships. Strategic signal: certification activity underpins readiness for higher-value contracts and device-integrated roll-outs.
- R&D Medical Products — Specializes in repositionable hydrogels used in wound care and electrode applications. Strengths: niche product designs and OEM customization. Strategic signal: demand for repositionable, patient-facing adhesives remains strong in monitoring and wound-management niches.
- Katecho — ISO 13485-certified contract manufacturer offering end-to-end design and assembly. Strengths: assembly and clean-room integration for pharma-device combos; suitable for companies seeking to outsource regulated production.
- Cardinal Health — A large OEM with established product lines for cardiology and electrophysiology (e.g., ECG and defibrillation hydrogels). Strengths: scale manufacturing, distribution networks, and long-standing procurement relationships with health systems.
Collectively, these firms reveal a market where regulatory credibility and manufacturing modality are the primary axes of competition. Expect incumbents to defend via certification and scale, while specialists compete on customization and speed to clinic.
Medical Grade Hydrogel Market
Strategic implications and recommended actions for 2026
- Prioritize certification early. For any company planning to enter or expand in medical-grade hydrogels, ISO 13485 certification and a mapped ISO 10993 testing plan shorten commercial lead times and unlock OEM procurement opportunities.
- Match manufacturing model to strategy. If you pursue OEM co-development or clinical-service agreements, invest in flexible small-run capacity (e.g., electron-beam or radiation crosslinking) or secure partnerships with certified contract manufacturers.
- Use concentration metrics in deal screens. The market’s moderate concentration implies attractive tuck-in M&A opportunities — but ensure target selection emphasizes regulatory compliance, repeatable manufacturing processes, and validated customer relationships.
- Design supply continuity into contracts. Given single-customer production patterns in some cases, contractual protections and dual-sourcing for key polymers will reduce commercial risk and protect clinical timelines.
- Accelerate clinical evidence selectively. Clinical studies targeted at demonstrating device-level improvements (e.g., reduced irritation, improved conductivity for electrophysiology pads) materially enhance OEM negotiation leverage and can justify premium pricing.
- Segment go-to-market by buyer type. Differentiate commercial approaches between hospital procurement (value and reimbursement focus), OEM customers (technical spec and integration), and specialty distributors (volume and logistics).
Using the PW Consulting study as an operational tool
The full report is structured to be used hard — not just read. We provide scenario models you can drop into your board packs, a target scoring matrix for M&A diligence, and supplier due-diligence templates that align quality, cost and time-to-market considerations. For product teams, the regulatory timelines and test matrices act as an integrated Gantt to plan R&D, clinical, and production milestones.
This preview intentionally omits the granular segmentation tables and regional/application breakdowns that are central to execution-level decisions. Those segment-level insights, including demand by application and regional exposure, are included in the full study and are critical for pricing strategies, market-entry sequencing, and M&A valuation adjustments. If you are preparing a capacity investment, bid for a strategic OEM partnership, or evaluating acquisition targets in 2026, the full dataset will materially change both the calculus and the timing.
Next steps
- For C-suite teams: request the data-appendix and scenario models to embed into Q2 planning assumptions and capital allocation discussions.
- For corporate development: use our M&A target scoring framework to run an initial screen of acquisition candidates against the market concentration and capability map.
- For product and R&D leaders: align your 12–18 month development roadmap with the regulatory test matrix in the report to remove approval timing as a source of commercial risk.
PW Consulting’s full Medical Grade Hydrogel Market study delivers both the strategic context and the actionable mechanics necessary for confident 2026 decision-making. This preview highlights the market trajectory, regulatory inflection points, and competitive dynamics you must weigh now — access the complete study to operationalize these insights with the segment-level data that drives pricing, capacity, and M&A execution.
For detailed analysis of this topic, please visit the official page: Medical Grade Hydrogel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


