



PW Consulting: HPMC Vegetable Capsule Market to hit USD 780M by 2032 at 8.4% CAGR

Vegetable (HPMC) Capsule Market 2026: Strategic Preview for Executive Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our full Vegetable (HPMC) Capsule Market study — a focused briefing designed to orient corporate leaders, investors, procurement heads, and R&D executives as they plan through 2026 and beyond. This preview surfaces the critical market trajectories, competitive dynamics, and decision levers our full research unpacks. It deliberately signals the actionable implications while withholding select granular segment tables and proprietary model outputs to preserve the report’s commercial value — think of this as a high‑impact trailer that surfaces what matters and why it should shape your 2026 agenda.
Vegetable (HPMC) Capsule Market
Why this market matters in 2026
-
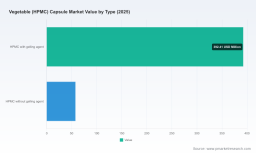
Resilient growth trajectory: The global vegetable (HPMC) capsule market demonstrated steady expansion through 2020–2025 and enters 2026 on an accelerated growth path. Our base‑year assessment (2025) positions the market at approximately USD 450 million (revenue, USD Million), with compound annual growth projected at roughly 8.4% across the 2026–2032 forecast window. This growth profile materially outpaces many adjacent specialty excipient and packaging segments, reflecting persistent demand from both pharmaceutical and nutraceutical end markets.
Vegetable (HPMC) Capsule Market -
Strategic inflection points: Three concurrent structural forces — regulatory tightening in major markets, supply‑side capacity shifts, and evolving buyer preferences toward plant‑based and clean‑label dosage forms — are converging to create both risk and opportunity for incumbent suppliers and downstream formulators.
Vegetable (HPMC) Capsule Market -
Decision urgency: For 2026 strategic planning, executives must evaluate supply security, regulatory risk exposure, cost pass‑through mechanisms, and partnership structures (e.g., tolling, strategic supply agreements, co‑development) rather than wait for price signals alone. The market is large enough to justify dedicated sourcing and regulatory teams, yet concentrated enough that supplier moves cause system‑wide ripple effects.
What the full study delivers — operational, transaction‑ready intelligence
-
Market sizing and outlook: A transparent reconciliation of historical performance (2020–2025) to a scenario‑based forecast (2026–2032), with bottom‑up validation and sensitivity testing against raw material price trajectories and energy cost shocks.
-
Supply chain and capacity mapping: A global atlas of manufacturing capacity, technology footprints (HPMC vs pullulan and hybrid offerings), and capital projects. We map where capacity is growing, where bottlenecks are likely to emerge, and how lead times will evolve under different demand scenarios.
-
Regulatory matrix and compliance playbook: Practical guidance on navigating recent tightening — including updated US FDA guidance for dietary ingredient notifications and recent EFSA administrative revisions — and a compliance checklist prioritized by market impact.
-
Commercial playbooks: Tailored go‑to‑market and procurement templates for pharmaceutical clients, contract manufacturers, and supplement brands that include supplier scorecards, negotiation levers, and escalation playbooks for substitution or dual‑sourcing.
-
Pricing and margin modelers: Interactive frameworks that let commercial leaders simulate the P&L impact of raw material swings, energy surcharges, freight disruptions, and currency movements on capsule cost‑per‑thousand‑units.
-
M&A and partnership intelligence: Target screens, value creation templates, and integration checklists for buyers seeking scale or capability (e.g., delayed‑release expertise, pullulan capabilities, regional plant footprints).
-
Risk heatmaps: Quantified exposure matrices — regulatory, trade (including anti‑dumping and import investigations), raw material price, and ESG/sustainability risks — prioritized by likelihood and impact.
Competitive landscape — who to watch and what their moves mean
The vegetable capsule market is served by a set of global leaders and regional specialists. Several dynamics are shaping competitive positioning in 2026:
-
Large capsule producers are consolidating scale and expanding geographic proximity to end markets. Recent capacity investments and green‑field launches illustrate an emphasis on shortening lead times and delivering multi‑formulation portfolios (HPMC, pullulan, gelatin) from single suppliers. Such investments reduce logistics risk for large customers but increase negotiation pressure on smaller CMOs and independent suppliers.
-
Strategic corporate transactions are re‑shaping ownership and capital intensity in the segment. A notable 2026 transaction transferred a major capsule business into private equity hands, recalibrating strategic priorities toward margin improvement, commercial optimisation, and selective bolt‑on acquisitions. Buyers and partners should expect a more commercially aggressive posture from assets under financial ownership in the near term.
-
Regional champions with large installed capacity continue to play a price‑sensitive role in global supply chains, while certified specialty suppliers—those with robust GMP, FDA and EMA credentials and niche offerings like delayed‑release HPMC formulations—capture premium segments in pharmaceuticals and high‑value nutraceuticals.
Representative profiles (high level):
-
ACG Worldwide — a global headliner deploying both capacity expansion and new facilities to secure market share in major geographies; targeted investments indicate a strategy of vertically integrated supply and localised production for strategic markets.
-
Suheung Capsule — a specialist known for certified vegetarian capsule brands and regulatory credentials attractive to pharmaceutical customers seeking validated supply.
-
Shanxi Guangsheng — a high‑volume producer whose scale pressures global price dynamics and provides a strategic buffer to tight markets when energy and feedstock allow ramp‑ups.
-
Natural Capsules, HealthCaps India, CapsCanada, Roxlor, Vitaquest, Silvaco — a mix of regional leaders and niche specialists supplying differentiated formulations and service models, from custom manufacturing to branded vegetarian capsule shells.
Recent company‑level developments are instructive for 2026 strategy. Examples we track: a major manufacturer announced a phased, multi‑hundred‑million dollar investment to establish first‑in‑market empty capsule facilities in the United States; another initiated operations at a new Asian manufacturing plant focused on hard shells; several regional players expanded installed capacity to capture rising supplement demand. Concurrently, a strategic sale of a prominent global division to a private equity acquiror has realigned competitive incentives and may accelerate a wave of optimisation and tuck‑ins across the value chain.
Regulatory and raw‑material environment — risk vectors that must be modelled
-
Regulatory tightening in the United States and the European Union is not hypothetical — updated guidance and administrative revisions enacted across 2025–2026 increase compliance burdens for new ingredients, labelling, and dossier requirements. Companies must map product portfolios against these new checkpoints to avoid market disruptions.
-
Trade and enforcement risks: ongoing investigations into imports of empty hard capsules have elevated the probability of tariffs, quotas, or remedial duties. Procurement strategies that once relied on single‑source low‑cost corridors now require contingency planning and tariff‑aware cost modelling.
-
Raw material and energy cost volatility: HPMC feedstock pricing showed relative stability in late 2025 in some regions but upward pressure earlier in the year due to rising production costs and energy instability. These dynamics translate into margin compression for manufacturers and cost passthrough negotiations with buyers — especially when long lead times and capacity constraints are present.
Strategic implications for executives in 2026
-
Secure multi‑tier supply: Locking in capacity through strategic contracts, tolling agreements, or equity partnerships should be prioritised for companies with critical launch timelines or narrow formulation windows.
-
Stress‑test pricing and contract terms: Use the report’s pricing modelers to stress test outcomes under energy shocks, trade restrictions, and regulatory delays. Structure contracts with clear escalation clauses, quality penalty frameworks, and mutual contingency plans.
-
Invest in regulatory preparedness: Prioritise dossier completeness for target markets and adopt a proactive approach to novel ingredient notification processes to avoid launch windows slipping due to administrative non‑compliance.
-
Pursue selective vertical integration: For firms dependent on a small set of suppliers, acquiring tolling capacity or entering JV arrangements can be a defensible hedge against supply shocks, particularly where delayed‑release or specialty functionalities are strategic differentiators.
-
Evaluate M&A and partnering opportunities: The market’s capital reallocation and recent divestitures create windows for strategic acquisition at attractive valuations. Consider targets offering regulatory certification, unique formulation IP, or geographic access to high‑growth nutraceutical channels.
Next steps — how PW Consulting helps
-
Our full report equips leadership teams with the granular datasets, regional capacity maps, supplier scorecards, and deal playbooks necessary to convert insight into action. It provides the calibrated, up‑to‑date scenarios you need to prioritise capital, renegotiate supply, or accelerate product roadmaps in 2026.
-
We recommend a three‑tier engagement for 2026 planning: (1) a rapid diagnostic to stress‑test current supply contracts and regulatory exposure, (2) a scenario workshop utilising our forecast and pricing toolset to quantify upside and downside, and (3) an execution phase — supplier negotiations, target screening, or compliance remediation — supported by our industry transaction specialists.
To preserve the strategic value of the full study, we have deliberately withheld some proprietary segment tables and pricing elasticity matrices in this preview. Those datasets — including detailed regional and application splits, facility‑level capacity figures, and transaction comparables — are available in the complete PW Consulting market report. For leaders making 2026 decisions, the full report converts uncertainty into executable choices: who to partner with, where to invest, and how to contract for resilience and margin protection.
PW Consulting stands ready to translate this market intelligence into a prioritized action plan tailored to your commercial, manufacturing, or M&A objectives. Use the insights above to identify your highest‑leverage strategic questions; our team can then deliver the operational detail you need to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Vegetable (HPMC) Capsule Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


