



PW Consulting: Bluetooth Headsets Market to Reach USD 24,159.23M by 2032; 8.0% CAGR (2026–2032)

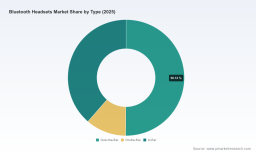
Bluetooth Headsets Market — Strategic Preview for 2026 Decision-Makers
As organizations plan product roadmaps, channel investments and M&A activity for 2026, the Bluetooth headsets market presents both an accelerating growth trajectory and a shifting technical foundation that will re-rank winners and losers over the next business cycle. This preview synthesizes the high‑level, data-driven signals you need to shape near-term strategy while deliberately withholding the granular segmentation tables and proprietary scorecards found in our full report — an approach designed to demonstrate analytical depth while inviting the targeted stakeholder engagement that converts insight into action.
Bluetooth Headsets Market
Market snapshot: momentum and scale
PW Consulting’s base-year calibration (2025) frames the Bluetooth headsets market as a sizable, expanding opportunity. After consistent expansion through 2020–2025, the market stood at approximately USD 14,096.7 million in 2025. Our model projects continued growth through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 8.0%, culminating in an expected market size north of USD 24 billion by 2032.
Bluetooth Headsets Market
Two practical takeaways for 2026 planning: first, the market is now large enough that incremental share gains yield material revenue upside for mid‑sized vendors; second, the steady mid‑single-digit to high‑single-digit growth rate means product cadence, cost structure and go‑to‑market efficiency will be decisive for profitability as many categories mature.
Bluetooth Headsets Market
Concentration and competitive dynamics
The market exhibits a mixed concentration profile: the top three players account for a meaningful but not dominant share of industry revenues, while the top five capture a compact majority, leaving room for regional specialists and product-focused challengers. A CR3 of ~39% and CR5 of ~62% highlights a market where scale confers advantages (channel access, R&D leverage, OEM partnerships) but where tactical differentiation still enables rapid share shifts.
- Implication: Consolidation and bolt-on acquisitions will remain an active play for organizations seeking distribution scale or rapid technical capability injection.
- Implication: Niche specialists that own a customer experience (e.g., enterprise conferencing, gaming immersion, fitness durability) can sustain healthy margins despite not being among the top five.
Technology and regulation: what changed in 2025–2026
Two Bluetooth SIG milestones reframe product and platform decisions for 2026:
- May 2025 — Bluetooth Core 6.1: introduces Randomized Resolvable Private Address (RPA) updates that materially improve device privacy profiles and power efficiency for Bluetooth peripherals. The immediate consequences are both regulatory and product-oriented: device lifetime and firmware update cadences will determine whether a device remains compliant and competitive.
- October 2025 — Bluetooth roadmap with High Data Throughput (HDT): HDT is scheduled for a phased release beginning in 2026 and is poised to address long-standing latency and bandwidth constraints for wireless audio streaming.
Strategic consequences:
- Privacy and power efficiency are now baseline buyer expectations in enterprise and consumer segments. OEMs must plan firmware roadmaps and certification pipelines to avoid product downgrades in the field.
- HDT opens a pathway to higher-fidelity streaming and lower-latency applications (competitive gaming, professional audio, multipoint conferencing). Early movers that integrate HDT-capable silicon and demonstrate real-world use cases will capture a pricing premium.
Competitive landscape — what incumbents are doing
We surveyed the leading vendors to isolate differentiated plays that will matter in 2026 procurement cycles. Below are profiles and strategic implications for five market-defining competitors (links supplied for direct reference):
- Jabra (Denmark) — https://www.jabra.com/ Jabra’s Evolve line persists as a reference design for professional wireless office headsets, with advanced ANC and call clarity as core value propositions. Their strength is in enterprise feature integration (platform interoperability, device management) rather than speculative premium audio experiments.
- Poly (United States) — https://www.hp.com/us-en/poly.html Poly competes on enterprise ergonomics and voice‑centric innovation; boomless designs and adaptive ANC position them well for hybrid-work deployments where device aesthetics and meeting-room integration matter.
- EPOS (Denmark) — https://www.eposaudio.com/en/us EPOS emphasizes noise-cancellation performance and audio clarity for business users; their go-to-market is anchored in premium enterprise contracts and channel relationships with unified‑communication vendors.
- Yealink (China) — https://www.yealink.com/en Yealink’s portfolio leans into DECT and dual‑speaker designs for office collaboration, reflecting a strategy to own the "conference endpoint" rather than play purely in consumer audio.
- Sony (Japan) — https://electronics.sony.com/audio/headphones/c/all-headphones Sony remains a reference in consumer audio: over‑ear and in‑ear Bluetooth headsets that emphasize studio‑quality sound and ANC — a valuable benchmark for margin and desirability in premium segments.
Across these vendors, the common strategic threads are: aggressive ANC roadmaps, ecosystem certifications (platform and conferencing), and differential bundling of software services (device management, analytics, security). For challengers, the path to scale is either deep vertical integration (fit-for-purpose solutions) or focused global channel partnerships.
Where PW Consulting’s full study adds operational value
Our full Bluetooth Headsets Market research is built to inform executable decisions in 2026. The report blends quantitative forecasting with tactical modules decision-makers use immediately:
- Robust market model (historical 2020–2025 calibration; forecast 2026–2032) with downloadable tables and sensitivity scenarios.
- Buy-side persona maps and use-case economics to size commercial vs. consumer opportunity at actionable granularity.
- Product landscape matrix that evaluates ANC performance, latency, battery profiles, and certification readiness (Bluetooth Core 6.1 and HDT alignment flagged).
- Channel and pricing playbook highlighting distribution economics, bundling strategies, and margin levers across retail, B2B direct and platform partners.
- Supply-chain risk register covering key components (silicon, MEMS mics, battery), lead‑time scenarios and cost pass‑through models for 2026.
- Competitive scorecards and M&A target watchlist (qualitative flags and decision criteria — detailed valuations are available in the premium dataset).
- Implementation templates: go‑to‑market checklists, firmware-update governance frameworks, and enterprise procurement tender language to de‑risk rollouts.
We intentionally withhold segmented tables and company-level financial estimates from this preview to protect the proprietary analytics that power those templates — but the full report contains those fields and the underlying raw data for client evaluation.
Strategic recommendations for 2026
For executives setting budgets and targets in 2026, prioritize three pragmatic moves:
- Lock in Bluetooth 6.1 compliance and HDT readiness: Treat firmware and silicon roadmaps as strategic assets. Devices that cannot adopt RPA updates or HDT extensions will face accelerated commoditization and increased return risk in enterprise deployments.
- Segmentation by use-case, not form-factor: Overlap across “fitness,” “enterprise conferencing” and “gaming” user requirements is increasing. Reframe R&D and marketing around use-case experiences (latency, form-fit, battery life, ruggedization) rather than chassis categories alone.
- Optimize route-to-market with service differentiation: Software-driven services (device management, analytics, warranty programs) convert one-time hardware sales into recurring revenue. Prioritize partnerships with platform providers and enterprise resellers that can accelerate adoption in volume deployments.
Additionally, investors and corporate development teams should accelerate due diligence on targets that provide immediate access to either enterprise distribution or HDT-capable IP; those assets compress time-to-value in an environment where standardization cycles (Bluetooth SIG roadmaps) are shortening.
Final note — why this matters for 2026
2026 will be the first full year in which the protocol-level changes introduced in 2025 materially influence procurement and product cycles. Vendors that treat Bluetooth as a passive commodity risk being outpaced by firms that integrate protocol advances into product experience, security, and lifecycle services.
PW Consulting’s full Bluetooth Headsets Market study contains the quantitative segmentation, vendor benchmarking and playbooks necessary to operationalize the above recommendations. If you are evaluating portfolio pivots, preparing an acquisition thesis, or setting FY2026 R&D priorities, the full dataset and our advisory services shorten execution time and reduce error. Visit our report landing page to access the complete table package, vendor scorecards and subscription options for ongoing bespoke modeling.
For detailed analysis of this topic, please visit the official page: Bluetooth Headsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


