



PW Consulting: Planter Market to Reach USD 2,376M by 2032 at 5.0% CAGR

Planter Market 2026 Outlook: Strategic Imperatives for Agribusiness Leaders
Executive summary
As agribusinesses prepare 2026 capital allocation and product roadmaps, the planter market sits at an inflection point driven by rapid technology adoption, supply-chain volatility and shifting regulatory pressures. PW Consulting’s latest Planter Market study uses 2025 as the base year and traces historical dynamics from 2020–2025, then projects the market through 2032. The market reached approximately USD 1.69 billion in 2025 and, at an expected compound annual growth rate of about 5% through 2032, is set to expand materially over the coming business cycles. Our analysis synthesizes macro demand drivers, vendor capability maps, and pragmatic decision frameworks designed to convert insight into deployable strategies in 2026.
Planter Market
Why this report matters for 2026 decision-making
-
Timing of investment: With precision agriculture and automation moving from pilot to scale, 2026 is a pivotal year for firms deciding whether to accelerate productization, pursue partnerships, or prioritize after‑sales service investments. The report identifies where near-term ROI is realistically achievable and where patient capital is required.
Planter Market -
Portfolio prioritization: Our findings enable executives to triage R&D and go‑to‑market budgets by pairing technological capabilities (e.g., seed placement precision, row-by-row control, automated depth adjustment) with likely adoption curves across farm sizes and crop types.
Planter Market -
Risk calibration: From tariffs on steel/aluminum to evolving EU labeling and state-level herbicide restrictions, the study provides decision-ready scenarios for sourcing, pricing and compliant product design.
Market trajectory and what the headline numbers mean
The planter market’s expansion from the 2025 base reflects steady, technology-led growth. At roughly USD 1.69 billion in 2025, the sector’s mid-single-digit CAGR through 2032 implies an industry that is neither hyper‑volatile nor fully mature—offering predictable expansion with pockets of rapid change. For incumbent manufacturers and new entrants alike this translates into two practical implications:
-
Scale matters, but specialization pays. The market concentration metrics (top‑three firms holding roughly a third of market value and the top five approaching mid‑forties percentile share) show meaningful leadership, yet substantial opportunity remains for focused specialists and regional champions.
-
Technology intensifies differentiation. Adoption of automated seed metering, real‑time depth control, and integrated fertilizer applicators—when combined with data services—creates recurring revenue pathways beyond the initial equipment sale.
Competitive landscape — positioning the leading players
Our competitive analysis profiles core OEMs and innovators across capability clusters: high‑speed precision planters, integrated seed‑and‑fertilizer applicators, specialty crop planters (e.g., potato), and light/high‑mobility systems suited for emerging markets. Key insights:
-
John Deere continues to lead on integrated precision and automation, leveraging technologies like ExactEmerge™ and increasingly rolling out targeted starter fertilizer solutions (ExactShot expansion in early 2026). Deere’s playbook focuses on bundling hardware with connectivity and agronomic services to lock in lifetime value.
-
CNH Industrial (Case IH / New Holland) is sharpening real‑time seed placement and telemetry integration across its Early Riser platforms. Recent automation enhancements (February 2026) underline CNH’s approach of platform continuity combined with incremental electronics upgrades—minimizing farmer switching costs.
-
AGCO is capitalizing on adaptive planting depth and shot control through SmartDepth and SmartShot features. AGCO’s strategy centers on modularity—allowing customers to cascade technology upgrades rather than replacing entire rigs.
-
Kinze , Väderstad , and specialized European OEMs (e.g., Terrateck, TEHNOS, GRIMME) defend niches where mechanical innovation and crop‑specific know‑how are decisive. Kinze’s 2026–2027 configuration launches and Väderstad’s Central Fill system upgrade (late 2025) exemplify competition through targeted product improvements aimed at operational throughput and logistics efficiency.
-
Kuhn , Mahindra and other regional players are influential where localized service networks and tractor integration matter most—particularly for specialty crops and emerging market demands.
For buyers and investors, the message is clear: vendor selection is as much about an OEM’s roadmap and aftermarket ecosystem as it is about current machine performance.
Regulatory, cost and supply‑chain dynamics shaping 2026 plans
External dynamics are accelerating strategic re-evaluations. Our research incorporates recent developments that materially affect pricing, deployment and compliance decisions:
-
New regulatory requirements—such as updated EU labeling for plant protection products—create compliance timelines and redesign costs for integrated applicator systems. Manufacturers should anticipate product updates and documentation support as non‑discretionary expenditures in 2026–2027.
-
Precision adoption is changing input economics. Evidence indicates precision farming practices have altered herbicide usage patterns and costs—raising herbicide expense exposure for U.S. farmers and increasing demand for applicators that optimize input placement.
-
State‑level restrictions on certain herbicide applications introduce geographic heterogeneity in product demand; companies must consider configurable applicator options and flexible firmware rules to maintain market access.
-
Tariffs on steel and aluminum complicate domestic manufacturing economics. Our supply‑chain scenario models quantify cost exposure and identify hedging strategies—ranging from regional sourcing to long‑term supplier contracts.
-
Labor cost pressures persist. More than half of surveyed farmers report rising crew and maintenance costs, strengthening the business case for higher‑automation planters that reduce operator time per hectare.
Report contents — what’s inside and how it’s actionable
The PW Consulting Planter Market report is designed as a playbook for executives. It delivers:
-
Market sizing and forecast (2020–2032) with scenario variants tied to technology adoption rates and commodity price sensitivity.
-
Competitive capability maps and vendor scorecards that evaluate mechanical performance, digital integration, service network depth and aftermarket monetization potential.
-
Commercial benchmarks for pricing, total cost of ownership models, and payback analyses across representative farm archetypes.
-
Go‑to‑market frameworks including channel strategy, dealer economics, and recommended service offerings to drive recurring revenue.
-
Supply‑chain risk playbooks addressing raw‑material tariffs, logistics disruption, and localized parts provisioning strategies.
-
Regulatory impact scenarios with product adaptation checklists and compliance timeline templates to coordinate engineering and certification efforts.
-
Implementation roadmaps for OEMs and large distributors: pilot designs for technology rollouts, partner evaluation matrices, and a prioritized list of short-term catalysts that will materially affect 12–24 month outcomes.
How competitors are evolving — recent tactical moves
Our monitoring of industry announcements through early 2026 indicates a wave of tactical software and hardware upgrades rather than wholesale new platform introductions. Notable moves include:
- John Deere’s early‑2026 expansion of ExactShot for metered fertilizer placement, reinforcing productized agronomy as a differentiation lever.
- CNH’s addition of real‑time seed placement monitoring and expanded AFS connectivity to Early Riser systems, lowering adoption friction for precision farming customers.
- Väderstad’s late‑2025 Central Fill upgrades that improve seed flow logistics—an operational advantage in high‑throughput planting windows.
- AGCO’s incremental SmartDepth improvements that automate planting depth based on soil conditions, demonstrating the competitive premium for robust sensing + actuation stacks.
- Kinze’s 2026–2027 configuration launches aimed at specific row spacing and track configurations to capture defined agronomic niches.
These moves indicate an industry focused on gradual capability densification—firms are layering electronics, connectivity and machine learning over proven mechanical platforms to de‑risk product acceptance.
Strategic actions for 2026
-
For OEMs: Prioritize modular electronics and software that can be retrofitted to existing frames. This reduces capital intensity and accelerates revenue realization from connectivity services.
-
For distributors: Expand service capabilities and parts availability in planting season hotspots; shift dealer compensation toward uptime and data‑service subscription targets.
-
For investors and M&A teams: Target regional specialists and data‑service providers that complement leading mechanical OEMs but lack scale—these acquisitions create asymmetric value when integrated with a large hardware platform.
-
For policymakers and large buyers: Use procurement levers to demand modular compliance features (e.g., configurable firmware limits, labeling workflows) that reduce product redesign costs across markets.
Where the study leaves optionality — and what we intentionally withheld
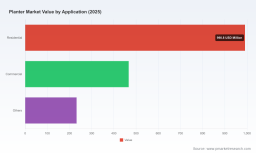
To balance transparency with strategic confidentiality, this overview highlights headline market size and growth trajectory while intentionally withholding granular subsegment allocations and region/application percentages that are included in the full PW Consulting report. These detailed splits—covering by‑region, by‑type and by‑application revenues and detailed CR analyses—are presented in the full study alongside downloadable models and interactive scenario tools. That level of granularity is often the deciding factor for bidders, OEM product teams and M&A due diligence units; we direct those readers to the source report for the full data set and downloadable financial models.
Conclusion — positioning for advantage in 2026
The planter market’s evolution over 2026 will reward firms that combine pragmatic engineering (reliable mechanics) with rapid digital enablement (sensing, telemetry, and services). The market’s steady growth profile—anchored in a mid‑single-digit CAGR from 2026–2032 and concentrated among a handful of leaders—creates an environment where differentiated technology, robust dealer networks and flexible compliance strategies determine winners. PW Consulting’s Planter Market study equips executives to make those 2026 decisions with confidence, offering both the macro context and the actionable detail required to translate market signals into commercial advantage.
For detailed analysis of this topic, please visit the official page: Planter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


