



PW Consulting: Allyl Alcohol Market to Reach USD 2.6 Billion by 2032 at 4.2% CAGR

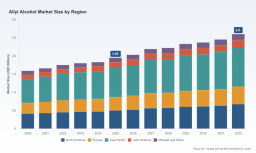
Allyl Alcohol Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As corporate leaders plan capital allocation, supply-chain redesign and product strategy for 2026, a focused understanding of niche intermediates such as allyl alcohol becomes a strategic advantage. Our forthcoming Allyl Alcohol Market study (base year 2025, historical window 2020–2025, forecast horizon 2026–2032) synthesizes macro trajectories, production-route economics, regulatory constraints and competitive positioning into an operational playbook. In this preview, PW Consulting outlines the high-level takeaways that should shape boardroom discussions this year while preserving the full, transaction-ready intelligence for subscribers to the complete report.
Allyl Alcohol Market
Why allyl alcohol matters to 2026 strategy
Allyl alcohol sits at the intersection of specialty chemicals and performance materials: it is both a feedstock for high-value downstreams (e.g., BDO derivatives, specialty resins and coupling agents) and a bellwether for shifts in propylene-derivative value chains. From 2020 to 2025 the market expanded steadily, reaching approximately USD 1.95 billion in 2025. Under baseline expectations, our model projects continuation of that trajectory through the forecast window, culminating near USD 2.6 billion by 2032, representing a compound annual growth rate of roughly 4.2% for 2026–2032.
Allyl Alcohol Market
That rate signals a market that is neither hypercyclical nor saturated; instead it rewards selective capacity additions, route optimization and integrated value-capture. For 2026 decision-making, companies should treat allyl alcohol as a strategic lever — an input whose sourcing, route selection and logistics options can materially affect margins across multiple downstream product lines.
Allyl Alcohol Market
Key market dynamics shaping 2026 decisions
- Feedstock cost pass-through and integration premium.
Propylene-cost volatility is a dominant theme. Observed price movement from early‑2024 into late‑2025 drove significant raw‑material inflation for propylene-derived intermediates; industry consensus and our scenario work indicate further upward pressure into 2026. Non-integrated producers face a measurable per‑tonne cost exposure relative to integrated peers, making integration or firm long‑term feedstock contracts a high-priority risk mitigation strategy.
- Production-route economics and operational footprint.
Multiple established routes (including propylene oxide isomerization, allyl chloride/acetate hydrolysis and acrolein hydrogenation) deliver differing cost structures, impurity profiles and downstream suitability. Route choice is not merely a capex decision — it influences product specifications, logistics complexity and safety compliance obligations. Firms should align route investments with targeted downstream markets rather than pursuing capacity expansion in isolation.
- Regulatory and logistics constraints.
Allyl alcohol is classified under international dangerous‑goods regimes with specific transportation and containment requirements. It is subject to hazardous‑materials classifications that restrict certain modes of transport and trigger domestic safety regimes (e.g., RMP/PSM in the U.S.) at defined handling thresholds. These regulatory constraints translate to real cost lines: packaging, specialized containers, restricted freight options and enhanced on‑site process safety programs.
- Concentration and competitive dynamics.
Market concentration is material: the top three producers account for a majority share and the top five raise that concentration further. That market structure produces opportunities for mid‑sized players: premiumization through high‑purity grades, logistical service differentiation, niche regional supply or downstream co‑development can yield outsized returns where scale alone is not the sole determinant of win‑rates.
What the full PW Consulting report delivers (practical outputs)
We designed the study for decision-makers who require both strategic clarity and executable detail. Highlights of the practical content you will find in the full report include:
- Granular supply-demand modeling calibrated to historical shipment data and validated through supplier and distributor interviews, enabling near‑term volume and price scenarios for 2026 planning.
- Cost‑curve analysis by production route, including fixed and variable components, feedstock sensitivity, catalyst and utility consumption profiles.
- Transport and logistics playbook covering packaging specifications, modal constraints, typical insurance and freight schedules, and an HS‑code mapping to inform cross‑border tariff planning.
- Regulatory compliance checklist: international classifications, threshold-based reporting obligations, recommended PSM/RMP controls and a phased CAPEX plan for compliance upgrades.
- Commercial playbook for market entry or growth: customer segmentation, contracting best practices, price-indexing strategies and suggested service bundles for premiumization.
- M&A and JV screening toolkit: value drivers, integration synergies, typical multiples observed for specialty alcohol intermediates and a shortlist of bolt‑on and scale candidates (including due‑diligence red flags).
- Risk matrix and scenario simulations covering feedstock shocks, transport disruptions, regulatory tightening and demand‑side substitutions, with mitigations prioritized by cost‑to‑implement and impact‑reduction.
- Proprietary supplier profiles and capability maps, covering production routes, capacity posture, quality certifications, and strategic priorities distilled from primary interviews.
We deliberately withhold the full segmentation tables and channel-level forecasts in this executive preview to preserve the actionable specificity that subscribers rely on for transactions and contracting. The full dataset and modelling workstreams are accessible to clients through the report portal.
Competitive landscape — what to watch in 2026
The competitive fabric of the industry blends integrated commodity players with specialist high‑purity producers. Several archetypes dominate:
- Integrated petrochemical majors.
These players leverage upstream propylene or propylene oxide integration and flexible downstream routing to protect margins. Their strategic advantages include feedstock hedging, captive logistics and global customer reach. However, they often compete on volume and breadth rather than purity or niche service.
- High‑purity specialists.
Market leaders in this category have leaned into product quality and tailored supply for electronics, pharmaceutical intermediates and specialty polymers. Recent capacity investments by one leading specialist underscore continued demand for certified, high‑spec grades and the willingness of customers to pay for consistency and chain‑of‑custody assurances.
- Regional producers with logistical advantages.
Producers with proximate manufacturing clusters to downstream converters (or with multi‑site footprints across relevant jurisdictions) can offset tariff and freight volatility — a differentiator in near‑regionalized procurement strategies.
Notable company actions are already reshaping capacity and capability dynamics. Capacity expansions from high‑purity producers completed in 2025 and continued into 2026 have strengthened their export posture, and certification efforts by regional producers underscore a push toward lower‑carbon product credentials. Concurrently, several established chemical conglomerates maintain multi‑route production capabilities that support downstream integration strategies.
Immediate strategic moves for 2026
- Audit feedstock exposure today.
Model the P&L impact of a USD‑100–250/tonne swing in propylene costs under both passthrough and contracted supply scenarios. For many firms this sensitivity analysis will re‑rank project IRRs and affect procurement terms for 2026.
- Prioritize route‑aligned investments.
CapEx should target routes that align with the firm’s downstream margin pool. For companies servicing high‑purity applications, incremental investment in polishing and quality assurance yields better payback than undifferentiated capacity additions.
- Lock logistics and compliance early.
Given transport restrictions under international hazardous‑goods rules, securing qualified carriers, containers and insurance capacity for 2026 is a competitive necessity — late procurement can materially delay commercial shipments.
- Explore commercial hedges and partnerships.
Long‑term offtakes, joint investments in upstream feedstock or toll‑manufacturing partnerships can protect margins and accelerate market access without bearing the full burden of capex.
How PW Consulting supports your 2026 roadmap
Our full Allyl Alcohol Market report provides the detailed datasets, route‑level cost models and supplier assessments that procurement, strategy and M&A teams require to make confident, time‑sensitive decisions. Subscribers gain access to reproducible models, a vendor scoring matrix, and a playbook for negotiations and operational upgrades aligned to 2026 timelines.
To deploy the insights summarized here, boards and executive teams should pair our scenario outputs with internal operations and commercial planning cycles now — the window to secure favorable feedstock contracts, logistics capacity and strategic partnerships is open, but it narrows as 2026 approaches.
Next steps
- Download the full PW Consulting Allyl Alcohol Market dossier for the complete segmentation, transactional datasets, and editable cost models.
- Arrange a workshop with our industry team to map the report findings onto your 2026 capital and procurement plan.
- Request a confidential supplier‑screening model tailored to your target downstream applications and regional footprint.
Allyl alcohol will not be a headline‑grabbing commodity in 2026, but it will be a decisive variable for any company with exposure to BDO derivatives, specialty resins or coupling agents. PW Consulting’s analysis gives you the situational awareness and operational prescriptions to turn that variable into strategic advantage.
For detailed analysis of this topic, please visit the official page: Allyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


