



PW Consulting: Blu-ray Player Market Set to Hit USD 307M by 2032, 5.5% CAGR

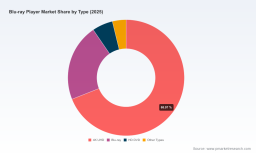
Blu-ray Player Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s senior strategy team, we present an executive preview of our Blu-ray Player Market study — a focused, decision-ready intelligence brief crafted to guide commercial, product and investment choices through 2026 and beyond. This preview demonstrates the report’s analytical depth and practical orientation while intentionally withholding granular segment-level datapoints to preserve the value of the full deliverable.
Blu-ray Player Market
Why this market matters in 2026
After a sustained recovery through the early 2020s, the Blu-ray player market stands at a strategic inflection. From roughly USD 150 million in 2020, the market expanded to USD 210 million by the 2025 base year. Our forecast in the full study anticipates a mid-single-digit compounded annual growth rate (CAGR) of 5.5% across the 2026–2032 horizon, producing a noticeably larger market by 2032. That trajectory reflects a combination of persistent premium hardware demand, upgraded disc formats, and a niche but resilient installed-base replacement cycle — even as streaming continues to reshape consumer habits.
Blu-ray Player Market
For executives weighing capital allocation, product roadmaps, channel investments or M&A options in 2026, these macro dynamics matter. A stable market expansion at an identifiable CAGR enables more confident scenario planning than many adjacent consumer electronics categories that face binary outcomes from platform shifts. But beneath the headline growth, strategic complexity abounds: supply-chain fragility, premium-segment consolidation, regulatory noise and shifting retail economics all converge to create both risk and opportunity.
Blu-ray Player Market
What PW Consulting’s study delivers (operational scope)
- Robust market-sizing and trend foundation — transparent methodologies that reconcile historical shipment, retail and manufacturer-reported data to produce an auditable market baseline and alternative scenarios through 2032.
- Scenario-driven forecasts — three policy- and supply-sensitive scenarios (Base, Constrained Supply, and Accelerated Premium Adoption) that let C-suite leaders stress-test CAPEX, inventory and go-to-market choices.
- Supply-chain diagnostics — component-sourcing heatmaps, lead-time and cost escalation matrices, single-point-of-failure identification and supplier-switching cost models designed to speed procurement decisions.
- Commercial playbooks — go-to-market templates for OEMs and channel partners covering pricing elasticity, bundling with streaming services and content partners, retail vs D2C channel economics, and promotional cadence calibration.
- Corporate finance tools — an M&A screening toolkit with synergy quantification, buy-vs-build calculators for optics/drives/manufacturing, and a valuation sensitivity suite tied to the report’s scenario outputs.
- Competitor analytics and benchmarking — positioning maps, product-feature matrices, and win/loss archetypes that illuminate where incumbents and potential entrants can find defendable niches.
How the study informs 2026 decision-making — strategic use-cases
- Portfolio prioritization: Use our scenario models to rank product investments by expected margin expansion and payback under constrained-component vs. unconstrained environments.
- Channel strategy: Evaluate the shifting economics of brick-and-mortar retail vs. direct-to-consumer premium channels, using our channel P&L templates to pinpoint where promotional spend converts to incremental lifetime value.
- Supply resilience: Translate the supply-chain heatmap into near-term tactical decisions — alternate-sourcing triggers, buffer inventory allocation, and contract-length levers for critical components.
- M&A and partnerships: Identify targets that accelerate access to high-margin segments or proprietary decoding/licensing advantages, using our M&A screening outputs to prioritize targets for diligence.
- Regulatory and cost shock planning: Incorporate tariff- and duty-related scenarios into pricing models; our regulatory-impact sensitivity shows how cross-border retail economics shift under higher import effective costs.
Competitive landscape — actionable insights (what we analyze)
The market is moderately concentrated: the leading three players account for roughly a third of industry revenue, and the top five combine for around two-fifths. That structure creates a contestable field where well-executed niche plays and supply-chain control can meaningfully change positioning.
- Sony (Tokyo, Japan) — Sony remains a mainstream manufacturer with products that span accessible home models to higher-tier 4K UHD players supporting streaming integration. Our analysis highlights Sony’s advantages in brand, software integration and ecosystems. The key strategic question for Sony in 2026 is balancing advances in streaming-focused consumer experiences with sustaining hardware margins in premium discs and playback fidelity.
- Panasonic (Osaka, Japan) — Panasonic continues to lead the audiophile and premium 4K UHD bracket with well-regarded models incorporating Dolby Vision, HDR10+ support and advanced audio features. Our benchmarking shows Panasonic differentiates through engineering depth and channel relationships in specialty retail. Their challenge is maintaining component availability and pricing discipline as premium consumer budgets realign.
- High-end specialist dynamics — Recent exits from the high-end manufacturing space altered the competitive topology. Component shortages in 2025 precipitated the discontinuation of several niche UHD players, consolidating high-end options and creating an opening for boutique brands that maintain vertical integration or exclusive sourcing arrangements.
In the full report we map vendor strengths and vulnerabilities at the SKU level, but in this preview we emphasize the operational takeaways: securing diversified supplier lists for key decoder chips and optical subsystems, leveraging software integration as a differentiator, and preparing premium product lines with aftermarket services to defend margins.
Macro and policy drivers to factor into 2026 plans
- Supply shocks: Component scarcity remains the single most material short-term risk. The 2025 wave of product discontinuations among boutique manufacturers exposed how thin high-end supply chains can be.
- Trade and tariff changes: Regulatory shifts that affect cross-border low-value purchases materially change consumer pricing dynamics for disc purchases and imported players. As an example of policy risk, recent executive-level changes in trade allowances increased effective landed costs for certain overseas retail purchases by an industry-reported quantum in mid-2025 — a real cost headwind for import-centric private-label and boutique brands.
- Channel evolution: Retail consolidation and streaming bundle dynamics reduce entry friction for non-traditional channels but increase the importance of software and content partnerships for hardware incumbents.
- Consumer segmentation: The market is bifurcating between pragmatic buyers (cost-conscious replacements) and a smaller but growing cohort of premium buyers who prioritize fidelity, legacy collections and integrated home-theater experiences.
Practical recommendations for 2026 execution
- Stress-test product roadmaps: Re-run SKU-level ROIs across our three forecast scenarios and prioritize SKUs that maintain acceptable payback under constrained-supply assumptions.
- Lock strategic supply agreements: Negotiate multi-year, tiered contracts for long-lead semiconductors and optical assemblies with defined supply-release triggers to reduce outage risk.
- Use hybrid channel experiments: Pilot direct-to-consumer premium offerings bundled with service plans in select markets to capture higher lifetime value and control pricing elasticity.
- Consider bolt-on M&A: Pursue acquisitions that secure unique component access or niche brand equity, and model post-acquisition synergies using our built-in M&A valuation templates.
- Prepare for regulatory shocks: Maintain adaptive pricing rules and inventory staging to mitigate sudden increases in landed costs tied to cross-border trade policy.
What this preview withholds — and why you should access the full study
This preview purposefully omits the granular regional, type and application splits and the full SKU-level benchmarking that underpin our conclusions. Those segment matrices, retailer-margin models, and product-feature comparisons are the core assets of the full report and are presented with source-level traceability, sensitivity tables and downloadable scenario models. If your 2026 plans depend on precise channel P&L, SKU-level margin ladders, or target lists for M&A outreach, the full dataset and interactive dashboards in the study are indispensable.
Final note — the strategic value proposition
For leadership teams, the practical value of this Blu-ray Player Market study is straightforward: it converts a volatile mix of technical evolution, supply fragility and shifting consumer preferences into a set of executable decisions with measurable consequences. Whether you are defending a premium product franchise, optimizing cross-border channels, or sizing acquisition targets, the research provides the forecasting discipline, operational diagnostics and commercial templates that enable faster, less risk-prone choices in 2026.
To convert these insights into action, PW Consulting’s full report includes the models, matrices and playbooks referenced here — along with an interactive workshop option that helps teams translate findings directly into quarterly execution plans and one-year financial projections. Contact our industry team to schedule an executive briefing and access the complete dataset.
For detailed analysis of this topic, please visit the official page: Blu-ray Player Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


