



PW Consulting: Precipitated Silicas Market to Reach USD 334.0M by 2032 at 7.85% CAGR

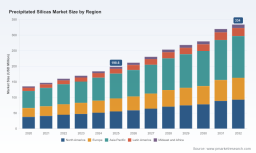
Precipitated Silicas Market — Strategic Outlook for 2026 Decision Makers
As companies prepare capital plans, sourcing strategies and go-to-market moves for 2026, the precipitated silicas market has shifted from a commodity cycle story to a structurally evolving specialty-materials industry. PW Consulting’s latest study, anchored on a 2025 base year and a 2026–2032 forecast horizon, synthesizes five years of historical performance (2020–2025) and projects a multi-year trajectory driven by regulatory change, automotive electrification, localized supply strategies and raw-material volatility. The market expands at a compound annual growth rate (CAGR) of 7.85% in our central forecast, reflecting how demand mix and cost dynamics are re-shaping investment and procurement decisions.
Precipitated Silicas Market
Why this research matters for 2026 strategic choices
-
Actionable macro-to-micro framework. We translate a broad market that grew meaningfully from 2020 through 2025 into decision-ready intelligence for 2026: demand elasticities, supplier scorecards, and scenario-based capex triggers that tell clients when to accelerate expansions or seek capacity via M&A.
Precipitated Silicas Market -
Timing matters. With the market already demonstrating sustained growth into 2025 and projected to continue through 2032, 2026 is a pivotal year to lock in supply chain resilience and secure advantaged manufacturing footprints before the next wave of capacity additions and regulatory costs compress margins.
Precipitated Silicas Market -
Risk-adjusted playbooks. Rising input cost volatility and tighter environmental standards require different risk management than we've seen historically—our report converts those risks into hedgeable actions for procurement, pricing and capital allocation.
Market trajectory — what the top-line shows
PW Consulting’s topline synthesis shows a clear expansion: an established recovery from the early 2020s and a continuation into the early 2030s. The study quantifies the market’s scale at the 2025 base year, and our 2026–2032 outlook embeds a 7.85% CAGR that reflects both volume growth and price/mix improvements. These dynamics are not uniform across end uses: the strongest demand pull originates from tire and rubber formulations aligned with green tire specifications, while industrial, coatings and personal-care segments contribute portfolio stability. To access the detailed, drilled-down tables and regional/application splits, the full report remains the authoritative source—this introduction highlights the strategic implications without reproducing segment-by-segment data.
Dynamics shaping 2026 decisions
-
Regulatory pull and formulation change. Tighter tire-labeling thresholds and OEM specifications in key markets have prompted higher silica loadings in green tire compounds. This structural change transforms silica from a negotiable filler to a performance-critical input; procurement strategies must shift from price-only sourcing to partnership-based supply agreements and technical co-development.
-
Input cost pressure. Acid and alkali feedstock volatility materially affects unit economics. Sulfuric acid and sodium silicate swings—compounded by regional supply disruptions—have driven significant production-cost variability. Our report models sensitivity of margins to raw-material price bands and identifies breakpoints where producers will reassess pricing or curtail production.
-
Environmental compliance and capex. New silica dust and wastewater limits in advanced markets add operating and capital expenditure burdens. For incumbent manufacturers, compliance increases production costs; for new entrants, it raises the bar to scale. We quantify the typical capex and operating uplift required to meet recent standards and outline phased upgrade options that preserve competitiveness.
-
Localization and resilient supply chains. Customer demand and geopolitical considerations are driving near-market capacity builds and the repatriation of strategic feedstock. Corporates evaluating 2026 CAPEX or market-entry moves will find our mapping of plant footprints, time-to-market and cost-to-serve essential to minimize exposure.
Competitive landscape — who matters and why
The market structure sits between fragmented and consolidated: the top-tier players collectively hold a meaningful share of capacity while a long tail of regional producers supplies niche applications. This creates an environment where strategic moves by one or two players can re-rate local supply balances.
-
Evonik Industries AG (Essen, Germany) — Evonik is positioning its ULTRASIL® and ZEODENT® platforms to capture growth in high-performance tire and specialty applications. A recent site expansion in Charleston, SC (50% capacity increase) underscores a playbook focused on localizing supply to OEMs and shortening lead times in North America. Expect Evonik to leverage brand strength and technical service as levers to defend premium positions.
-
PQ Corporation (Valley Forge, USA) — PQ’s portfolio of specialty silicas targets green tires, coatings and industrial niches. Strategic acquisitions have broadened their product breadth and geographic reach; PQ’s play emphasizes higher-margin specialty grades and integrated service models for formulators.
-
Qemetica (Warsaw, Poland) — Through the acquisition of a major precipitated silica business, Qemetica has accelerated its ascent in Europe and North America. Its multi-brand strategy and expanded manufacturing footprint create a platform that can compete on both supply scale and regional proximity.
-
Solvay SA & PPG Industries — Both maintain differentiated product lines targeting tire and industrial uses; recent expansions in Asia signal continued investment in growth markets and application development.
-
Cabot, Wacker, Tata and regional players — Cabot and Wacker continue to compete on technology and application know-how, while regional champions (including Indian producers that have expanded capacity in the past 24 months) are optimizing cost-to-serve for domestic and export markets.
Recent strategic moves—capacity add-ons, targeted acquisitions, and plant commissioning—are reshaping the competitive map. Our study includes a consolidated timeline and an acquisition impact model that shows how transactions influence local supply balances, price dynamics and bargaining power across customer segments.
What PW Consulting’s full report delivers (practical outputs)
-
Decision-ready dashboards: Monte Carlo and scenario-run outputs that map demand, price and margin trajectories under alternative raw-material and regulatory regimes.
-
Supplier scorecards: objective metrics on technical capability, geographic coverage, compliance posture, and commercial flexibility to support supplier rationalization and strategic sourcing.
-
Capex and M&A playbooks: quantified break-even cases for greenfield vs brownfield expansion, recommended hurdle rates, and acquisition target screening criteria with post-deal integration checklists.
-
Commercial strategies: pricing-indexation templates, long-term offtake structures for tiered contracts, and go-to-market recommendations for specialty vs commodity offerings.
-
Regulatory and ESG toolkit: costed compliance pathways for new emissions/wastewater limits and an implementation timeline that aligns with corporate net-zero and circular-economy objectives.
-
Procurement hedging models: raw-material index hedges, dual-sourcing blueprints and working-capital optimizations to protect margins during price shocks.
Implications and recommended 2026 plays
-
For manufacturers: prioritize capacity projects that shorten lead times to high-growth end-markets and invest in process improvements that reduce feedstock intensity. Consider selective bolt-on acquisitions to secure feedstock or fill strategic geographic gaps.
-
For OEMs and formulators: lock long-term technical partnerships with silica suppliers and embed co-development clauses to secure first access to specialty grades demanded by evolving tire standards.
-
For investors: target assets with robust environmental permits and proximity to feedstock; regulatory headwinds and feedstock volatility create differentiated valuation uplifts for low-carbon, low-cost producers.
-
For procurement teams: implement forward-buying and index-linked contracts for sulfuric acid and sodium silicate, and stress-test supplier continuity plans under 30–90 day shock windows.
Accessing the intelligence you need
PW Consulting’s Precipitated Silicas Market report is designed as a transactional toolkit for 2026: it converts macro growth and cost trends into executable strategies, tailored supplier plays and investment roadmaps. This introduction highlights the strategic contours—our full analysis contains the granular segment and regional tables, vendor-specific assessments and downloadable models that decision makers use to finalize budgets and negotiation tactics. For access to the complete dataset, scenario model files and company scorecards, consult the full report on PW Consulting’s research portal.
In an industry where a few strategic moves can reconfigure regional supply and where regulatory and feedstock shocks can rapidly compress margins, the right intelligence in 2026 will determine whether organizations lead, follow or react. Our study equips leaders to choose.
For detailed analysis of this topic, please visit the official page: Precipitated Silicas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


